Understanding How Reverse Mortgage Calculators Actually Work
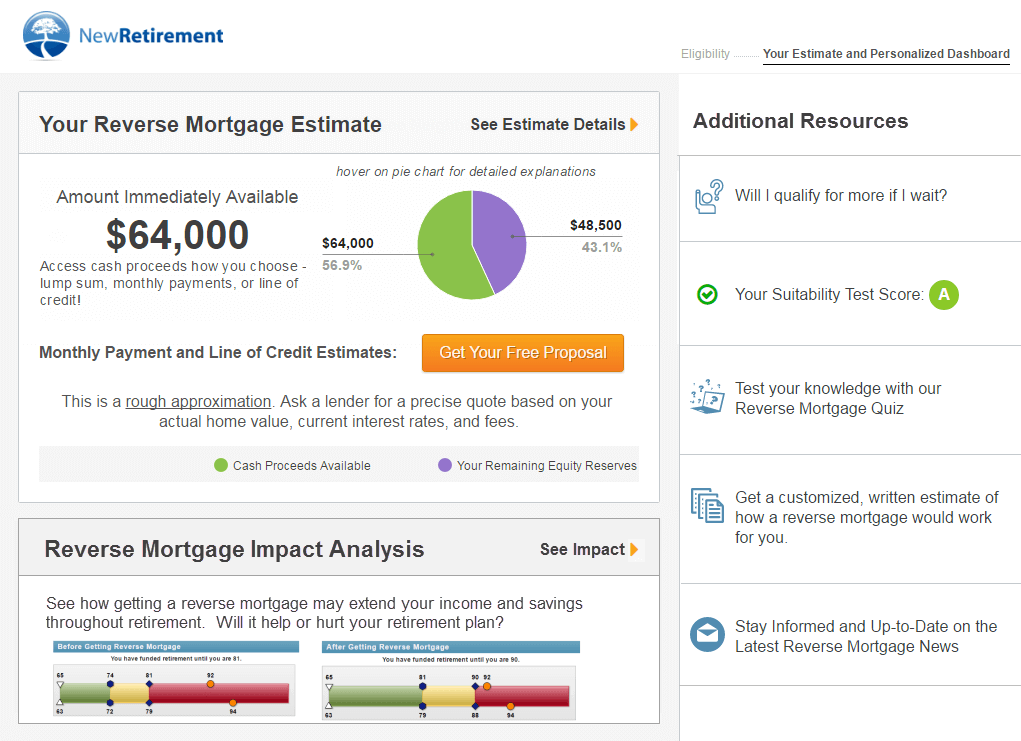
Most reverse mortgage calculators you find online are pretty rudimentary. They take your age, your home value, and a current interest rate, then spit out a number. That number is close, but it won't match what a lender will actually offer you on the day you close. The gap exists because real calculations involve several layers that most free tools skip over entirely.
The core calculation hinges on something called the Principal Limit Factor, or PLF. This is a percentage determined by the FHA and varies based on your age, the current interest rate, and the home value cap (which changes annually). You look up the PLF in the HECM tables, apply it to the lesser of your home's appraised value or the FHA lending limit, and subtract any existing mortgage balance. What's left is roughly what you can access. Simple in theory. Messy in practice.
Using a Reverse Mortgage Payment Calculator Correctly
Here is how I approach these calculations when I need a realistic figure rather than a rough estimate. Start by finding the current HECM lending limit for your area. For 2025, the baseline limit is $510,400, but high-cost areas go significantly higher. You need to know which bucket your property falls into before anything else. A lot of people skip this step and plug in their actual home value, which can overstate their potential proceeds by tens of thousands of dollars if they are in a standard cost area.
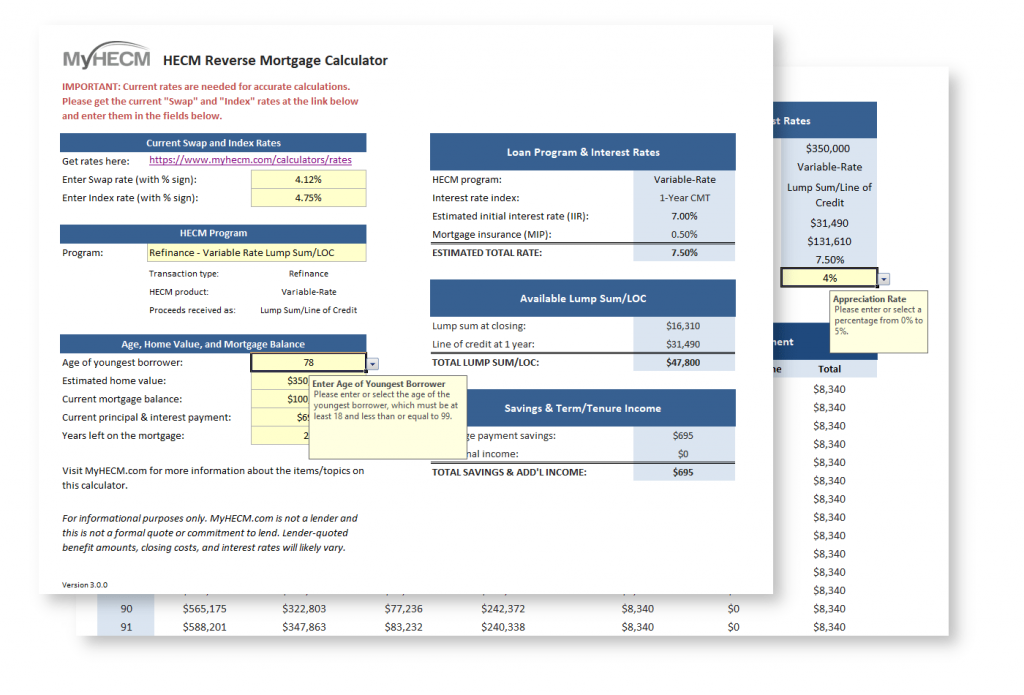
Next, pull the PLF from the latest FHA tables. These get updated quarterly. Using an old table will give you a number that is slightly off, and in reverse mortgage math, slightly off compounds fast because the loan balance grows over time. The PLF for a 70-year-old at a 6% interest rate will be materially different from the PLF for a 70-year-old at a 5% rate. Small rate shifts matter more than people expect.
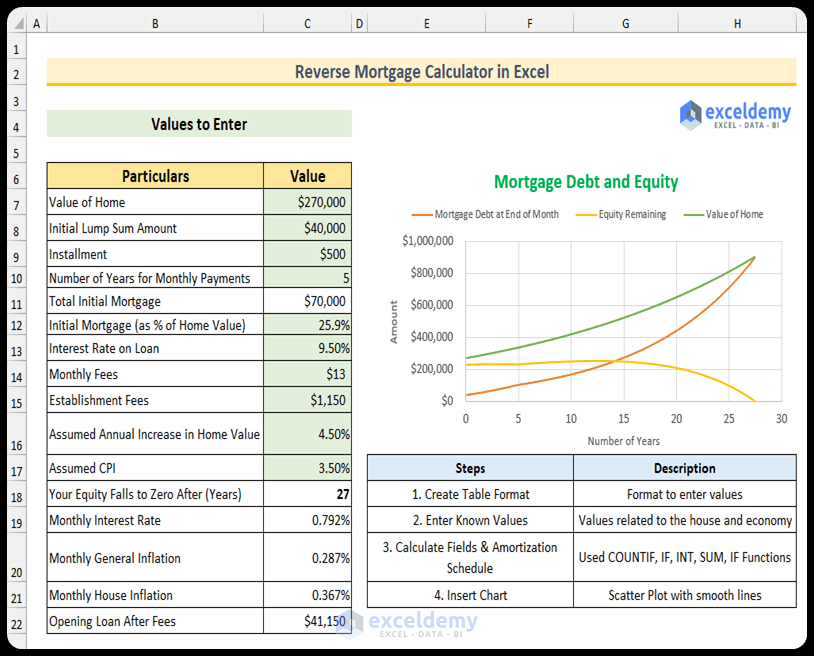
Then there is the closing cost calculation. Every reverse mortgage carries upfront mortgage insurance premiums — typically 2% of the home value for a standard HECM. There are origination fees, title work, appraisal costs, and servicing fees. Most basic calculators ignore these. When I built my own tool, I made it so you could input whether you wanted to finance the upfront MIP into the loan balance or pay it out of pocket. That one toggle changed the usable proceeds by about 8% in most cases.
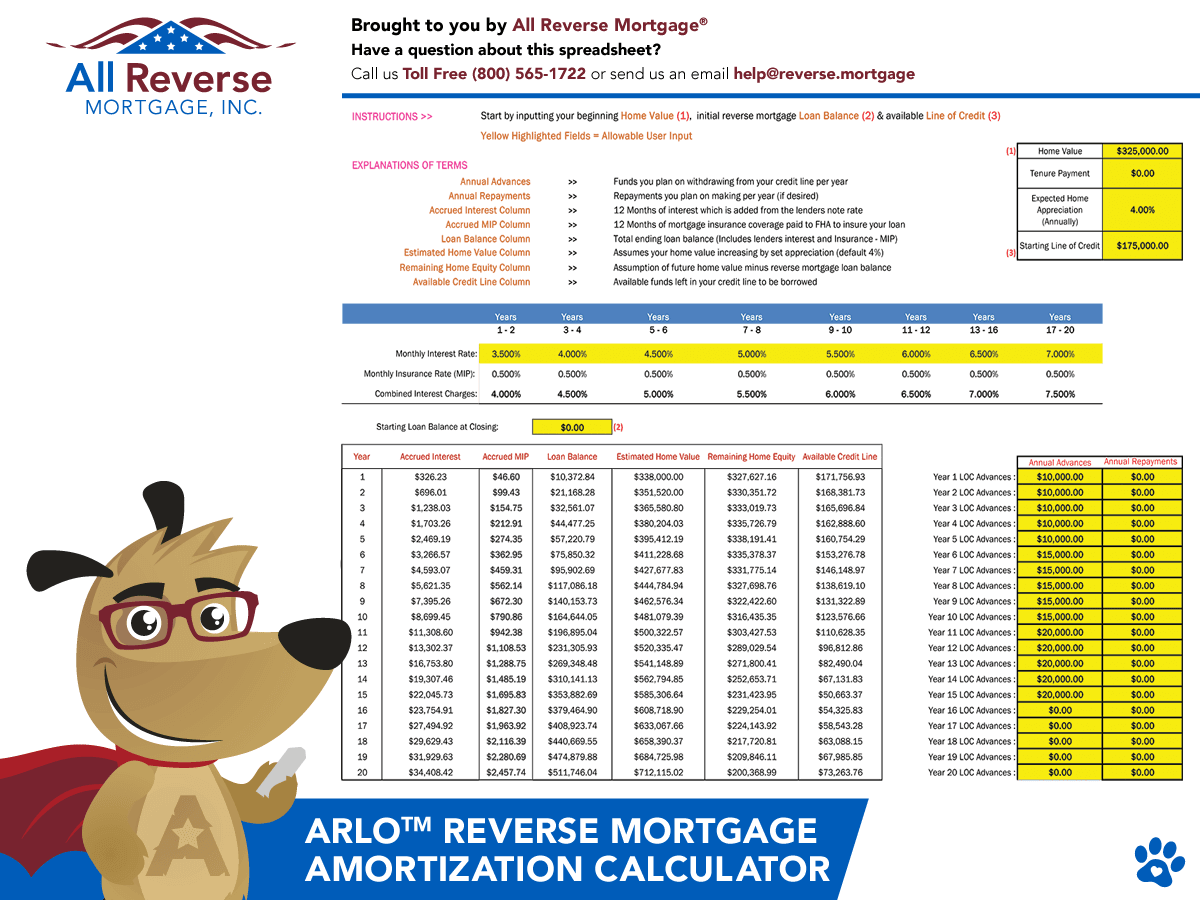
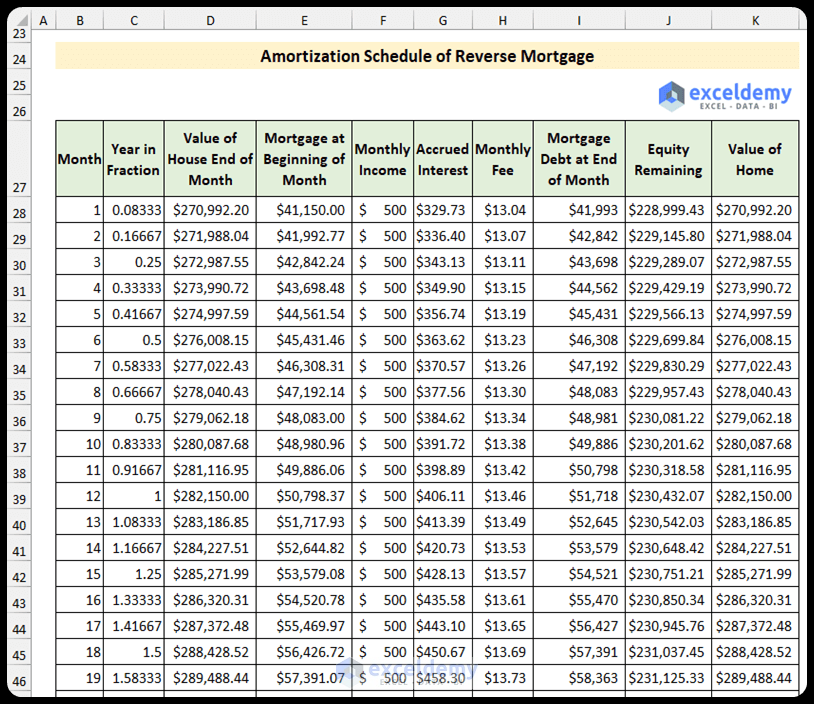
I ran into a specific issue last year with a client who was looking at a jumbo property valued at $920,000 in a high-cost county where the limit was $1,089,300. She assumed she could access nearly the full difference between her equity and the existing lien. The calculator I used showed her about $410,000 in proceeds. The actual offer from the lender came in at $362,000. The missing piece was the ongoing monthly mortgage insurance premium of 0.5% of the outstanding balance, which the upfront-only calculator never accounted for. Once I factored in the compounding effect of that annual MIP on the growing loan balance, the numbers aligned. I ended up building a spreadsheet that projected the balance forward at the assumed interest rate plus the ongoing MIP, so the figure reflected the true net line of credit available at closing.
The Pitfalls Most People Miss
The biggest mistake I see is treating the calculator output as a guaranteed amount. It is not. It is a projection based on today's rates and today's PLF. If rates move two points up before you lock, your proceeds drop. Not by much in some cases, but enough to matter on a tight budget.
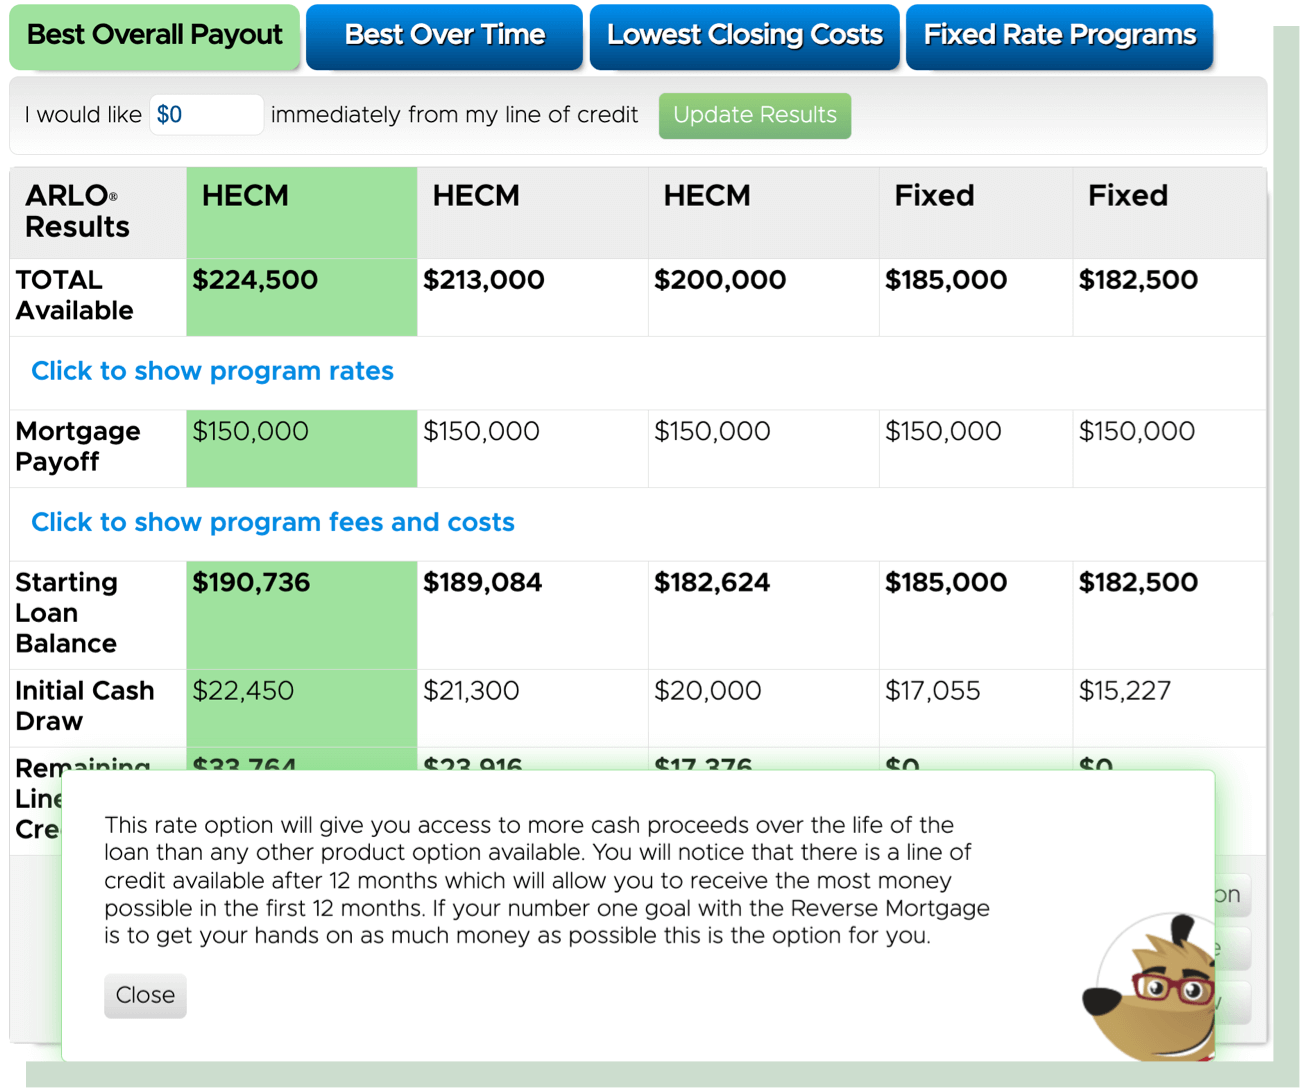
Another issue is the assumption that all available proceeds show up as cash. They don't. You can choose a lump sum, a term payout, a tenure payout, or a line of credit. A line of credit grows at the loan's interest rate — meaning the available balance increases every month even if you don't touch it. This is actually one of the features that makes reverse mortgages more useful than people assume, but most basic calculators don't model that growth at all. They just give you a single static number.
What to Look for in a Reliable Tool
A decent reverse mortgage payment calculator should let you adjust the interest rate, select your age, input any existing mortgage balance, and show you the difference between financing closing costs into the loan versus paying them separately. It should also display both the initial principal limit and the line of credit growth projection over time. If it only gives you one number with no breakdown, it is not giving you enough information to make a real decision.
You can find several working tools by searching for "Reverse Mortgage Payment Calculator." The ones produced by licensed reverse mortgage counselors tend to be more accurate than the ones on general mortgage aggregator sites, because the counselors are required to use the current FHA tables and disclose all costs. The aggregator sites often use simplified models that look clean but miss key variables.
When a Calculator Falls Short
There are scenarios where no calculator will help you much. If you have a non-traditional property like a manufactured home without a permanent foundation, a multi-unit property with a primary residence component, or a home with significant deferred maintenance, the appraisal value becomes unpredictable. The calculator assumes a clean appraisal. When it isn't clean, you need a real consultation with a counselor or lender who has seen similar properties.
Similarly, if you are under 62 or have a co-borrower who is significantly younger, the calculation changes dramatically. The younger co-borrower's age determines the PLF, not the older one. I have seen people get confused by this and run the numbers using only the older spouse's age, then show up at the appointment surprised by a much lower offer. Run the calculator with both ages entered correctly, or bring both ages to a counselor and ask them to walk through it with you.
The bottom line is that a reverse mortgage payment calculator is a starting point, not an answer. Use it to narrow the range, then verify the details with someone who works with HECM formulas daily. The numbers shift enough between tools and over time that relying on a single static calculation is risky.
Gallery Reverse Mortgage Payment Calculator
How to Create Reverse Mortgage Calculator in Excel (With Easy Steps)
Download a Free Excel Reverse Mortgage Calculator (2026)
Reverse Mortgage Amortization Calculator Excel at Lorelei Rios blog
Reverse Mortgage Calculator | How Does It Work and Examples
Reverse Mortgage Calculator | Instant Eligibility, Rates, APR & Costs