Understanding Rogue Trading Through Real Cases
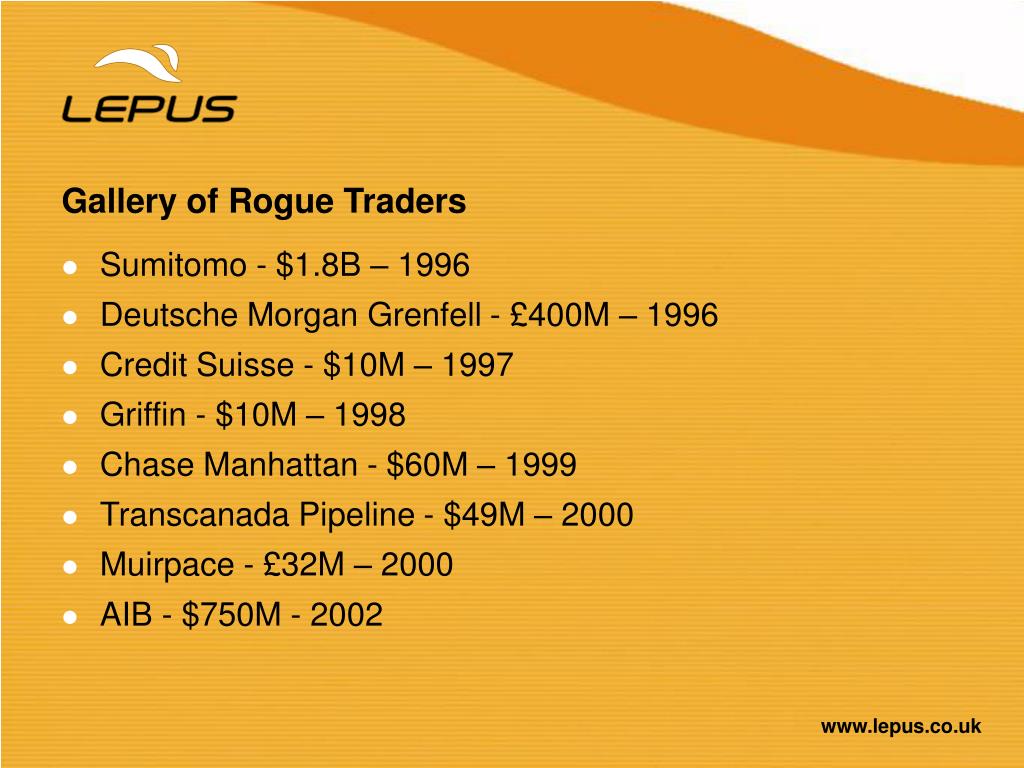
Rogue trading happens when someone on the buy side or sell side of a desk bypasses risk limits and makes unauthorized positions. It is not some mysterious financial art form. It is usually a combination of weak controls and someone willing to hide losses for a while. The Nick Leeson case at Barings Bank is the one everyone cites, but it is worth looking at again because the mechanics are still relevant. Leeson was simultaneously head of futures trading and settlement for Nikkei 222 options in Singapore. He kept the error trades in a separate account called 88888, which looked like rounding errors. When losses mounted, he rolled them into new positions hoping the market would reverse. It did not. Barings collapsed in 1995. The key takeaway is that no single person should hold both the front office and back office functions for the same book. I have seen firms still allow this in smaller subsidiaries. It does not end well. Jérôme Kerviel at Société Générale in 2008 is another clear example. He used stolen credentials and fake offsetting orders to hide massive directional positions in European index futures. The firm lost about €4.9 billion. What stands out here is how he exploited the fact that the risk system was checking gross exposure but his hedging offsets were entered as synthetic positions. The risk engine saw net zero. The workaround I recommend is to decouple trade entry from confirmation. Whoever enters the trade should not be the one who confirms or settles it. Cross-functional reconciliation on a T+1 basis catches most of this before it becomes a catastrophe.
Brian Hunter at Refco in 2003 is less discussed but instructive. He posted fake hedge positions in a separate account to mask a $2.3 billion loss in silver futures. The red flag should have been that the hedge portfolio returned almost zero volatility while the main book was wildly volatile. When auditors finally asked for source documents, the hedge positions could not be verified. Refco filed for bankruptcy. The lesson here is that unexplained correlation breakdowns between a trading book and its supposed hedges are a warning signal. I have run automated checks that flag when a hedging book diverges from the underlying risk metrics by more than two standard deviations. It catches anomalies within hours instead of months. Kweku Adoboli at UBS in 2011 traded €5 billion in unauthorized equity derivative positions and hid them using fabricated trades. The loss was approximately CHF 2 billion. UBS had new risk systems in place but Adoboli found gaps in the reconciliation process during a transition period. This shows that even expensive technology does not automatically prevent rogue trading. Process gaps during system migrations are where most modern cases emerge. When I audit trading desks, I look for four specific things. First, check whether any trader has access to both trade initiation and position confirmation. Second, verify that error accounts exist and reconcile them daily against the general ledger. Third, review exception reports for trades that bypass normal pricing routes. Fourth, compare individual trader P&L attribution against aggregate book P&L. Discrepancies between the two usually indicate something is being hidden somewhere.
One practical problem I encountered involved a mid-sized commodity trader who used a shadow Excel model to track off-book positions. The trades existed in the system but were offset by fabricated counterparty confirmations that never reached the back office. The discrepancy showed up only because the settlement team noticed payment amounts that did not match contract terms. The workaround was to require all counterparties to confirm trades through a centralized portal. Any trade without a third-party confirmation gets flagged automatically. This eliminated the shadow book in about three weeks. Another issue that trips people up is the assumption that rogue trading always involves intentional fraud. Sometimes it is just aggressive limit circumvention that crosses into unauthorized territory. A trader might believe they are protecting the firm from a losing position by moving it to an unmonitored account. The intent is different but the outcome is the same. Risk committees should treat both scenarios with equal seriousness. Technology can help but it has limits. Automated surveillance tools like TraceLink or Smile Trade Surveillance can flag unusual patterns, but they generate a lot of noise. The false positive rate is typically high unless you tune them to your specific book. I recommend starting with a small set of hard rules rather than a broad behavioral analysis. Rules like: no trades after 4 PM without supervisor approval, no error account entries over a certain threshold, and mandatory rotation of trader responsibilities every six months. These are simple and they work.
Get the Full Details

What You Can Actually Do About It
Build a culture where traders report mistakes quickly. The traders who get caught are usually the ones who tried to hide their errors. If the penalty for reporting a mistake is minimal and the penalty for hiding it is severe, people will come forward early. Early detection turns a potential billion-dollar problem into a five-figure adjustment. Rotate desk assignments regularly. Traders who stay in the same role for years develop blind spots and relationships that make oversight harder. Rotation disrupts those patterns. It also gives other people a chance to notice irregularities. Keep independent risk reporting separate from the trading floor. I have seen risk teams report through operations managers who sit next to the traders they are supposed to be monitoring. That arrangement does not work. Risk should report to someone who has no interaction with the trading desk.
Document every exception. When a trader bypasses a control, record it. Review the records quarterly. Patterns emerge that are impossible to see in real time. A trader who consistently gets exceptions approved during month-end close is worth investigating more closely than one who gets an exception once a year.