The Unromantic Truth About Keeping Score
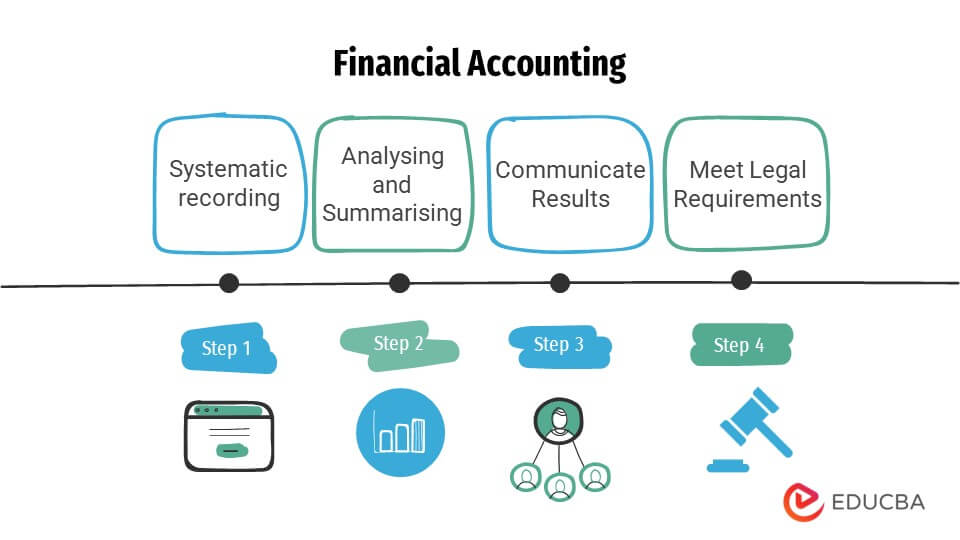
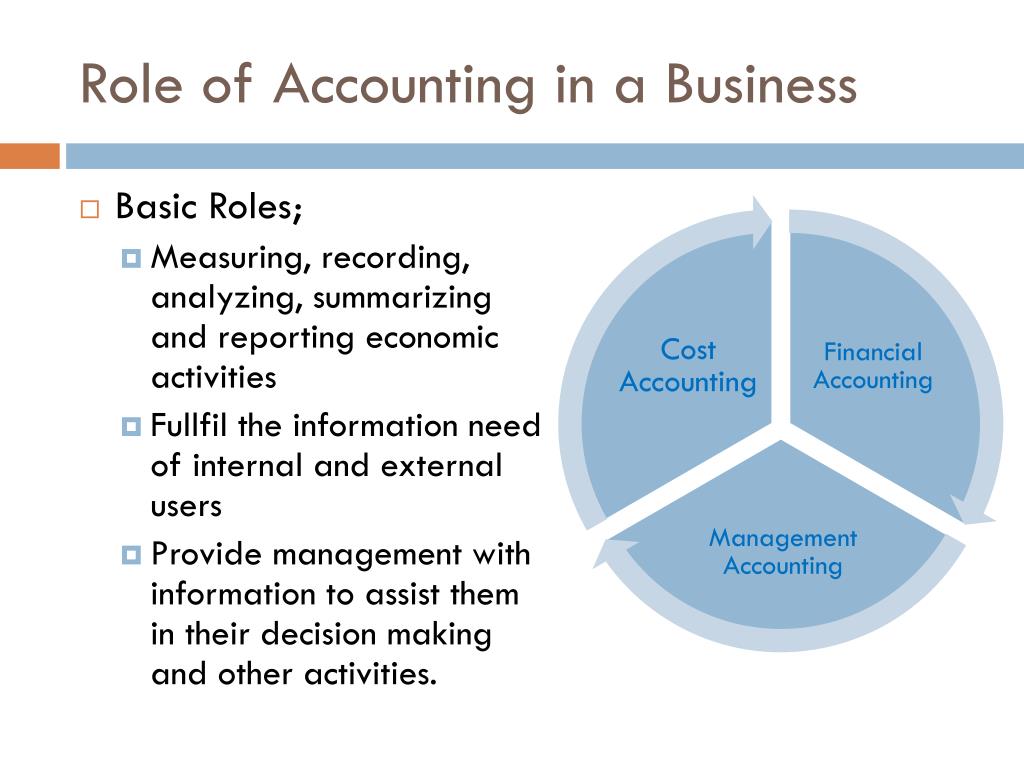
Most business owners treat financial accounting as the boring tax-adjacent chore that happens at the end of the year. That attitude is how companies find themselves two years into operation with no idea whether they're actually profitable or just really good at delaying bill payments. Financial accounting exists to create a standardized record of what a business has done with money over a specific period. The income statement, balance sheet, and cash flow statement aren't abstract exercises. They're the only things standing between you and the moment you realize your revenue is higher than your actual bank balance. I spent three years managing the books for a mid-size logistics company before I realized how much damage sloppy accounting does. We had a client who paid early, which made our cash flow look strong in Q2. Meanwhile, our actual receivables were rotting because a few customers were dragging invoices into Q3. The financial statements masked the problem entirely until we switched to accrual-based tracking and started aging our receivables weekly. That alone stopped us from making hiring decisions based on fake data. You learn pretty quickly that Role Of Financial Accounting In Business isn't about making numbers look good. It's about preventing the business from making decisions based on numbers that don't reflect reality.
Role Of Financial Accounting In Business: How It Actually Works Day to Day
At its core, financial accounting tracks every transaction a business processes and categorizes it so that anyone reading the financial statements can understand what happened. Revenue gets recorded when it's earned, not when cash hits the account. Expenses get recorded when they're incurred, not when the bill gets paid. This is the accrual method, and it's what separates a usable set of books from a ledger that looks decent in January but falls apart in March. The standard process runs like this. Transactions flow in from the operational side -- sales, purchases, payroll, vendor payments. Each one gets tagged with a general ledger account. The accounting software aggregates those entries into trial balance reports. From there, you produce the three core statements. Revenue and expenses flow to the income statement. Assets, liabilities, and equity sit on the balance sheet. Cash movements appear on the cash flow statement. The three should reconcile with each other, and when they don't, you've got a problem worth investigating before you present anything to anyone. Here's where people get tripped up. The most common mistake I see is treating the balance sheet as a static snapshot and the income statement as the real story. They're linked. Net income from the income statement flows into retained earnings on the balance sheet. If your balance sheet doesn't balance after you close a period, your income statement is wrong too. I once spent four hours tracking down a $3,200 discrepancy that turned out to be a single journal entry posted to the wrong account in April. The income statement looked fine. The balance sheet was off by exactly that amount. Two minutes of reconciliation would have caught it.
What Financial Accounting Enables That Bookkeeping Alone Doesn't
Bookkeeping records transactions. Financial accounting interprets them for external and internal decision-making. A bookkeeper might tell you that you spent $14,000 on software subscriptions this quarter. A financial accountant tells you that $14,000 represents 18 percent of your operating expenses, which is 6 percent above the industry median for companies your size, and that three of those subscriptions are duplicate tools you could eliminate without impacting operations. This distinction matters because it determines whether you're reacting to symptoms or addressing root causes. When investors or lenders look at your financial statements, they're not checking whether you remembered to record every transaction. They're assessing whether your business model is sustainable. Gross margin trends, debt-to-equity ratios, current ratios, and operating cash flow tell a story that raw transaction data never will. Getting that story right requires understanding what each line item represents and why it moved. One counter-intuitive thing about financial accounting that beginners miss: higher revenue on the income statement doesn't always mean better financial health. I had a situation where a client's revenue grew 40 percent year over year, which looked fantastic until I pulled the cash flow statement. Operating cash flow was negative because accounts receivable ballooned. Customers were taking 90-day payment terms that weren't in the original contract. Revenue was real in the accounting sense, but the business was bleeding cash. Without the cash flow statement, that problem stays hidden for quarters.
Get the Full Details
The Limitations Nobody Talks About
Financial accounting has real constraints. Historical cost depreciation means your balance sheet doesn't reflect what your equipment is actually worth today. Goodwill from acquisitions sits on the books at purchase price and gets tested for impairment annually, but that test is more art than science. Intangible assets like brand value and customer relationships rarely appear on the balance sheet unless you acquired them. These aren't flaws in the system. They're features of a framework designed for consistency and auditability, not for capturing every dimension of business value. Another limitation is timing. Financial statements are produced monthly, quarterly, or annually. By the time you read them, the information is already stale. Real-time operational dashboards fill that gap, but they're not financial statements and they don't carry the same credibility with lenders or regulators. The workaround is simple: treat financial accounting as the official record and operational metrics as the leading indicators. Don't confuse the two. I've seen business owners make expansion decisions based on dashboard numbers that hadn't been validated through the accounting close process. It almost never ends well. If your business is small enough that you don't need external financial statements -- no lenders, no investors, no regulatory requirements -- then formal financial accounting may be overkill for your situation. A clean cash-basis profit and loss statement with a monthly bank reconciliation will cover most of your needs at that scale. Formal accounting becomes necessary when you need to prove financial position to third parties or when your operational complexity makes it impossible to track profitability through gut feel alone.
Getting Started Without Overcomplicating It
Set up a chart of accounts that matches how you actually run the business, not how an accountant wishes you would. Group accounts logically. Revenue by product line or service type. Expenses by function -- cost of goods sold, selling expenses, general and administrative. Keep it detailed enough to be useful but not so granular that closing the books takes all week. Most small businesses I work with end up reconciling their statements within two to three days per month once the chart of accounts is properly structured. Implement a monthly close checklist. Bank reconciliation, accounts receivable aging review, accounts payable verification, expense accruals, depreciation entries, prepaid expense amortization, and a variance analysis comparing actual results to budget or prior period. Run through that same sequence every month without exception. The consistency builds discipline and makes anomalies stand out faster. When something looks wrong, you'll notice because you've seen it right a dozen times before. Automate what you can but verify manually at least once per cycle. Reconcile your bank statements yourself rather than trusting the software to do it perfectly. I've found that software-driven bank feeds miss categorized items about 5 to 8 percent of the time in my experience, usually involving fees, transfers, or merchant deposits that need manual attention. A thirty-minute manual review catches those before they compound into larger problems.
Invest in understanding the statements you produce. Knowing how to read an income statement is table stakes. Understanding why gross margin contracted even though revenue grew, or why operating expenses declined while net income stayed flat, is what turns financial accounting from a compliance task into a management tool. That shift is where the actual value lives.