Why People Look for a Role Of Financial Institutions Quick Check
Most students and junior analysts grab a quick reference sheet when they need to explain financial intermediation in under two minutes. The material gets dense fast. Banks, credit unions, insurance companies, pension funds, investment firms — each plays a different structural role in the economy, and the lines between them blur in practice even though textbooks keep them neatly separated. I've seen people stumble over these distinctions during earnings calls and board meetings because they memorized definitions instead of understanding the mechanics. Start by identifying the three core functions every financial institution performs: maturity transformation, liquidity provision, and risk pooling. Everything else branches from those. When you run through a quick check, ask whether the entity accepts deposits, issues policies, underwrites securities, or matches borrowers with lenders directly. The answers tell you its primary role. I remember sitting through a regulatory compliance training where a participant confidently told the instructor that credit unions were commercial banks with different branding. The trainer walked away frustrated. Credit unions operate on a cooperative model with member-owned governance and profit distribution through better rates, not shared equity. Mixing those up isn't just a terminology problem — it affects how you assess their capital requirements, regulatory oversight, and risk exposure. That mistake came from relying on surface-level descriptions instead of understanding institutional structure.
The practical workaround is straightforward. Before accepting any quick reference, verify that it distinguishes between depository institutions, contractual institutions, and investment intermediaries. A proper checklist will separate commercial banks and credit unions from life insurers and pension funds from mutual funds and hedge funds. If it lumps them together, discard it.
What Most Quick Checks Get Wrong About Financial Institutions
They oversimplify the shadow banking system. Many summaries treat the formal banking sector as the entire financial ecosystem. They don't. Money market funds, repurchase agreements, asset-backed commercial paper conduits, and private credit platforms perform bank-like functions without bank-like regulation. This matters because leverage and liquidity risk hide in those gaps. During the 2008 financial crisis, the fastest failures weren't traditional banks — they were Bear Stearns and Lehman, both investment banks, and the commercial paper market, which is technically shadow banking. Another frequent error is treating financial institutions as passive middlemen. They aren't. Every institution creates or destroys liquidity depending on its balance sheet decisions. When a bank tightens lending standards during uncertainty, it contracts money supply even if the central bank hasn't moved rates. When it expands, the opposite happens. The quick check you're using should reflect this active role, not present institutions as neutral conduits between savers and borrowers. I once reviewed a training document that claimed mutual funds and exchange-traded funds served identical economic purposes. They don't. Mutual funds price once per day at net asset value and can face redemption gates during stress. ETFs trade continuously on exchanges like stocks and use creation-redemption mechanisms with authorized participants. One structure creates intraday liquidity risk for the fund manager; the other transfers it to the market maker. Those differences matter enormously during market dislocations.
Get the Full Details

The Core Roles You Need to Know
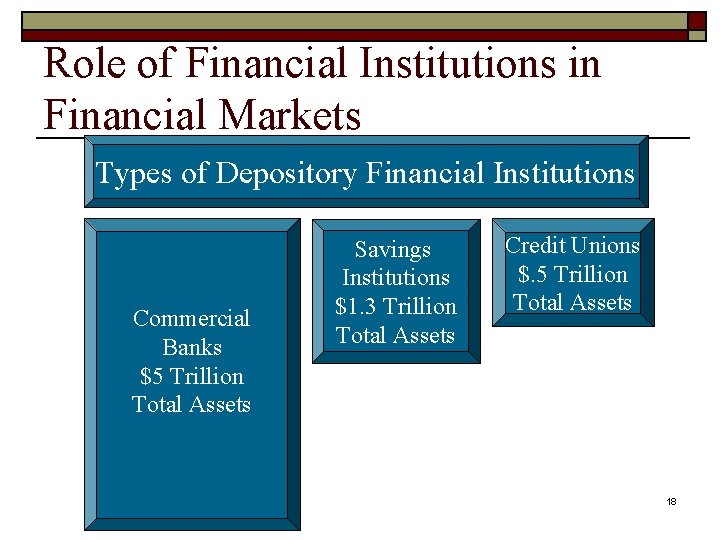
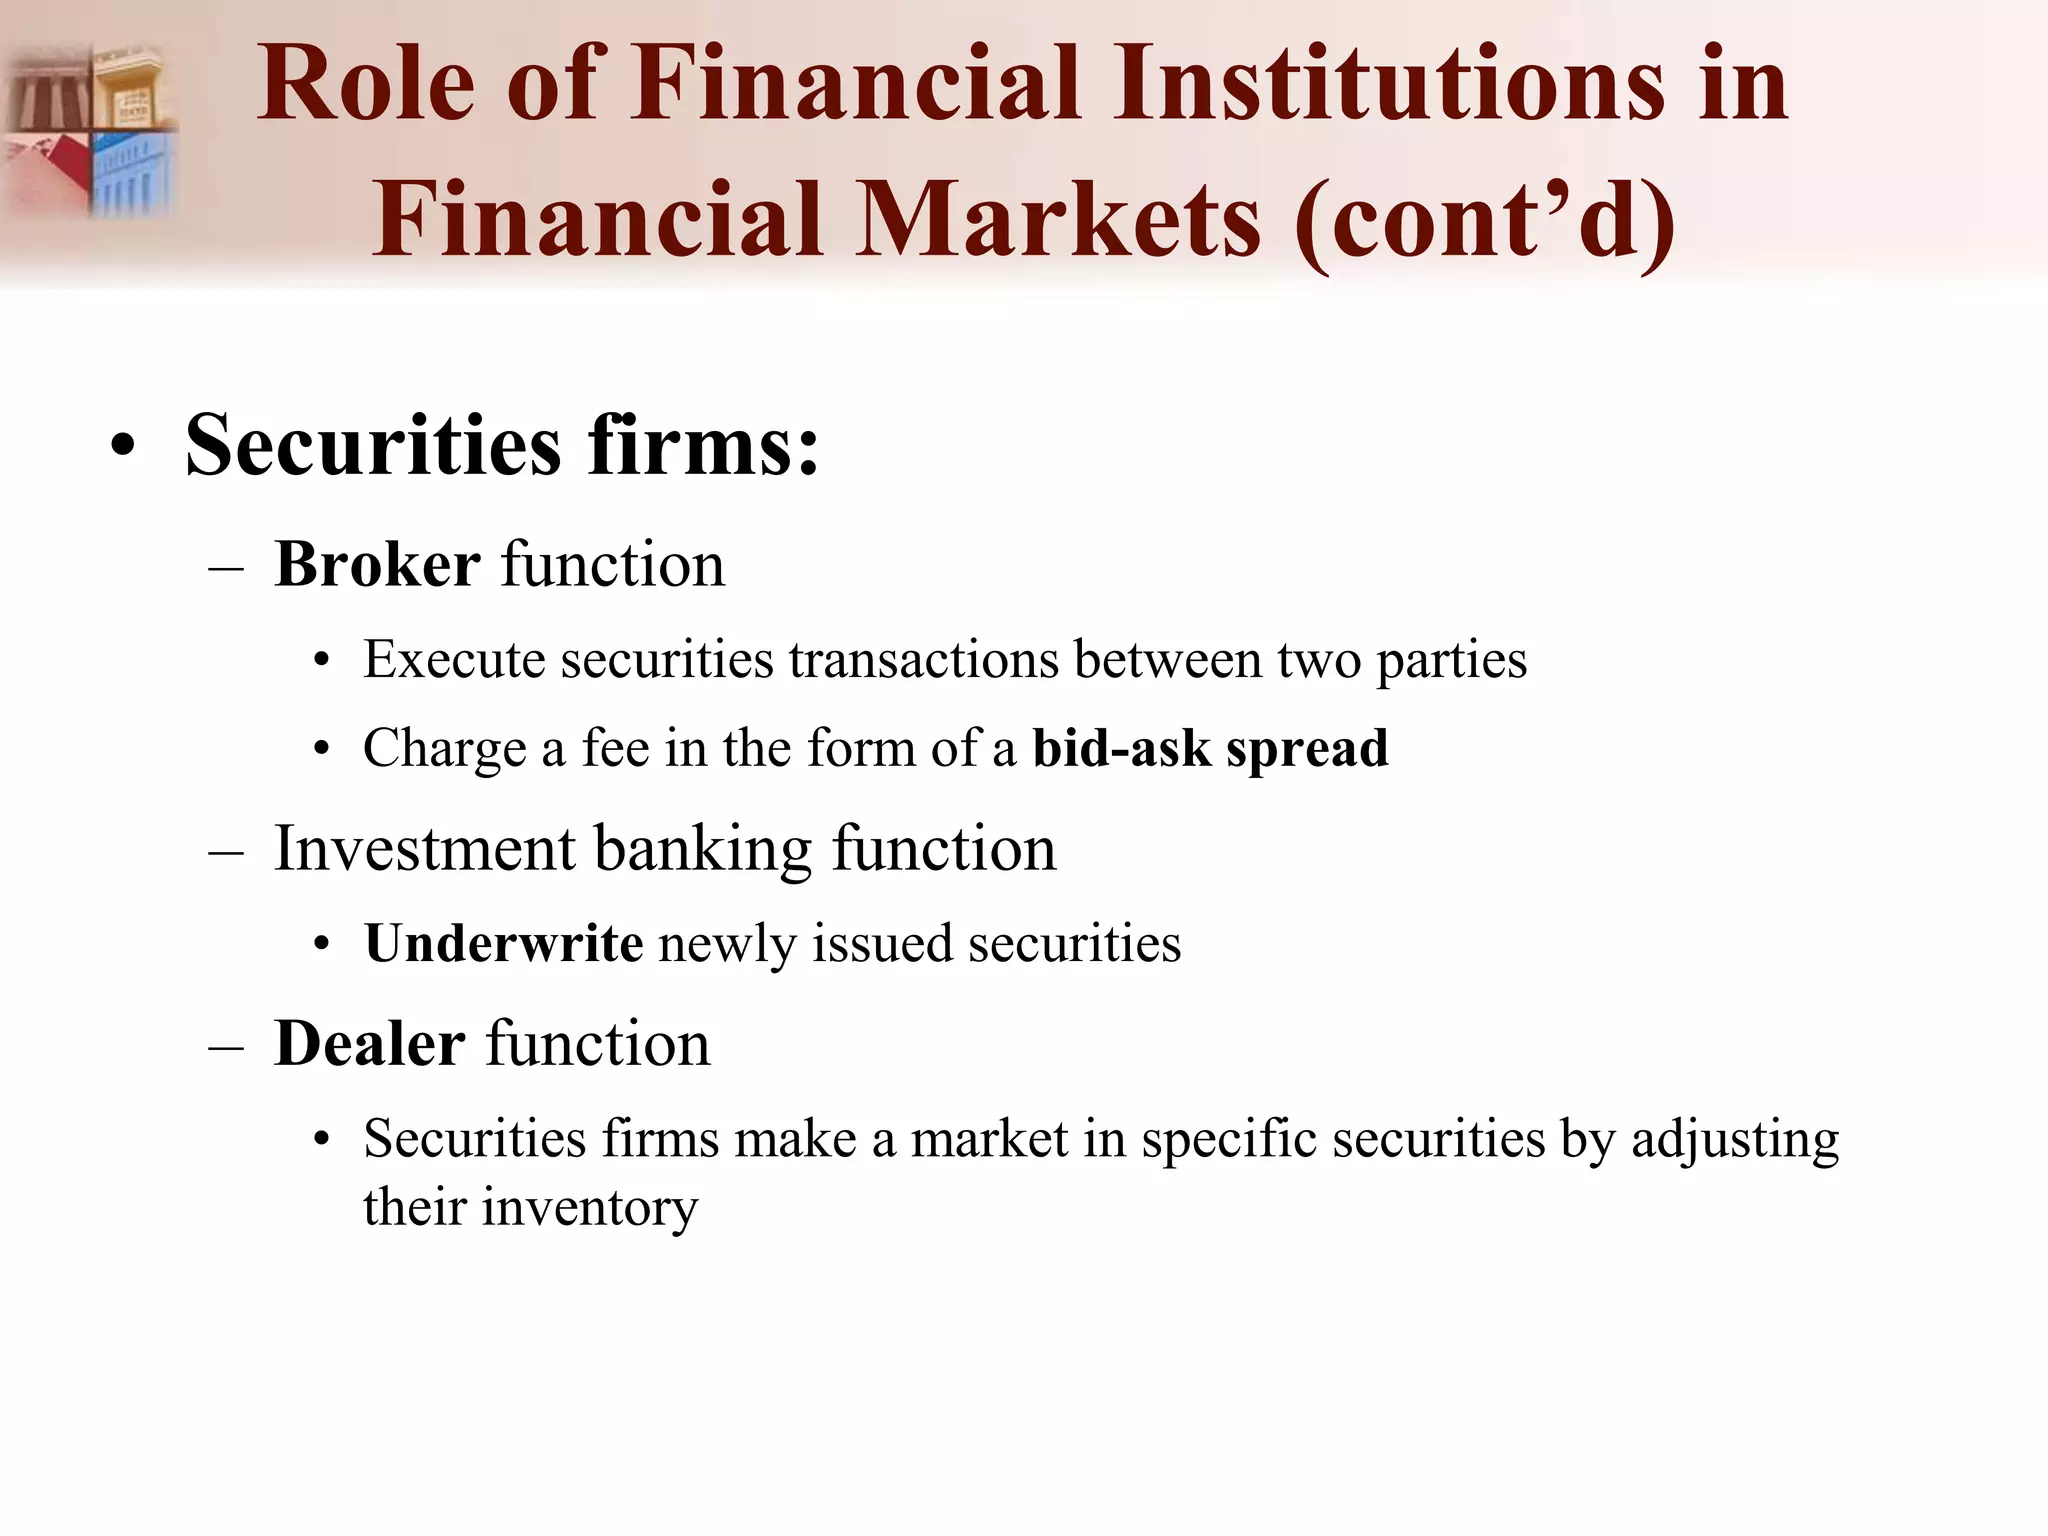
Depository institutions — commercial banks, savings banks, credit unions — accept deposits and make loans. Their primary economic function is maturity transformation. They borrow short and lend long. This creates a structural mismatch that requires deposit insurance, reserve requirements, and central bank backstops to remain stable. Contractual institutions — life insurance companies and pension funds — collect premiums or contributions and pay out future obligations. They specialize in long-duration liability matching. Their investment portfolios lean heavily toward fixed income because liabilities are predictable and distant. They're less liquid-focused and more yield-focused than depositories. Investment intermediaries — mutual funds, hedge funds, investment banks — facilitate capital formation and securities trading. They don't typically take deposits. Instead, they pool investor capital or provide underwriting and advisory services. Their risk profile is fundamentally different: mark-to-market volatility rather than credit risk concentration.
Multilateral development banks — the World Bank, regional development banks — serve policy objectives rather than profit maximization. They raise funds through bond markets and lend to governments or quasi-governmental projects in developing economies. Their role is developmental infrastructure financing, which commercial institutions avoid due to higher country risk.
Limitations of Any Quick Check Approach
A condensed reference will always flatten nuance. The real world doesn't fit neatly into categories. JPMorgan Chase does commercial banking, investment banking, asset management, and insurance. Industrial and Commercial Bank of China operates as a universal bank with subsidiaries in securities, trust, and leasing. Chinese banking groups and European financial conglomerates follow similar structures. Any quick check that presents these as pure examples of one category is misleading. Additionally, regulatory frameworks vary by jurisdiction. What counts as a bank in the United States under the Federal Reserve Act differs from what qualifies under the Basel III framework or the European Union's CRD IV. A quick check designed for one jurisdiction may not apply elsewhere. If you're working across borders, verify the regulatory classification separately. The most reliable approach is to use a quick check as a starting point, not an endpoint. Pull up the institution's regulatory filings, its balance sheet composition, and its primary revenue sources. Then map those against the three core functions. The details will override any summary sheet you read five minutes ago.

Where to Find a Role Of Financial Institutions Quick Check
Academic economics departments at major universities often maintain study guides and review sheets as part of their course materials. Those tend to be accurate but sometimes outdated. Government publications from the Federal Reserve, the Office of the Comptroller of the Currency, and the Financial Stability Board publish periodic overviews of the financial system that double as reliable quick references. Industry associations like the American Bankers Association and the Securities Industry and Financial Markets Association also distribute practitioner-oriented summaries. When you find one, check the publication date. Financial regulation changes frequently. Post-2008 reforms, the Dodd-Frank Act, Basel III phase-ins, and the 2023 regional banking stress all shifted how institutions are classified and regulated. A quick check published before 2020 may miss material updates to capital requirements and liquidity coverage ratios. The best quick checks are the ones that acknowledge complexity rather than papering over it. If a summary pretends the boundaries between institutions are clean, it's not useful for actual work.