How a Roll Over 401K Calculator Actually Works
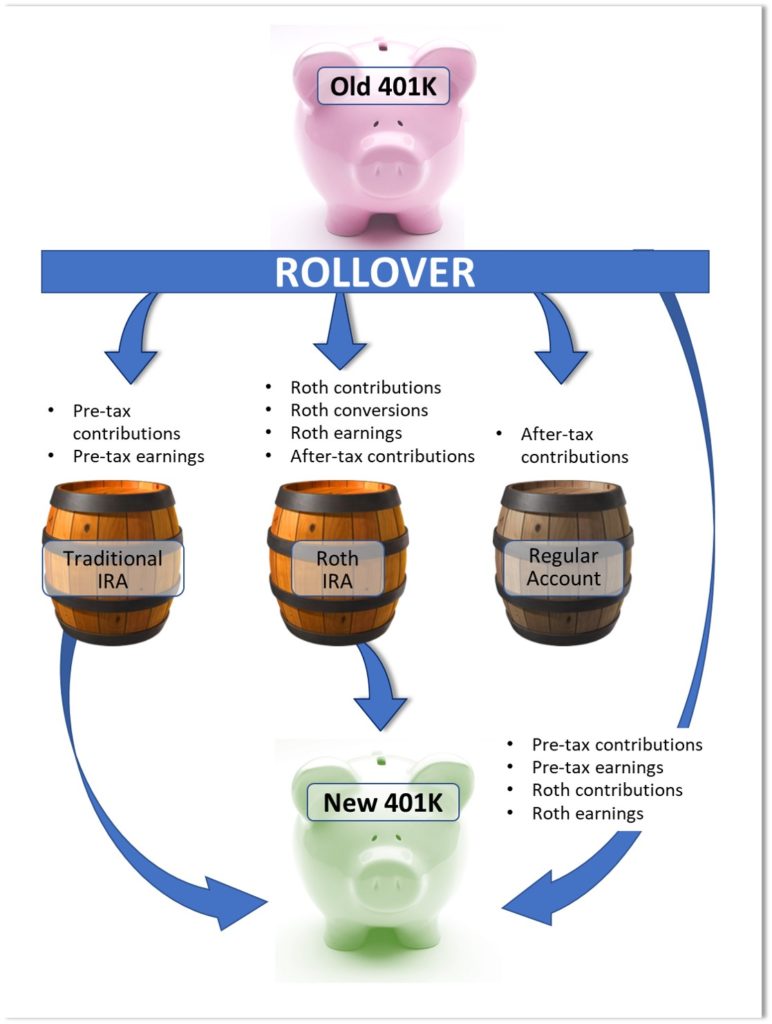
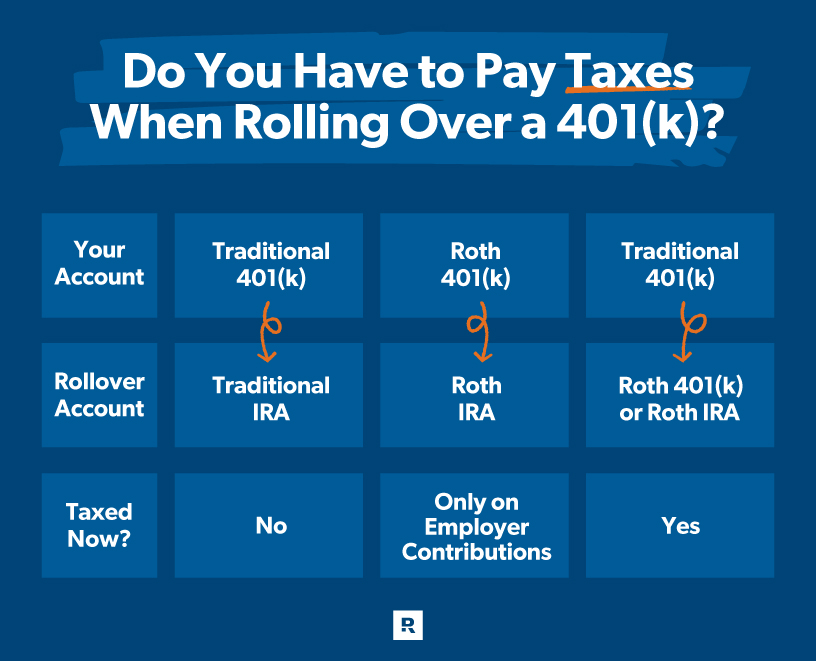
A Roll Over 401K Calculator is a simple tool that estimates what happens when you move money from an old employer's retirement plan into a new one or into an IRA. It takes your current balance, your contribution history, and the expected rate of return, then projects the new balance over time. Most people use these to figure out whether keeping their money in the old plan or moving it makes sense. The math isn't complicated. You have an ending balance, a monthly contribution amount, an annual percentage return, and a number of years. The calculator compounds those numbers forward and shows you the result. What most people don't realize is that the output depends heavily on which tax treatment you choose — traditional versus Roth — and whether the rollover is direct or indirect. A direct rollover to a Roth IRA creates a tax event. A direct rollover to a traditional 401K or traditional IRA does not.
Using a Roll Over 401K Calculator Correctly
Start by gathering your old plan's most recent statement. You need the total account balance as of a specific date, your employer match contributions separately from your own deferrals, and any loans you might have outstanding. If there's a loan, the calculator won't automatically factor it in. I learned this the hard way in 2019 when I rolled over a $142,000 401K that still had an $18,500 loan attached to it. The calculator spat out a clean projection, but the actual rollover amount was $123,500 because the plan custodian withheld the loan payoff first. I had to request a corrected distribution form and resubmit everything, which added three weeks to the process. Enter the balance as of your separation date, not your last pay stub date. Plans continue earning credits or taking fees until the actual distribution date. Those extra days matter more than people think when you're talking about six figures. Set the assumed rate of return honestly. Most calculators default to 7 percent, which is the historical S&P average, but your actual allocation probably isn't 100 percent equities. If you're mostly in a target date fund or conservative allocation, 5 to 6 percent is more realistic. Plugging in 7 percent when you really earn 5 percent will make you feel better about your retirement timeline while giving you false confidence.
Choose the right tax scenario. If you're doing a Roth conversion as part of the rollover, enter the taxable amount separately. The calculator should show you both the pre-tax and post-tax balances so you can see the difference. If you're staying in a traditional structure, just enter the total.
Get the Full Details
What These Calculators Miss
They do not account for plan-specific fees. Some employer plans charge administrative fees that get deducted directly from your balance. Others hide fees inside expense ratios that aren't visible on your quarterly statement. A calculator assumes a flat return, but your actual return gets eaten by 0.25 percent in administrative fees before it even starts compounding. They ignore state tax differences. If you move from California to Texas, you lose state retirement tax benefits. If you move the other direction, you gain them. The calculator treats every dollar the same regardless of where you live. They don't handle partial rollovers well. Say you have $200,000 in the old plan but want to leave $50,000 there to keep access to an employer loan feature or superior investment options. Most basic calculators assume a full roll. You have to manually adjust the inputs to reflect the split, which is easy to mess up.
Here is a counter-intuitive thing: rolling over to an IRA is not always better, even though financial advisors say it is. Large employer 401K plans sometimes offer institutional share classes with expense ratios below 0.05 percent. Many IRA providers charge 0.10 to 0.25 percent for the same underlying funds. On a $500,000 balance, that difference compounds to roughly $750 to $1,000 per year. Over twenty years, that is $15,000 to $20,000 you could keep instead of handing to the provider. Check your old plan's expense ratios before you click rollover. Another thing nobody mentions: creditor protection differs between plans. A 401K has federal ERISA protection that shields up to $1.5 million in bankruptcy. An IRA has the same protection, but the limit was raised recently and varies by state for non-bankruptcy creditors. If you run a business with liability exposure, keep more in the 401K structure longer.
When a Calculator Fails You
If you have after-tax non-Roth contributions in your old plan, the calculator will likely give you wrong numbers. These are rare, but they exist in older plan designs. Moving after-tax money into a traditional IRA triggers pro-rata rules that can create a huge unexpected tax bill the following year. You need to roll that portion directly into a Roth 401K if the new plan accepts it, or into a separate Roth IRA to avoid the pro-rata calculation. Standard calculators do not have a field for this, so you end up with projections that look fine until tax season. If your old plan has a consolidated asset fee structure, the calculator cannot model it. Some plans charge a flat dollar amount per participant per year, sometimes $100 to $300, that gets deducted from everyone's balance equally. On a small balance, that fee represents a much larger percentage than on a large balance. Your actual return gets dragged down more than the calculator predicts. For complex situations, the online calculator gives you a rough estimate at best. You should talk to a CPA or fee-only fiduciary advisor who can run the numbers with your actual plan documents in hand. The Rollover 401K Calculator is useful for initial planning, but it is not a substitute for professional advice when your situation involves after-tax basis, loans, or state tax complications.
The tool works best when you treat it as a starting point, not an answer. Enter conservative numbers. Compare multiple scenarios. Then verify the math against your actual plan statement before you submit any paperwork.