Using Your 401K to Fund a Business: The Rollover Route
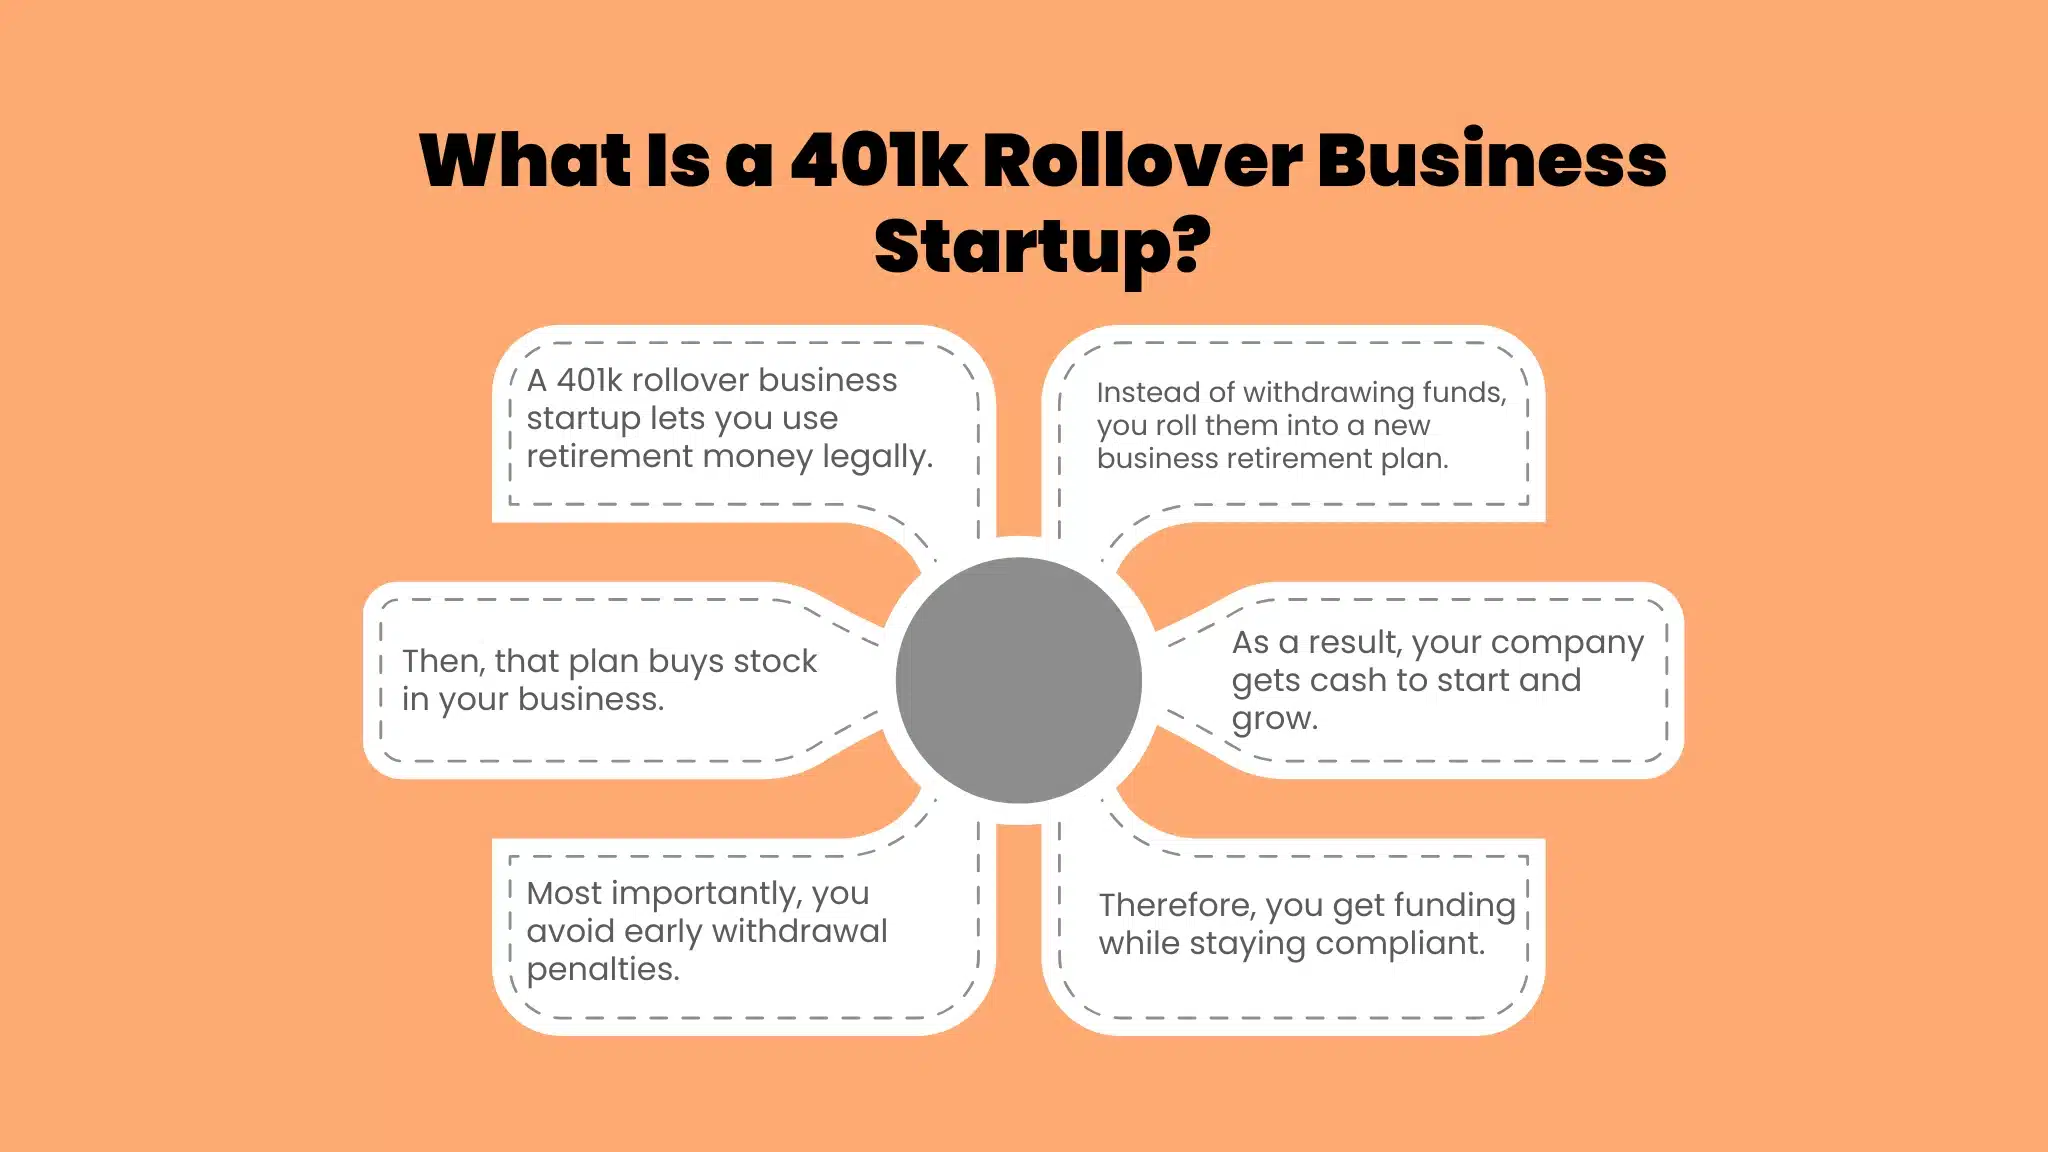
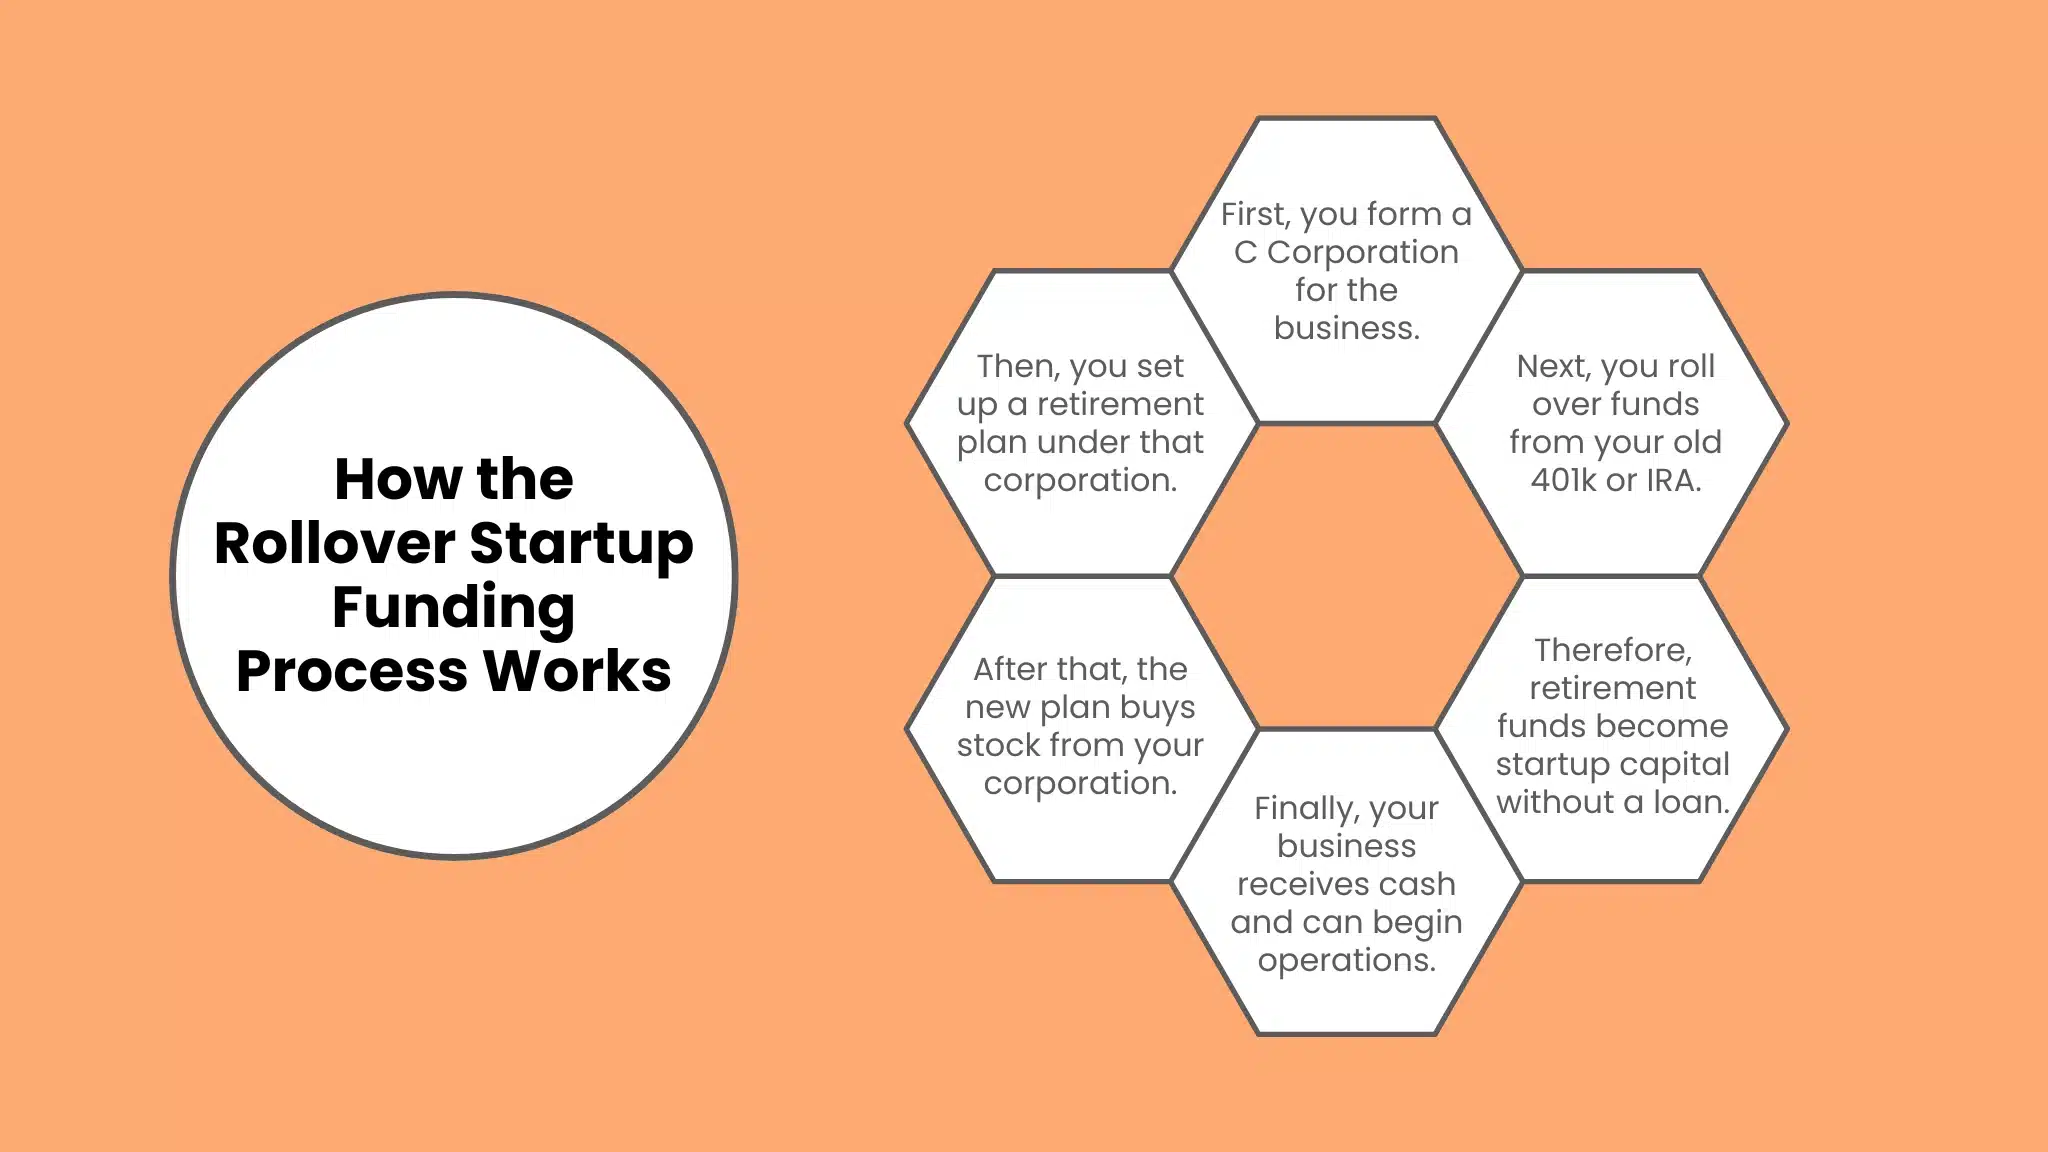
I have seen enough people try to use retirement money for startup capital to know where this goes wrong. The process itself is straightforward, but the tax consequences and timing issues can catch you off guard if you do not plan the mechanics correctly. The vehicle you are looking for is called a rollover, specifically a direct rollover from your 401K into an IRA, then using that IRA to back your business through a Rollover for Business Startups structure. I prefer the term ROBS because it makes the whole operation easier to discuss without having to explain the technical name every time. Here is how it works in practice. You close out your 401K by rolling it into a self-directed IRA. That IRA then lends money to your LLC or corporation. The business pays the IRA back with interest over time. You are essentially borrowing from yourself, with the advantage being that the money never hits your personal taxable income.
I ran into a specific problem early on when I first tried this. The plan administrator at my previous employer made the direct transfer process take six weeks. They kept asking for additional documentation about the receiving institution, even though I had already provided everything twice. The workaround was having my new IRA custodian call the 401K provider directly. A live conversation between financial institutions cut the delay down from three weeks to about four days. Do not try to navigate this through email threads. The IRS does not actually prohibit this. Section 401K plans are governed by ERISA, and the agency has a notice from 2014 that acknowledges the structure. Your plan document controls whether you are even allowed to do it. Some plans prohibit early distributions entirely. Others allow in-service distributions after age 59 and a half. Check your summary plan description before you spend any money on setup costs.
The Mechanics
You need four things in place before anything moves. First, a self-directed IRA custodian who understands ROBS transactions. Not every SDIRA provider will touch this. Some will take your money and do nothing. Others will take a fee and ghost you when paperwork gets complicated. I have worked with three providers over the years and learned to verify their transaction history before handing over any funds. Second, your business entity. An LLC is the standard choice. It gives you liability protection without the corporate formalities that an S-corp requires. You can operate on less paperwork and still borrow from the IRA. The loan goes from the IRA to the LLC, not from the IRA to you personally. That distinction matters for tax purposes. Third, a promissory note. This is the legal document that makes the loan real. The IRS looks for substance, not just paperwork. The note needs a reasonable interest rate, a repayment schedule, and collateral. I usually recommend using the business assets as security. That gives the IRA some recourse if things go sideways.
Fourth, proper account titles and records. The IRA needs to be clearly identified as the lender. The LLC needs to be clearly identified as the borrower. Mixing these up on a bank statement or invoice can trigger a prohibited transaction.
Get the Full Details
Costs and Timeline
Expect to spend between two and four thousand dollars to set this up. The SDIRA custodian charges an annual fee of five hundred to twelve hundred dollars depending on the provider. A lawyer or service company that drafts the promissory note and supporting documents will charge another thousand to two thousand. Setup typically takes two to six weeks if everything goes smoothly. The actual rollover from 401K to IRA takes three to eight weeks. Plan administrators vary wildly in their efficiency. Some process requests in ten business days. Others take two months and still find reasons to delay. I have seen people sit on hold for three hours trying to get a status update.
Common Pitfalls
Self-dealing is the biggest risk. You cannot use the IRA funds for personal expenses. You cannot buy property that you personally use. You cannot pay yourself a salary from IRA money. The IRS treats these as distributions, which means taxes and penalties hit immediately. Another issue is the valuation requirement. If your business buys real estate, the IRA needs an appraisal. Skip that step and you are exposing yourself to a prohibited transaction claim. I learned this the hard way when a friend skipped the appraisal to save three hundred dollars and ended up owing forty thousand in back taxes and penalties three years later. The market timing risk is real too. You are tying up retirement savings in a business that may not succeed. If the business fails, you lose both the startup capital and the retirement funds. I have seen this play out more times than I would like to count. The emotional toll of watching retirement money vanish while you are also unemployed is harder to describe than it is to experience.
Tax Implications
A proper ROBS transaction does not create immediate taxable income. The money stays in the retirement account ecosystem. Interest payments from the LLC back to the IRA are tax-deferred. When you eventually take distributions from the IRA, those are taxed as ordinary income. If you have a traditional 401K, all future growth and withdrawals are taxed at your ordinary income rate. A Roth 401K or Roth conversion changes the math. You pay taxes now and withdrawals are tax-free later. Many business owners prefer Roth for this reason, since successful businesses tend to grow significantly. The pass-through taxation benefit only applies to the business structure. An LLC taxed as a sole proprietorship passes income through to your personal return. An S-corp or C-corp files its own return. This decision should be made with a CPA, not based on what sounds good.
When This Does Not Work
If your 401K balance is under twenty-five thousand dollars, the setup costs eat into the advantage quickly. You are paying two to four thousand dollars to access money that small. The math does not work in your favor. If you already have other sources of startup capital, using retirement money adds unnecessary risk. A personal loan from a credit union at seven percent interest beats losing your retirement security. If your plan prohibits early distributions, you are stuck. Some employer plans lock you out until termination, age 59 and a half, or death. Check your summary plan description. Do not assume you can proceed just because you have a balance.
Alternatives to Consider
Small Business Administration loans offer better terms if you qualify. The SBA 7(a) program provides up to five million dollars at competitive rates. The application process takes longer than a ROBS setup, but the cost of capital is significantly lower. Crowdfunding platforms like Kickstarter or Indiegogo let you validate your business concept while raising money. You get market feedback before committing any personal funds. Angel investors and venture capitalists provide capital without the retirement risk. The trade-off is giving up equity and control. This may or may not be acceptable depending on your goals.
I have seen successful business owners use all of these approaches. None of them are wrong. Using your 401K is one tool in the toolbox, not the only tool. Make sure you understand the trade-offs before you commit retirement savings to a business venture.
Using Your 401K to Fund a Business: The Rollover Route
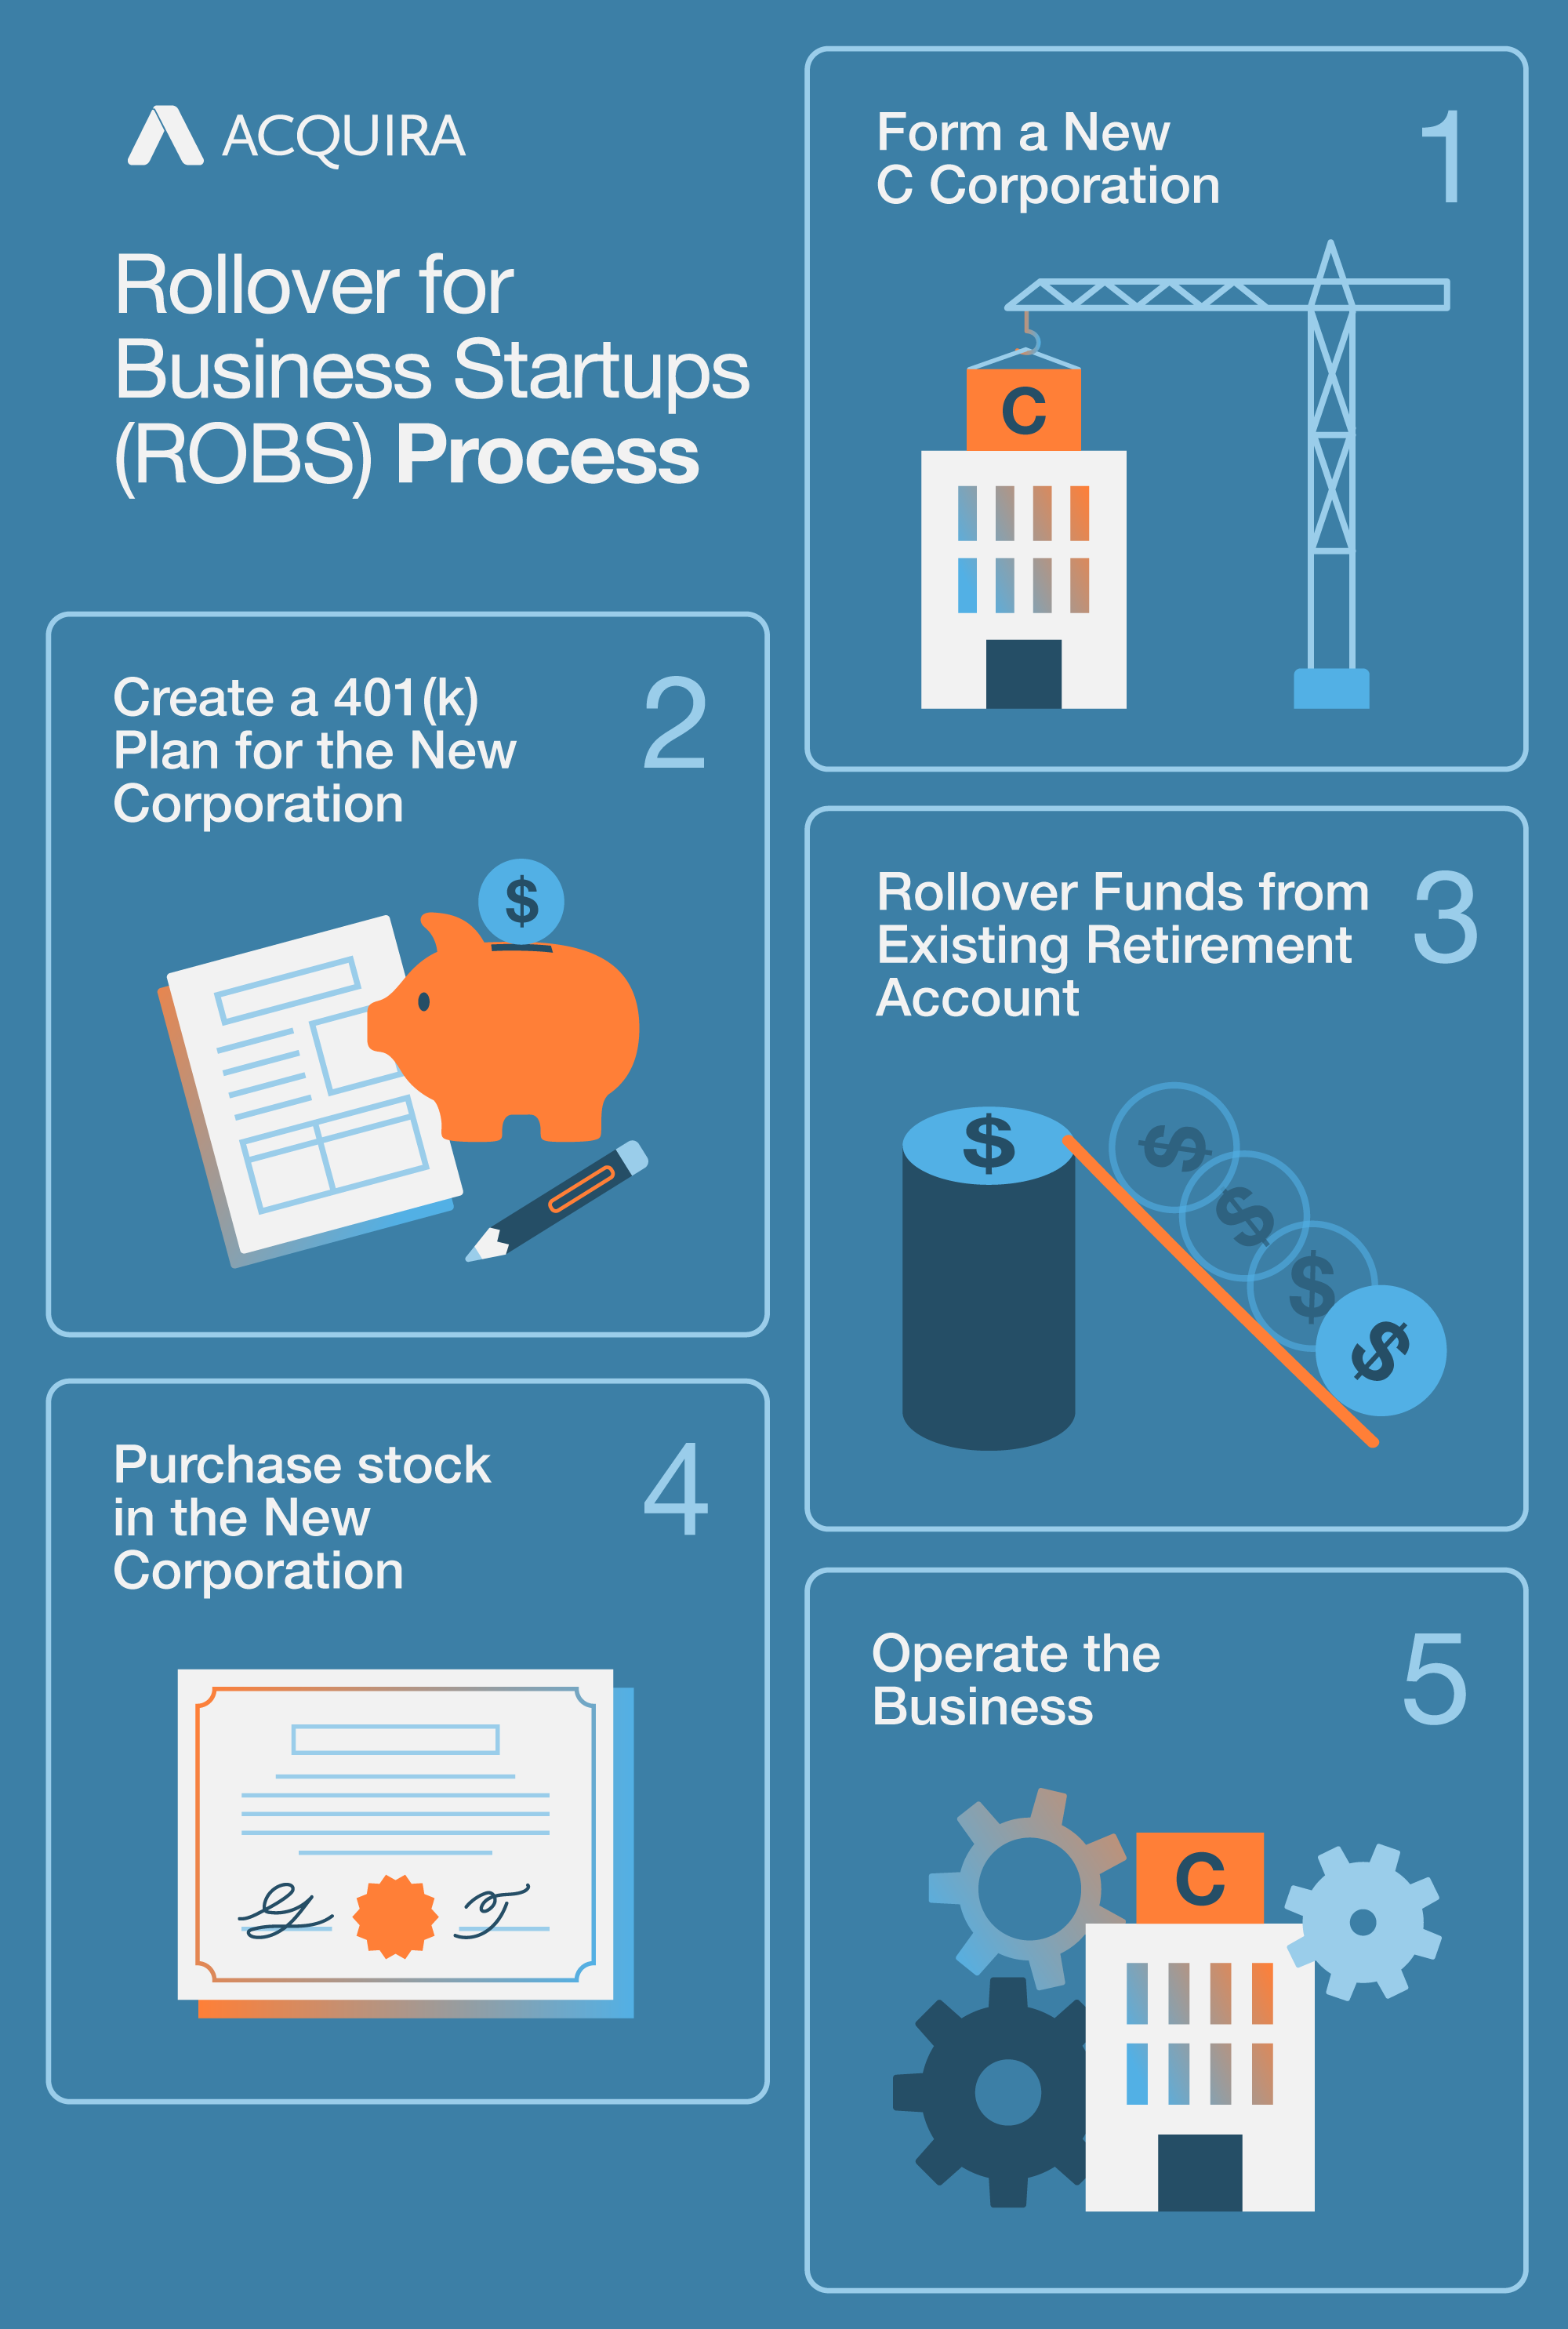
I have seen enough people try to use retirement money for startup capital to know where this goes wrong. The process itself is straightforward, but the tax consequences and timing issues can catch you off guard if you do not plan the mechanics correctly. The vehicle you are looking for is called a rollover, specifically a direct rollover from your 401K into an IRA, then using that IRA to back your business through a Rollover for Business Startups structure. I prefer the term ROBS because it makes the whole operation easier to discuss without having to explain the technical name every time. Here is how it works in practice. You close out your 401K by rolling it into a self-directed IRA. That IRA then lends money to your LLC or corporation. The business pays the IRA back with interest over time. You are essentially borrowing from yourself, with the advantage being that the money never hits your personal taxable income.
I ran into a specific problem early on when I first tried this. The plan administrator at my previous employer made the direct transfer process take six weeks. They kept asking for additional documentation about the receiving institution, even though I had already provided everything twice. The workaround was having my new IRA custodian call the 401K provider directly. A live conversation between financial institutions cut the delay down from three weeks to about four days. Do not try to navigate this through email threads. The IRS does not actually prohibit this. Section 401K plans are governed by ERISA, and the agency has a notice from 2014 that acknowledges the structure. Your plan document controls whether you are even allowed to do it. Some plans prohibit early distributions entirely. Others allow in-service distributions after age 59 and a half. Check your summary plan description before you spend any money on setup costs.

The Mechanics
You need four things in place before anything moves. First, a self-directed IRA custodian who understands ROBS transactions. Not every SDIRA provider will touch this. Some will take your money and do nothing. Others will take a fee and ghost you when paperwork gets complicated. I have worked with three providers over the years and learned to verify their transaction history before handing over any funds. Second, your business entity. An LLC is the standard choice. It gives you liability protection without the corporate formalities that an S-corp requires. You can operate on less paperwork and still borrow from the IRA. The loan goes from the IRA to the LLC, not from the IRA to you personally. That distinction matters for tax purposes. Third, a promissory note. This is the legal document that makes the loan real. The IRS looks for substance, not just paperwork. The note needs a reasonable interest rate, a repayment schedule, and collateral. I usually recommend using the business assets as security. That gives the IRA some recourse if things go sideways.
Fourth, proper account titles and records. The IRA needs to be clearly identified as the lender. The LLC needs to be clearly identified as the borrower. Mixing these up on a bank statement or invoice can trigger a prohibited transaction.
Costs and Timeline
Expect to spend between two and four thousand dollars to set this up. The SDIRA custodian charges an annual fee of five hundred to twelve hundred dollars depending on the provider. A lawyer or service company that drafts the promissory note and supporting documents will charge another thousand to two thousand. Setup typically takes two to six weeks if everything goes smoothly. The actual rollover from 401K to IRA takes three to eight weeks. Plan administrators vary wildly in their efficiency. Some process requests in ten business days. Others take two months and still find reasons to delay. I have seen people sit on hold for three hours trying to get a status update.
Common Pitfalls
Self-dealing is the biggest risk. You cannot use the IRA funds for personal expenses. You cannot buy property that you personally use. You cannot pay yourself a salary from IRA money. The IRS treats these as distributions, which means taxes and penalties hit immediately. Another issue is the valuation requirement. If your business buys real estate, the IRA needs an appraisal. Skip that step and you are exposing yourself to a prohibited transaction claim. I learned this the hard way when a friend skipped the appraisal to save three hundred dollars and ended up owing forty thousand in back taxes and penalties three years later. The market timing risk is real too. You are tying up retirement savings in a business that may not succeed. If the business fails, you lose both the startup capital and the retirement funds. I have seen this play out more times than I would like to count. The emotional toll of watching retirement money vanish while you are also unemployed is harder to describe than it is to experience.
Tax Implications
A proper ROBS transaction does not create immediate taxable income. The money stays in the retirement account ecosystem. Interest payments from the LLC back to the IRA are tax-deferred. When you eventually take distributions from the IRA, those are taxed as ordinary income. If you have a traditional 401K, all future growth and withdrawals are taxed at your ordinary income rate. A Roth 401K or Roth conversion changes the math. You pay taxes now and withdrawals are tax-free later. Many business owners prefer Roth for this reason, since successful businesses tend to grow significantly. The pass-through taxation benefit only applies to the business structure. An LLC taxed as a sole proprietorship passes income through to your personal return. An S-corp or C-corp files its own return. This decision should be made with a CPA, not based on what sounds good.
When This Does Not Work
If your 401K balance is under twenty-five thousand dollars, the setup costs eat into the advantage quickly. You are paying two to four thousand dollars to access money that small. The math does not work in your favor. If you already have other sources of startup capital, using retirement money adds unnecessary risk. A personal loan from a credit union at seven percent interest beats losing your retirement security. If your plan prohibits early distributions, you are stuck. Some employer plans lock you out until termination, age 59 and a half, or death. Check your summary plan description. Do not assume you can proceed just because you have a balance.
Alternatives to Consider
Small Business Administration loans offer better terms if you qualify. The SBA 7(a) program provides up to five million dollars at competitive rates. The application process takes longer than a ROBS setup, but the cost of capital is significantly lower. Crowdfunding platforms like Kickstarter or Indiegogo let you validate your business concept while raising money. You get market feedback before committing any personal funds. Angel investors and venture capitalists provide capital without the retirement risk. The trade-off is giving up equity and control. This may or may not be acceptable depending on your goals.
I have seen successful business owners use all of these approaches. None of them are wrong. Using your 401K is one tool in the toolbox, not the only tool. Make sure you understand the trade-offs before you commit retirement savings to a business venture.

