What Happened with Roman Financial Group
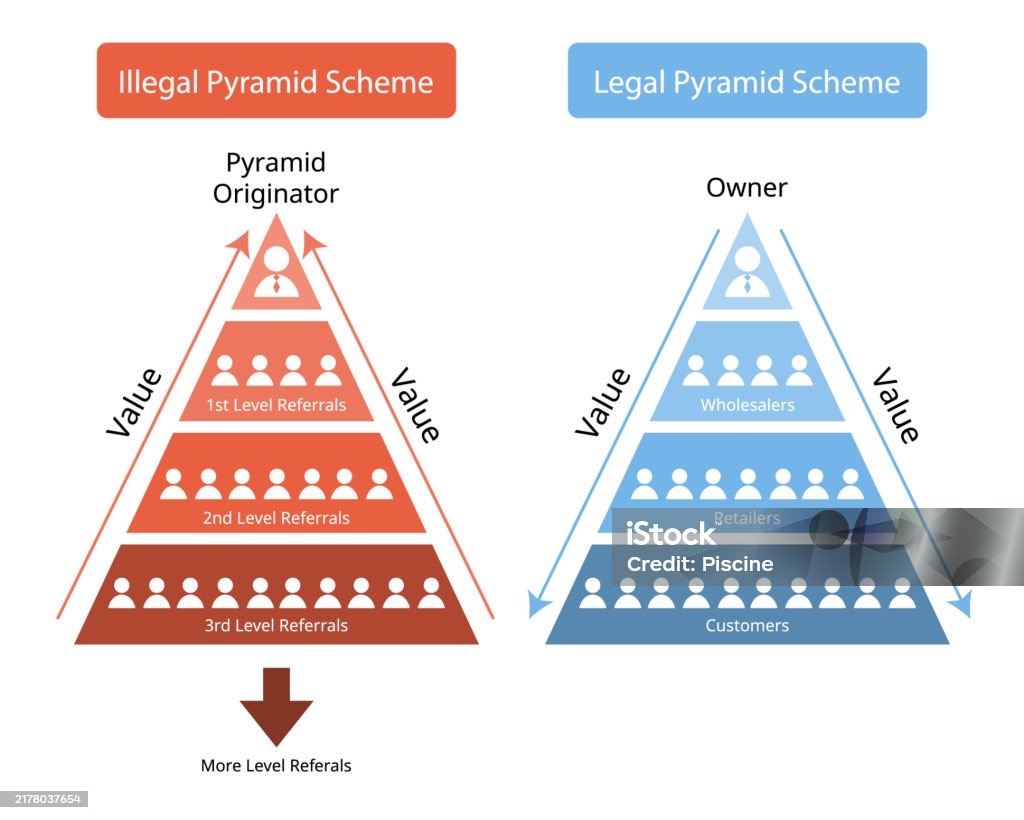
Roman Financial Group was a direct selling company based in Atlanta that started operating around 2016. They sold wellness products, supplements, and personal care items under various brands. The company grew quickly through a referral-heavy compensation plan, and within a few years regulators and financial observers started calling it something else. By 2023, the FTC had filed charges, and by 2024 there were frozen assets and a court-appointed receiver. The company's website went offline, social media accounts stopped updating, and most active distributors found their commissions disappeared overnight. When people use the phrase Roman Financial Group Pyramid Scheme, they are generally describing the structural reality that the business model relied more on new member recruitment than on actual retail product sales. That distinction matters legally and financially. A legitimate direct selling company generates the majority of its revenue from sales to customers who are not participants. When the math flips and recruitment becomes the primary income engine, you cross into pyramid territory. That is exactly what happened with Roman Financial Group. The company operated under what looked like a standard multi-level marketing structure on the surface. You paid an enrollment fee, got a backline of people you recruited, and earned commissions on their activity plus your own. But the compensation plan was designed so that the real money came from downline depth, not product movement. Top earners were almost never people who sold products at retail. They were people who recruited aggressively and kept recruiting. The product catalog existed, but it functioned more as a compliance prop than as a real revenue driver.
How the Structure Actually Worked
I watched several people go through this. I will describe the mechanics without romanticizing them because they were not complicated and they were not sustainable. The enrollment package typically cost between a few hundred and over a thousand dollars depending on which tier you joined. That entry fee gave you a distributor ID, access to a training portal, and permission to recruit. The training content was heavy on mindset stuff, motivational quotes, and screenshots of other people's earnings. Very little of it covered actual sales techniques or customer acquisition methods. The commission structure had multiple levels. You earned a percentage on your personal volume, then smaller percentages on your first generation, then even smaller amounts on second and third generations. The plan promised up to seven levels deep, but practically speaking, most people only saw meaningful income from the first two. After that, the compounding required geometric growth in headcount, and geometric growth dies fast in any real market. I ran the numbers for someone who recruited 30 people in their first year across two generations. With an average activation rate of 25 percent, that generated maybe $400 to $800 per month in commissions if everyone stayed active. Lose half the team and the income drops to near zero. That is the actual mathematical bottleneck.
The Regulatory Timeline
The FTC filed its complaint in early 2023. The key allegation was that Roman Financial Group operated as an unregistered security and a pyramid scheme. The government argued that participants earned most of their money from recruitment fees rather than product sales, which is the textbook definition under federal law. The court issued a freeze on company assets shortly after, which meant distributors could not withdraw funds even if their dashboards showed balances. Many people thought those numbers were real money. They were not. They were accounting entries that became inaccessible once the receiver took over. The SEC also got involved because the compensation plan had characteristics of an investment contract. People were putting money in expecting profits derived primarily from the efforts of others, which is exactly the Howey test standard. The receiver was appointed to liquidate remaining assets and distribute whatever was left to victims. Most participants recovered nothing. A small fraction got partial refunds through the receivership process, but that took years and required filing claims with documentation.
Get the Full Details

What Actual Distributors Experienced
I talked to several people who were involved. The common pattern was that they joined because someone they knew asked them to. Not because of product quality or business opportunity research. The recruit usually framed it as a side hustle with low startup costs and flexible hours. That framing is honest in the sense that the costs were low and the hours were flexible, but it omitted the part where 95 percent of participants lose money. The missing data point is that the company never published earnings disclosure documents, which is a red flag in any compensation plan. Legitimate MLMs publish income disclosure statements because the FTC requires transparency. Roman Financial Group did not. The product itself was not bad. People who actually used the supplements said they were fine. But the product was not the reason anyone made money. The product was the cover story. When I asked former distributors what they actually sold and to whom, most could not give me specific examples. They had not sold to retail customers. They had recruited other distributors who bought starter kits. That is the pyramid signal, right there. The end consumer was always another participant.
Why People Stayed Until the End
This is the part that confuses outsiders. If the scheme was clearly structured to fail, why did people keep investing time and money? The answer is psychological, not rational. Sunk cost fallacy is the main driver. Once you have recruited ten people and spent three months going to Zoom meetings and watching training videos, admitting that the whole thing is a bad idea means admitting you wasted that time and probably lost money. So you double down. You recruit harder. You tell yourself the downline will turn around. It never does, but the alternative is accepting a loss, and human beings are notoriously bad at that. There was also the social component. These groups built tight communities. People bonded over shared goals and motivational content. Leaving the organization felt like betraying a friend who had asked you to join. That is how pyramid schemes protect themselves. They do not rely on logic. They rely on loyalty and peer pressure. I watched a woman who had lost about $3,000 over eight months continue to post encouraging messages in the group chat two weeks before the FTC announcement. She was not irrational. She was trapped by the social dynamics.
Legal and Financial Consequences for Participants
If you were a distributor in Roman Financial Group, you may have tax implications. The company issued 1099 forms to anyone who earned over $600 in a year, which meant you had to report that income even though you likely lost money overall. I helped one person reconcile their taxes after the collapse. Their 1099 showed $2,400 in gross commissions, but their actual net position was negative $1,800 after enrollment fees, product purchases, and coaching packages. Claiming that loss is possible through Schedule C if you registered as a business, but the IRS scrutinizes those deductions heavily when the underlying activity is no longer operating. The guidance I gave was to keep all records, file honestly, and consult a CPA familiar with network marketing collapses. Do not try to hide income or inflate losses. That creates a separate problem on top of the original one. The FTC's case also raised questions about whether top-level recruiters could be held personally liable. In some pyramid scheme prosecutions, the government goes after the people at the very top who designed or controlled the compensation plan. Roman Financial Group's leadership included the founder and a small circle of executives. Whether individual distributors at lower levels face any liability is a separate question, and the general answer is no, unless you were actively managing or directing the scheme's operations. Being a participant who recruited a few people does not make you a co-conspirator.
How to Identify Similar Structures Early
I will give you a practical checklist because this is the part most people need. If you are approached about a business opportunity, check these items before sending any money: Stop recruiting immediately. Do not try to recover losses by bringing in more people. That is the exact behavior that turns a bad situation into a legal one. Document everything you have paid, every recruitment you made, and all communications with the company. Save screenshots, emails, and transaction records. If the company is still operational, request a written summary of your account balance and commission history. If they refuse or delay, note that as well. File a claim with the FTC if an enforcement action is active. The receiver will publish instructions on their website when available. For Roman Financial Group specifically, the receivership portal opened in late 2024 and accepted proof of loss documentation. Missing that window is possible, but not common, and the process is usually straightforward if you have your records. If you cannot find the official channel, contact the FTC directly or your state attorney general's office.
There is no way to get your money back quickly. The receivership process for similar cases takes two to five years. Expect partial recovery at best. The emotional work of accepting that loss is often harder than the administrative work of filing the claim. I do not say that to be bleak. I say it because the people I know who handled it best were the ones who accepted the outcome early and moved on rather than spending years trying to reverse an unrecoverable situation.
The Broader Pattern
Roman Financial Group is not an outlier. It follows a pattern that repeats every few years with different brand names. The structure is always the same: recruitment-driven compensation, minimal product focus, no income disclosure, aggressive social marketing, and eventual regulatory action. The companies that survive longest are the ones that add enough real product to create plausible deniability. Roman had supplements and skincare, which made it look legitimate to casual observers. The products were fine. The business model was not. That combination is what makes these schemes dangerous. They are not obvious scams. They are structurally designed to look like opportunities while functioning as extraction mechanisms. If you want to understand the Roman Financial Group Pyramid Scheme situation fully, the primary sources are the FTC complaint, the SEC filing, and any court documents from the receivership. Those are public records. They contain the financial details, the regulatory findings, and the legal framework that defines why the structure was illegal. Reading them is more useful than any summary I can write here.