Most people pull money from their Roth IRA without running the numbers first. They assume since it is "after-tax money" everything comes out free. That assumption costs them money every single time.
A Roth Ira Early Withdrawal Calculator exists because the withdrawal ordering rules are not intuitive. The IRS has a specific sequence you must follow when you take money out, and if you get it wrong you will either overpay taxes now or trigger an audit later.
How the Calculator Actually Works
You feed it three numbers: your total account balance, how much you have contributed over the years, and how much of that has grown as earnings. It outputs a breakdown showing what portion is tax-free, what portion is taxable, and whether the 10% penalty applies.
The logic behind it relies on FIFO ordering. Contributions always come out first. They are never taxed or penalized because you already paid tax on them. After contributions are exhausted, converted amounts come next. Each conversion has its own five-year clock. If a conversion happened less than five years ago and you are under 59 and a half, that chunk gets the 10% penalty even though the tax itself is deferred. Earnings are last. They are always taxable plus penalized unless you qualify for an exception.
I spent three hours one evening trying to manually calculate a withdrawal for a client who had done three Roth conversions over four years with varying start dates. The fifth-year windows didn't overlap. I ended up using a spreadsheet with individual rows for each conversion and cross-referencing the dates against the distribution amount. A calculator like this does that in about ten seconds, but only if you input the conversion history correctly.
Here is the part most online calculators skip. You need to know the exact date of each conversion, not just the year. The five-year rule for conversions starts January first of the year the conversion occurred. If you converted in December 2021, your five-year window ends December 31, 2025. A calculator that only asks for the year will give you the right answer for most people but will be wrong for anyone who converted late in the calendar year.
When the Calculator Will Mislead You
Most free calculators online assume a standard case. They do not handle partial conversions, reconversions, or rollovers from traditional IRAs into Roth accounts that happened before 2018. If your situation involves any of those, the output is a guess, not a calculation.
Another blind spot is state taxes. The 10% penalty is federal only. Some states conform to the federal treatment and some do not. A few states tax Roth earnings differently or do not allow the penalty deduction. If you live in California, New Jersey, or Massachusetts, for example, the state-side number could be significantly different from what a generic calculator shows. I had a client in California who thought his penalty was 10%. It was actually 15% once state rules and the inability to deduct the penalty on the state return were factored in.
There is also the qualified distribution question. If you are over 59 and a half and your Roth has been open for at least five years, you do not need a calculator at all. Everything comes out free. A lot of people do not realize that the five-year clock for the account itself started on January first of the year you opened your first Roth IRA, not the year of your current account. If you opened a Roth in 2010 and converted money in 2023, your earnings from the 2010 contributions have been waiting seven years for you, while your 2023 conversion earnings only have two.
A Practical Walkthrough
Say you have $85,000 in your Roth IRA. You have contributed $60,000 total over the years. That means $25,000 is earnings. You need $20,000 and you are 42 years old.
The calculator will show that $20,000 comes entirely out of your contribution basis. Zero taxes. Zero penalty. You walk away with the full amount.
Now say you need $70,000. The first $60,000 is still contribution basis and remains tax-free. The remaining $10,000 comes from earnings. That $10,000 is added to your taxable income for the year and hit with the 10% penalty, which is $1,000. If you are in the 22% federal bracket, you also owe $2,200 in income tax. Total cost of the withdrawal is $3,200.
If you had instead taken the $20,000 from earnings only, keeping your contribution intact, the tax hit would be the same on $20,000 of earnings but you would have burned through $20,000 of future tax-free growth. The calculator can show you both scenarios side by side if you adjust the inputs.
The hardest part is getting your contribution total right. Many people estimate it. If you are not sure, pull your Form 5498 from each year and add up the Roth IRA contributions. Do not include earnings, rollovers, or conversion amounts. Those are separate buckets.
Where to Find One That Is Worth Using
IRS.gov has a basic calculator but it only handles the standard case and does not break down conversion windows. Most financial advisor tools on commercial sites are fine for quick estimates but lack the conversion detail I mentioned above. A couple of the better ones that handle multi-conversion scenarios properly include the tool on Investor.gov and the spreadsheet versions circulated by CPA forums, though the latter require more manual input.
I use a hybrid approach. I run the numbers through a free calculator first for a rough picture, then I verify the conversion five-year windows manually because the calculators I have seen rarely flag a conversion that is still within its penalty window unless you explicitly enter each one.
If you have only contributions and earnings with no conversions, any basic calculator will work. If you have ever converted a traditional IRA to a Roth, you need one that tracks individual conversion dates. That is the difference between a useful tool and a waste of time.
Bottom Line
A Roth Ira Early Withdrawal Calculator saves you from two mistakes: assuming all withdrawals are penalty-free and misreading the five-year conversion windows. It does not save you from bad input. If your contribution total is wrong, the whole output is wrong. Double check your numbers against actual tax forms before you trust the result.
Gallery Roth Ira Early Withdrawal Calculator
Irs Ira Withdrawal Calculator , Calculate Your RMD – NQVWO
Best Roth IRA Calculator To Use In 2025
Roth Ira Tax Calculator | Roth IRA Calculator – ZQKX
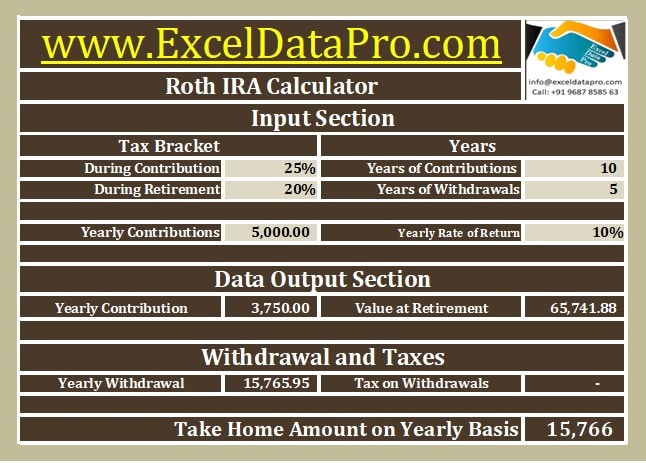
Download Roth IRA Calculator Excel Template - ExcelDataPro
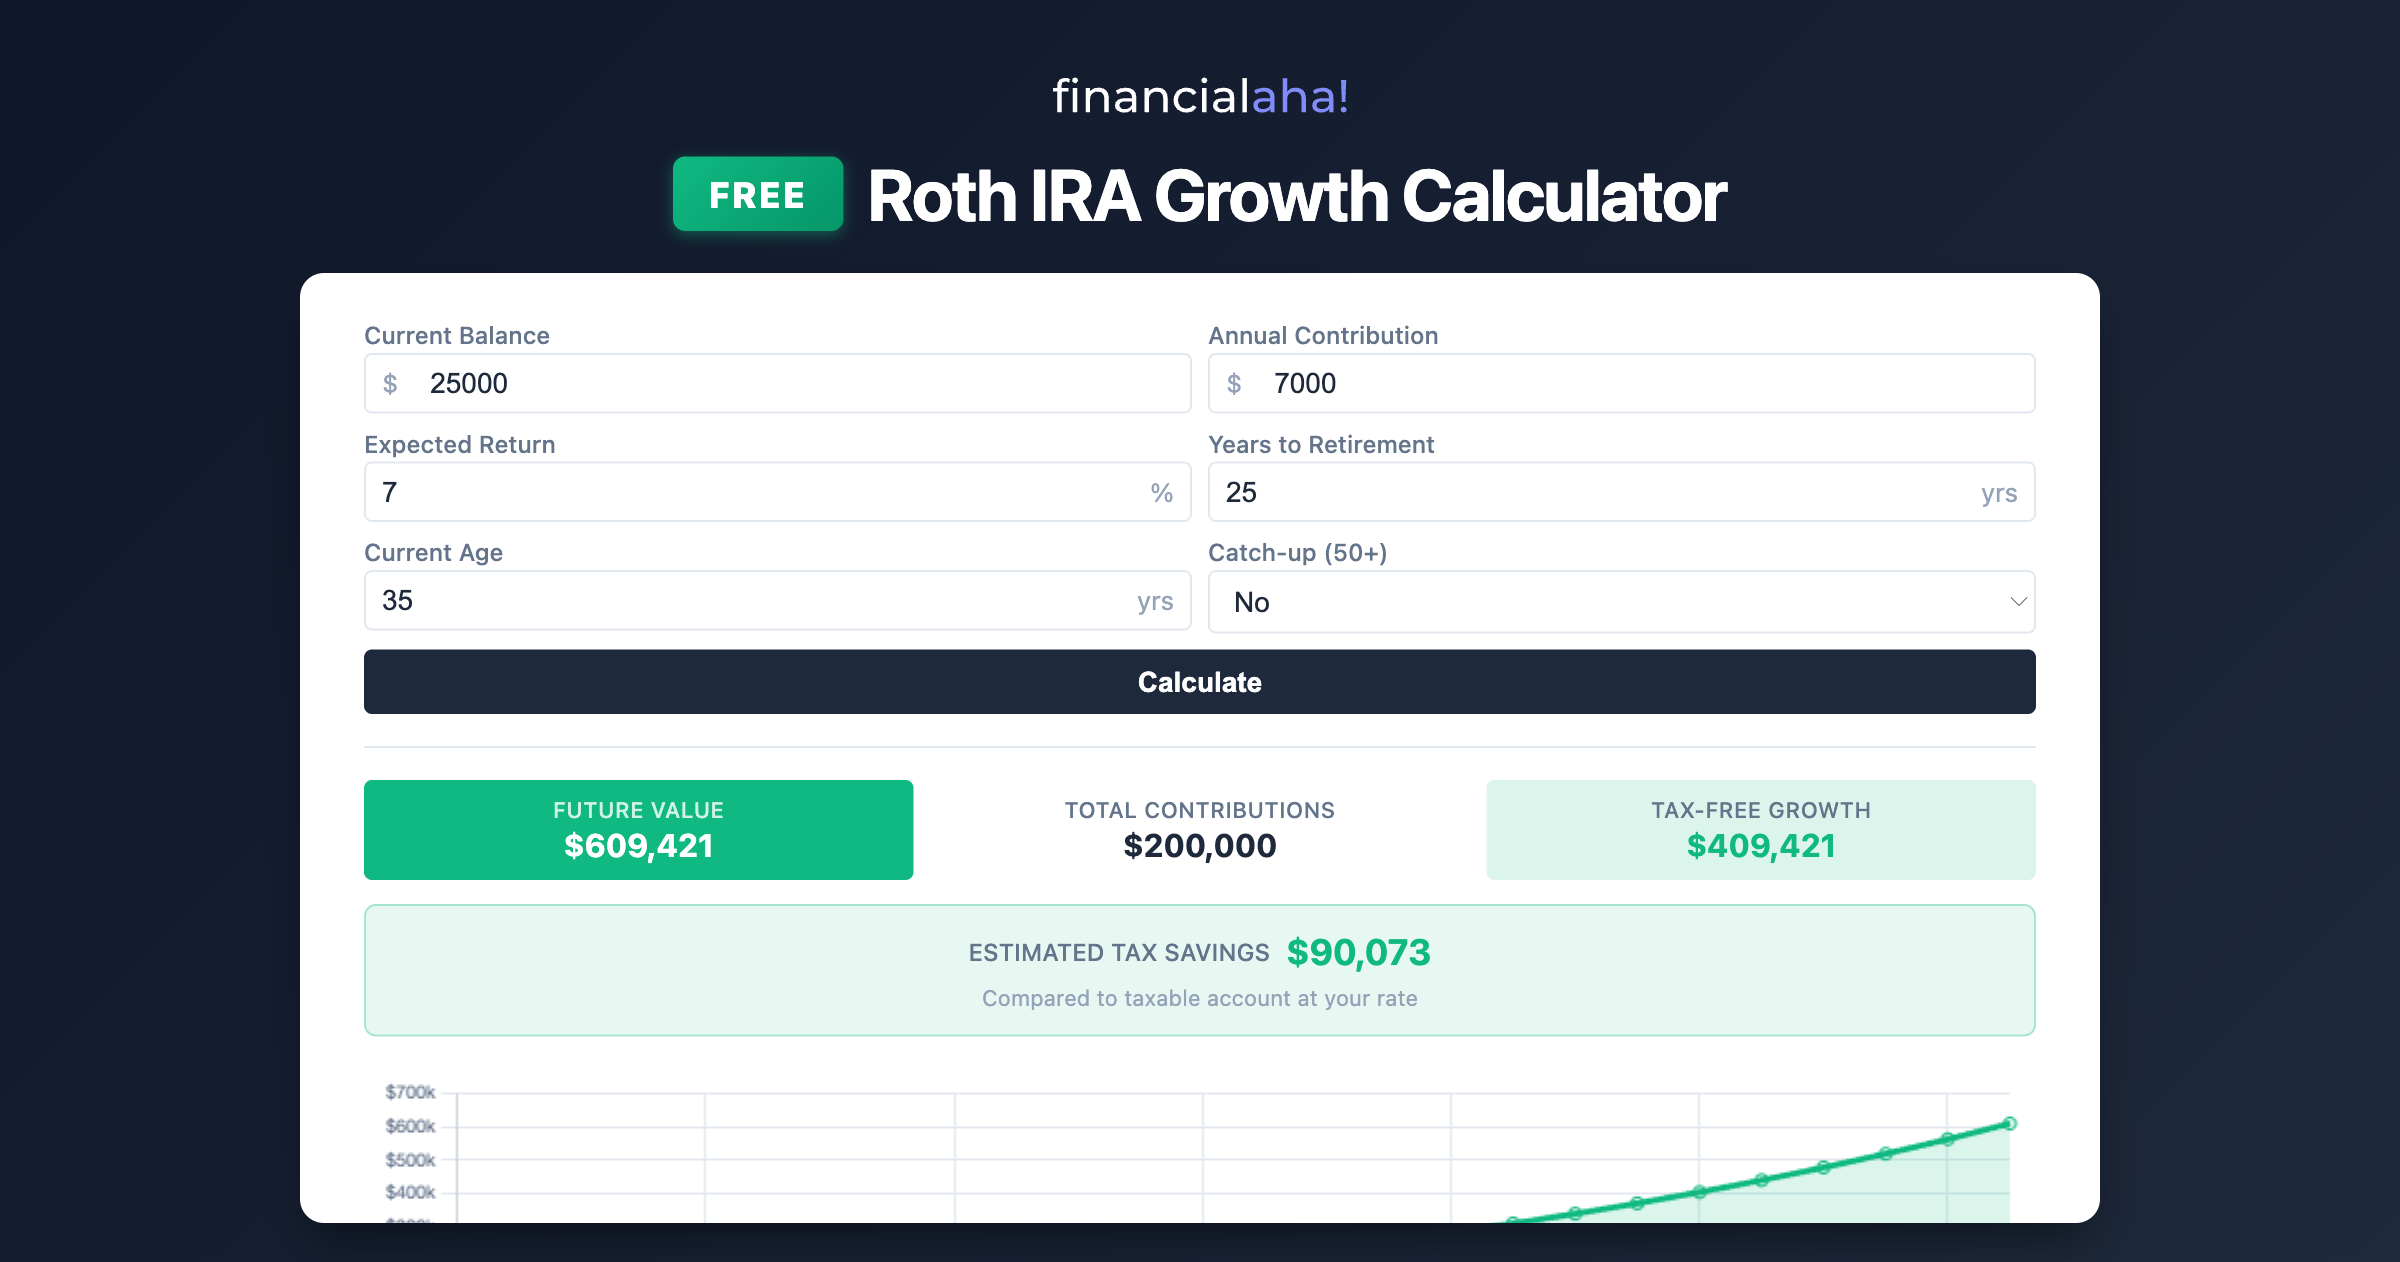
Free Roth IRA Growth Calculator | Tax-Free Retirement Projections | FinancialAha!