Understanding Bank Routing Numbers
A routing number is a nine-digit code assigned to U.S. financial institutions to identify them during electronic fund transfers. It's on every check you've ever written, sitting in the bottom left corner. If you've never noticed it, look at your next paycheck stub deposit slip. The American Bankers Association maintains the entire system. They assign these numbers, issue new ones when banks merge or restructure, and retire numbers that are no longer in use. It's not complicated, but it's also not well-documented in one place, which is why this Routing Number Guide exists.
Where Routing Number Guide Becomes Necessary
I spent three years in accounts payable at a mid-size manufacturing firm before moving to a payments operations role. The problem wasn't that routing numbers were hard to find. The problem was that banks often have more than one. Chase, for example, has a main routing number for ACH transfers and a completely different one for wire transfers. Same bank, different digits, different purpose. I've watched junior accountants send a $40,000 vendor payment to the wrong queue because they pulled the routing number from the website footer instead of the ACH origination form. Here's what nobody tells you upfront: a single bank can have dozens of active routing numbers. It depends on the state where the branch was originally chartered, the type of transaction, and sometimes which processing center handles your account. PNC Bank alone has over twenty routing numbers in circulation. If you're processing payroll or setting up recurring payments, you need to match the right number to the right transaction type, or the payment bounces back, usually on a Friday afternoon.
How to Find and Verify a Routing Number
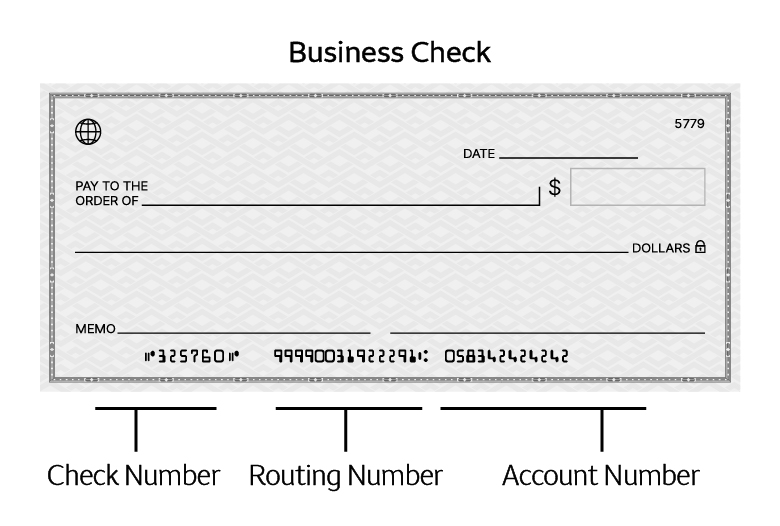
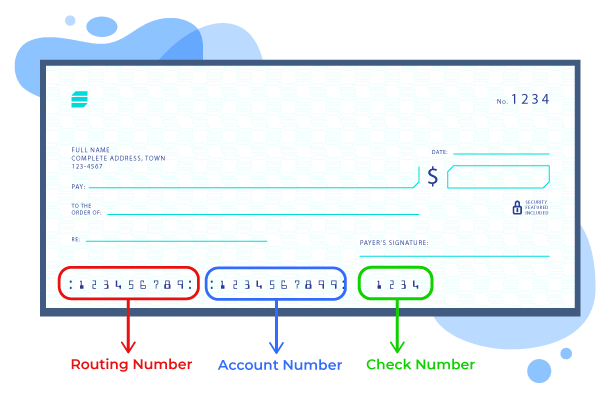
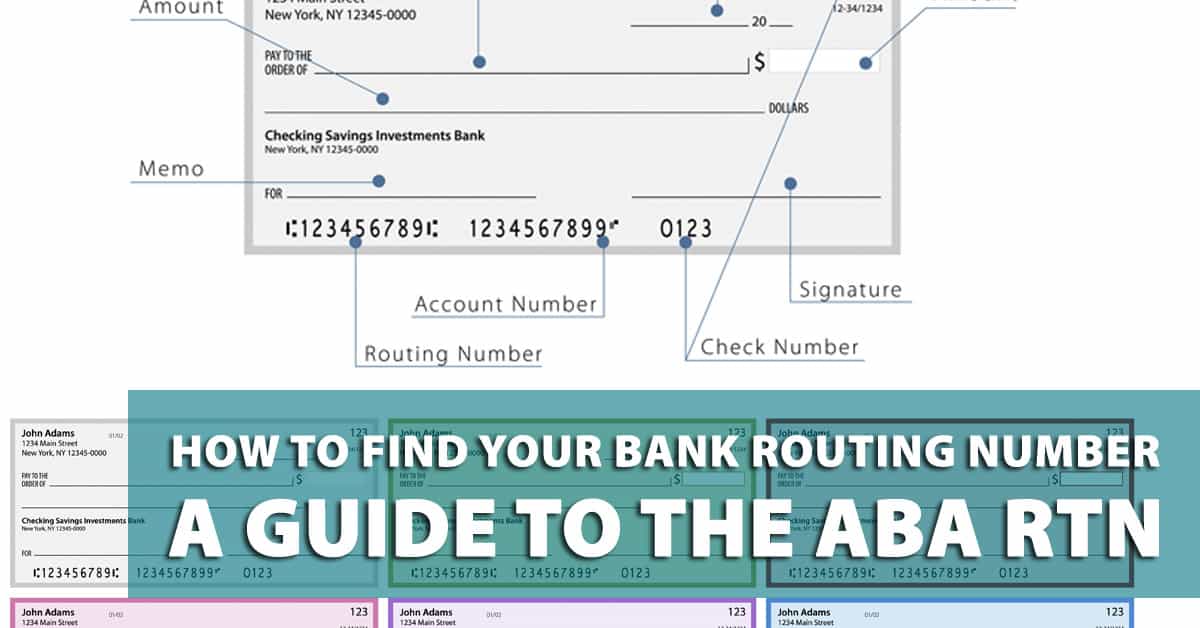
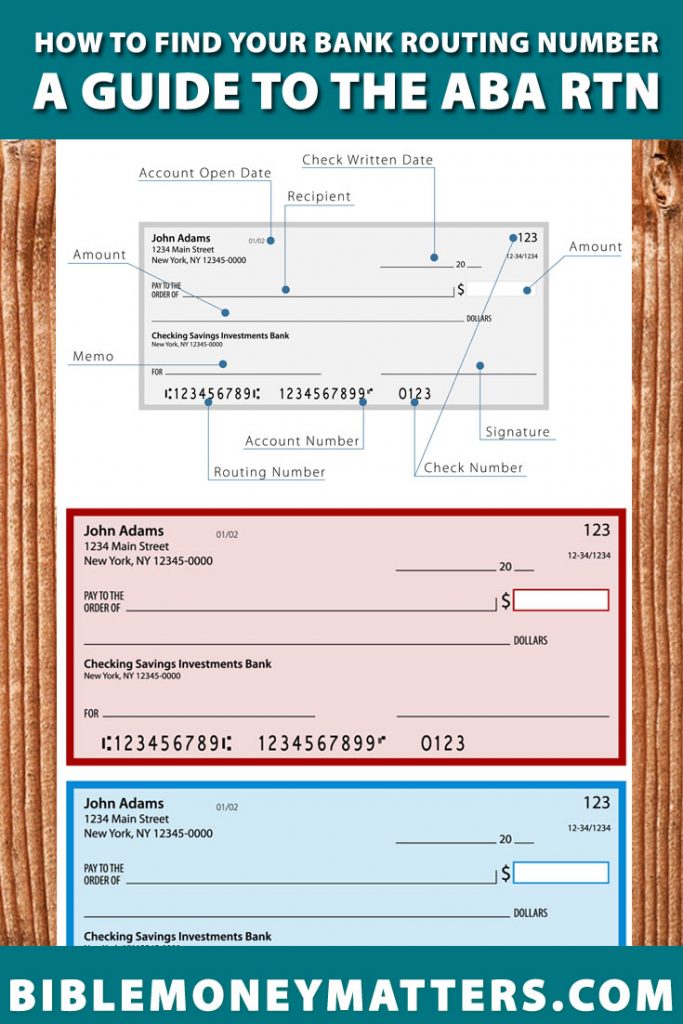
Start with the physical check. The first set of nine digits at the bottom left is your routing number. The second set is your account number. The third set, if it appears, is a check serial number and means nothing for routing purposes. This works for personal accounts and most business accounts. For online-only banks or situations where you don't have a check, go to the bank's official website and search their help section. Wells Fargo's routing lookup tool, for instance, asks for your state and transaction type and returns the correct number. It's not perfect sometimes it defaults to the corporate headquarters routing number when your account was opened at a branch that uses a different one. Always double-check against a live transaction record if you're processing anything over five figures. The ABA website doesn't publish a searchable public database. You'll find third-party sites that claim to have everything, but their data is months or sometimes years out of date. I've seen people use stale routing numbers from merged banks and watch payments fail repeatedly until they dug up the original chartered routing number in the bank's merger documentation.
Get the Full Details
Common Pitfalls That Cost Real Money
Wire transfers and ACH transfers use different routing numbers at most major banks. Capital One uses 071000505 for ACH and 071000013 for wires. If you mix them up, the money doesn't go to the wrong bank. It sits in limbo at the receiving bank's correspondent account, gets rejected, and comes back to you after three to five business days. You lose the float, you annoy whoever was waiting on that money, and if it's a payroll cycle, you're explaining yourself to people who are already stressed about missing rent. International wires coming into the U.S. sometimes require an additional SWIFT code even when you have the routing number. The routing number only gets the wire to the right bank. The SWIFT code identifies the specific branch or department. I learned this the hard way when a supplier in Ohio was trying to set up a direct deposit from our German office and we kept getting returned messages about "unable to locate branch." The routing number was correct. We just didn't have the SWIFT code for the regional clearing center. Another thing that catches people off guard: some credit unions use the same routing number across multiple states because they're federally chartered and processed through a single system. Others have different numbers per state. If you're managing payments for a distributed team, verify each location individually rather than assuming one number covers everything.
When Routing Numbers Change
Mergers are the main driver of changes. When a smaller bank gets absorbed into a larger one, the acquired bank's routing numbers eventually retire. There's usually a transition period of six to eighteen months where both numbers work, but that window isn't guaranteed. I worked through a merger in 2019 where the acquiring bank announced a routing number change with ninety days notice. About forty percent of our vendor files still had the old number six months later. We caught it during the quarterly audit and had to reconfigure payment runs for roughly two hundred accounts. It took a long Tuesday. Bank branches that change their charter or move to a different Federal Reserve district can also get new routing numbers. This is rarer but happens enough that if you're doing a routing number lookup for an account you haven't processed in over two years, verify it again rather than assuming nothing changed.
Practical Steps for Businesses Handling High Volume
If you're processing more than fifty payments a month through ACH or wire, build a routing number verification step into your workflow. Don't rely on memory or a single source of truth that might rot. Pull the routing number directly from a recently processed check or statement for each vendor. Cross-reference it against the bank's published lookup tool. Log the verification date so you know when to check again. Automated systems can reduce manual errors but they introduce their own failure modes. I've seen accounts payable software auto-populate a routing number from a vendor's profile and then silently accept a payment that failed because the profile hadn't been updated since a merger. The system logged it as "sent successfully" because it accepted the transmission. The rejection came back as a return code three days later. Set up exception reporting that flags any return codes within the first ten business days of a new vendor relationship. Catches more problems than you'd expect. The downside of all this attention to detail is that routing number management adds friction to processes that should be straightforward. Vendors complain when you ask them to confirm numbers instead of just taking what they send. Sometimes they send the wrong one intentionally because they're using a different account for different purposes and didn't realize you needed the specific routing number for their particular account type. Be patient. It happens constantly.