
Setting Up a Rule 10b-1 Plan That Actually Stands Up
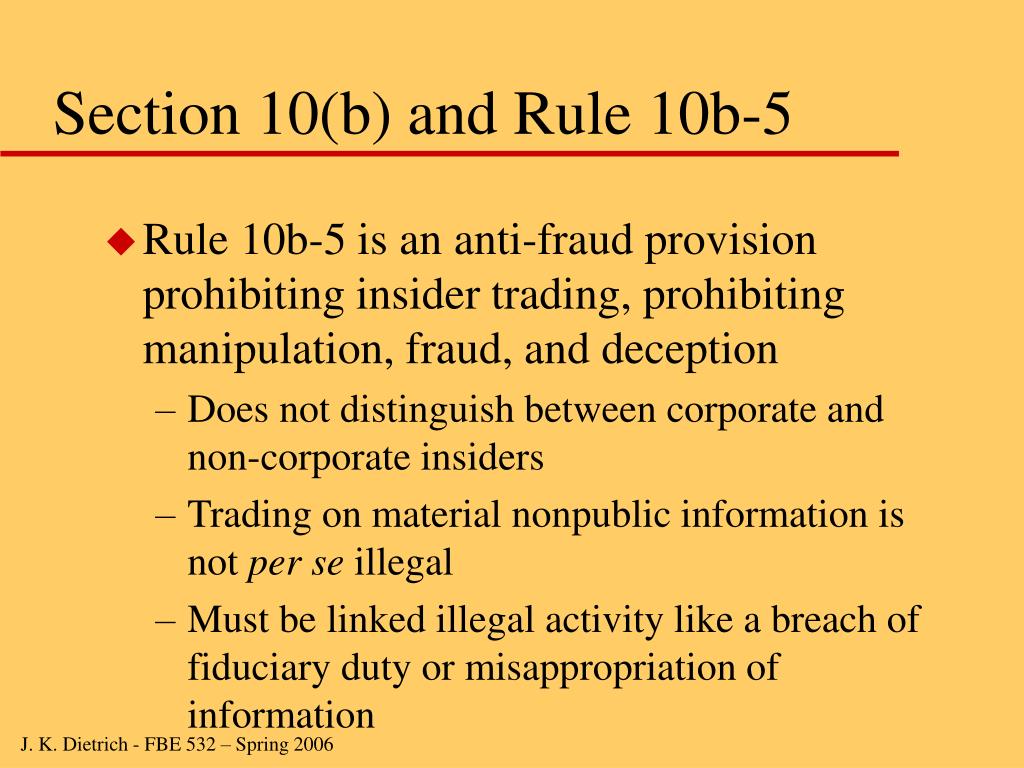
The first thing you need to understand about Rule 10b-5 Insider Trading is that it is not a plan. It is a liability standard. Rule 10b-1, adopted in 2007, is the procedural shield that sits on top of it. Most people conflate the two and then get burned because they built a plan around the wrong rule. Rule 10b-5 makes it illegal to trade on material nonpublic information. Period. The SEC does not care about your intentions. They care about whether a reasonable factfinder could conclude you possessed MNPI at the time of the trade. The plan is just documentation that helps argue the negative. I spent six years in compliance at a mid-tier broker-dealer reviewing pre-clearance requests and post-trade analysis for equity traders. The worst cases I saw were never the ones where someone clearly abused insider information. They were the ones where someone forgot to document a timing decision or modified a plan mid-stream without proper authorization. Those look like conscious evasion to an examiner. I will walk you through how to build a plan that survives that scrutiny, including a specific edge-case scenario I ran into more times than I would like to admit.
How Rule 10b-5 Insider Trading Actually Works in Practice
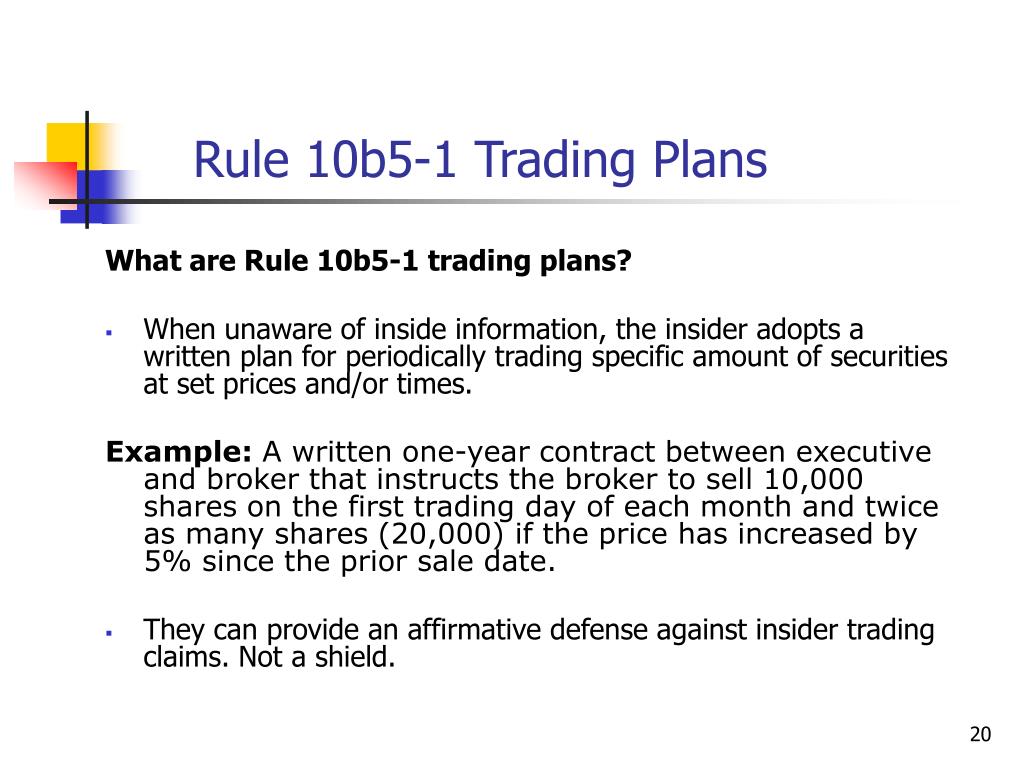
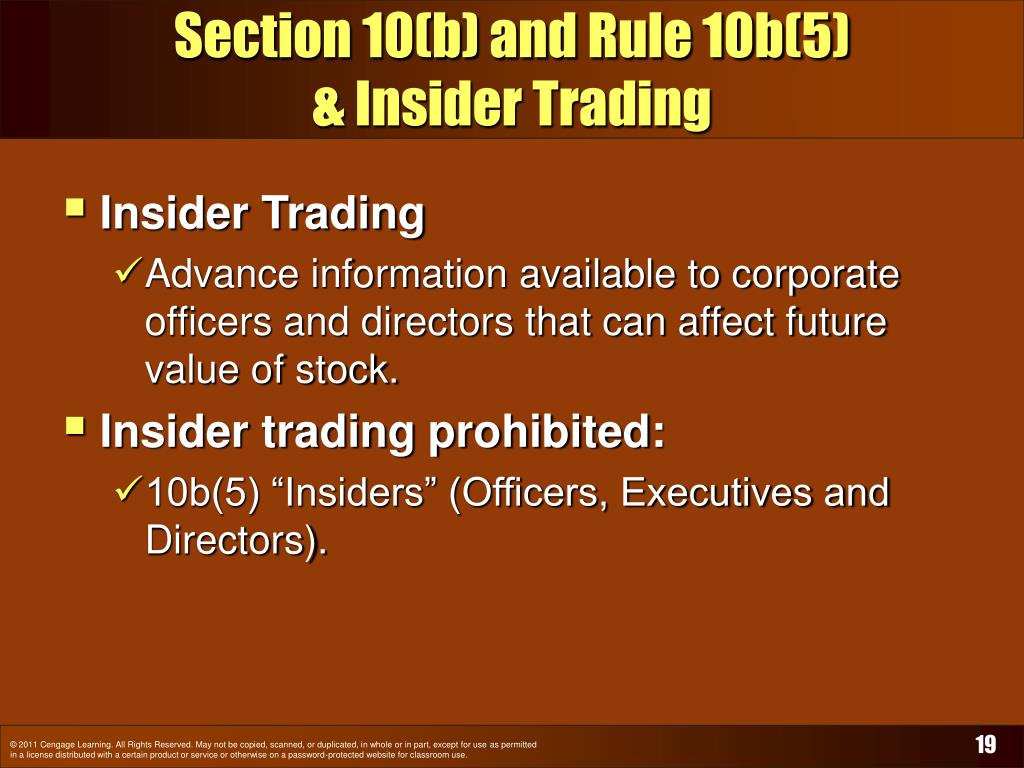
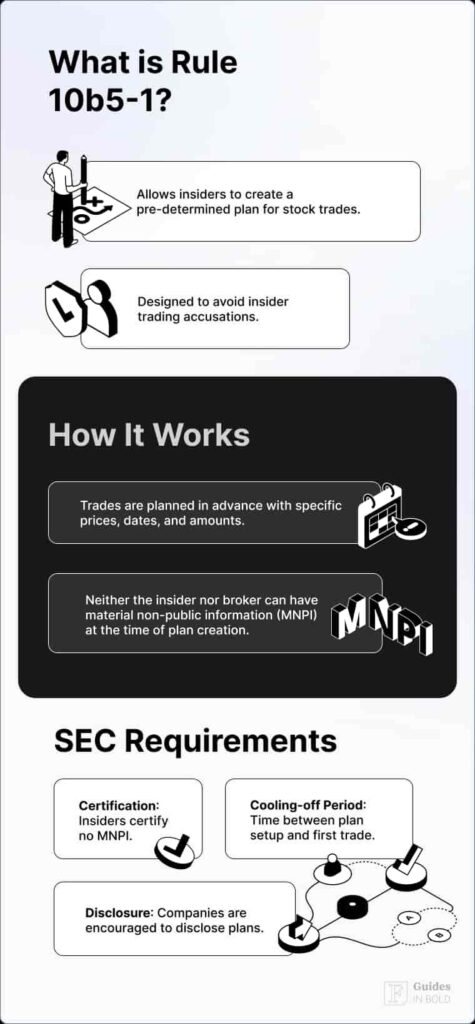
Rule 10b-5 has three components the government has to prove for a conviction: a deceptive device or contrivance, in connection with the purchase or sale of a security, using material nonpublic information. Most enforcement actions are civil, so the standard is preponderance of the evidence rather than beyond a reasonable doubt, but the structural logic is identical. The critical insight that people miss is that possession is enough. You do not have to have actually used the information in your decision-making process. If you had it and you traded, the burden can shift to you to show you did not rely on it. That is why the plan matters. Not because it proves innocence. Because it creates a paper trail that forces the SEC to do actual work. When you draft a Rule 10b-1 plan, you are creating a contractual framework that separates your trading decisions from any MNPI you might encounter later. The plan must satisfy three conditions: it has to be adopted in good faith, it has to specify the amount price and timing of trades or set an objective formula that determines them, and it has to be governed by an independent coordinator who has no access to your inside information. If any of those elements is weak, the safe harbor falls apart and you are back to a straightforward Rule 10b-5 analysis.
Building the Plan Step by Step
Start with the adoption date and your identity. Write down exactly who you are, your title, the issuer or issuers whose securities you are authorized to trade, and the date the plan becomes effective. This seems basic but I have seen plans where the effective date was left blank or the signatory was someone who was not actually independent. One firm I worked with had a CCO who also served as the plan coordinator. That is a conflict that will get flagged immediately during an exam. The coordinator needs to be structurally separated from your informational flow. Next, define the trading parameters with enough precision that a stranger could execute them without asking you anything. This means specifying dollar amounts or share counts, the time windows during which trades can occur, and the triggers that authorize execution. You can use a formula like a fixed percentage of compensation or a target dollar value rebalanced quarterly. You can also use a pre-determined schedule, like the first business day of each quarter within a thirty-day window. What you cannot do is leave discretion to yourself at the moment of trade. If you get a tip about an earnings miss two days before the plan window opens and you choose not to trade during that window because of it, you just violated the plan's independence requirement and lost the safe harbor retroactively. The independent coordinator clause is where most plans fail on paper. The coordinator needs actual authority to buy and sell without consulting you. In practice, this means a third-party administrator or a compliance officer who does not report to you and has no way of receiving your MNPI. I recommend putting the coordinator's contact information and authority delegation in writing and keeping it on file. When I was reviewing plans, the ones that held up in exams were the ones where the coordinator's signature appeared on every execution order without exception.
Get the Full Details
A Specific Problem I Dealt With and How I Fixed It
About three years into my compliance career, a trader at one of our larger accounts set up a proper Rule 10b-1 plan for his company stock. Everything looked clean on paper. Then the company announced a merger. He was in possession of MNPI during the confidential period. The plan had a trading window open that week and he had previously authorized a block trade to execute automatically. The independent coordinator was sitting there ready to pull the trigger at 9:31 AM when the trader called and asked to suspend the trade until after the merger announcement. From the outside, that looks like a textbook 10b-5 violation waiting to happen. The trader had MNPI and he influenced the timing of a trade connected to that stock. But here is the nuance that almost got overlooked: the trader did not cancel the plan. He modified it. He asked the coordinator to reschedule the execution to a date twenty business days out, outside any information window. The coordinator complied and documented the change as a plan amendment, not a personal instruction tied to the merger. We retained the phone recording, the email chain, and the amended plan documentation. When the SEC eventually asked about the trade, we produced the full record. The modification was based on a general policy the plan allowed for rescheduling with forty-eight hours notice, not on the merger itself. The trade went through two weeks later when the information was public. The filing held. The lesson from that is that modifying a plan is not automatically fatal. But you have to modify it under the plan's own terms, with documentation that shows the reason was procedural and not informational. If you amend a plan because you heard something, you are right back inside Rule 10b-5 territory and the plan provides zero protection.
Common Pitfalls That Will Kill Your Safe Harbor
The most common mistake I see is people adopting a plan after they already possess MNPI. The rule requires good faith adoption, and good faith means you cannot be carrying material information at the time of signing. If you are in a situation where you expect to receive MNPI regularly, like an executive in a tech company working on product launches, adopt the plan before you walk into that boardroom. Otherwise the plan is void from the start and you are trading naked under Rule 10b-5. Another trap is the informal amendment. Traders will email their coordinator and say cancel tomorrow's trade, take it next week. The coordinator complies. That email exchange is now evidence that the trader had knowledge that influenced trading timing. Even if the trader genuinely did not have MNPI, the appearance is damaging. Always amend plans through the formal mechanism the plan itself establishes, usually a written request submitted a minimum number of business days before the intended trade date, with no reference to current events or unpublished information. There is also the issue of affiliated persons. If you are a director or officer, your trades are automatically subject to Section 16 reporting regardless of whether you have a Rule 10b-1 plan. The plan does not eliminate your reporting obligations. It only provides the affirmative defense against insider trading allegations. I have seen people treat the plan as a replacement for 16(b) compliance and then get hit with both an insider trading investigation and a separate short-swing profit claim. Those are two different legal frameworks that do not cancel each other out.
What the Plan Cannot Do for You
A Rule 10b-1 plan is not a get-out-of-jail-free card. It is a conditional defense. If the SEC can show that you adopted the plan as part of a scheme to evade insider trading laws, the safe harbor is unavailable. Courts look at the totality of circumstances: was the plan adopted at a time when you were aware of pending material events, were the trading parameters unusually restrictive or unusually loose, did you frequently modify or cancel trades, was the coordinator truly independent or a figurehead. The plan that looks most suspicious is the one that is too perfectly tailored to the trader's known information exposure. If you adopt a plan two days before a locked-down earnings call with trading windows that only open when you know you will not have access to the data, an examiner will notice that pattern. The plan also does not protect you from Section 16(b) claims. Short-swing profit recovery is strict liability. Buy and sell within six months and you owe the profits to the issuer regardless of whether you had any inside information. A Rule 10b-1 plan will not shield you from that. Some traders assume it does and then get blindsided by a derivative suit from a shareholder demanding disgorgement. That is a completely separate legal exposure that exists independently of the insider trading statute. There is also a practical limitation that nobody talks about enough. The plan only covers the securities and the issuer you specify. If you trade a different stock while the plan is active, that trade is not covered. I have seen traders assume their plan protects all their equity transactions across all holdings. It does not. It protects only the securities identified in the plan document and only trades executed through the independent coordinator according to the plan's terms. If you place an order yourself through your brokerage account for a different company, you are on your own under Rule 10b-5 with no safe harbor available.
The Documentation You Need to Keep
Retention matters more than most people realize. Keep the original adopted plan, every amendment, every execution instruction, and every communication with the coordinator for at least six years after the last trade under the plan. That covers the statute of limitations for SEC civil actions and overlaps with the typical retention period for exchange records. I have seen firms lose cases simply because they could not produce the original plan document when the examiner asked for it. If you cannot produce it, the examiner assumes it never existed and the safe harbor is gone. Store the documents in a way that prevents alteration. Email the plan to your compliance file, not to a personal inbox. Have the coordinator countersign each amendment. Date and initial every page. These are small things that look like bureaucracy until you are in a deposition and the prosecutor asks when you signed page three and you cannot remember because you never actually signed page three.
Rule 10b-5 Insider Trading: The Bottom Line
The core issue with Rule 10b-5 Insider Trading is that it is broad and the enforcement standard is low. The plan is your only practical tool for managing the risk, but it only works if you treat it as a binding operational framework and not a piece of paperwork you fill out once and forget. Adopt it before you need it. Keep it running through an independent coordinator. Do not modify it based on information you possess. Document everything. And understand that it solves one problem, insider trading liability, while leaving you exposed to every other securities law violation that might apply to your trading activity.
: Inside Information in Markets PowerPoint Presentation, free download - ID:339049](https://image.slideserve.com/339049/5-7-rule-10b5-1-l.jpg "PPT - [5](1): Inside Information in Markets PowerPoint Presentation, free download - ID:339049")
