Getting Your Head Around the Rule of 72 Before You Build a Worksheet
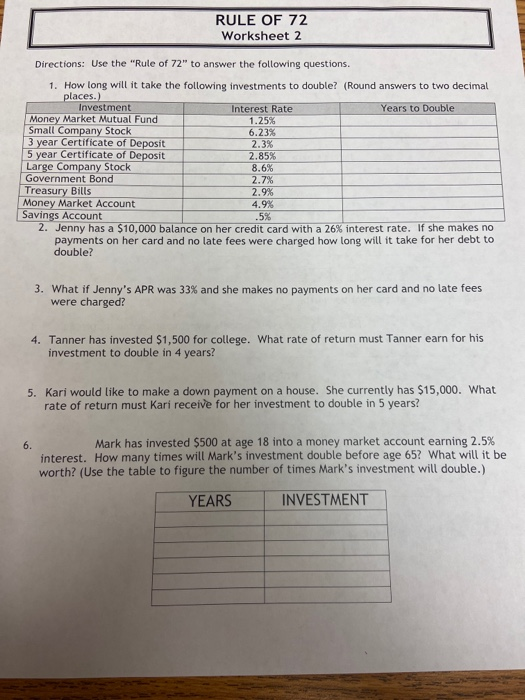
The Rule of 72 is just a shortcut. Divide 72 by your annual interest rate and you get a rough number of years until your money doubles. It works well enough for rates between 6% and 10%, which is where most people are sitting anyway. Beyond that range, the accuracy drifts and you start noticing the gap between what the rule says and what the actual compound interest formula spits out. I built my first proper spreadsheet version of this back when I was doing personal finance modeling for a small fund. The client wanted to compare four different retirement scenarios side by side without running full DCF models. A simple sheet with the Rule of 72 did the trick in about twenty minutes. They got the intuition they needed. Full amortization schedules would have taken three hours and confused half the stakeholders.
How to Actually Build a Rule Of 72 Worksheet
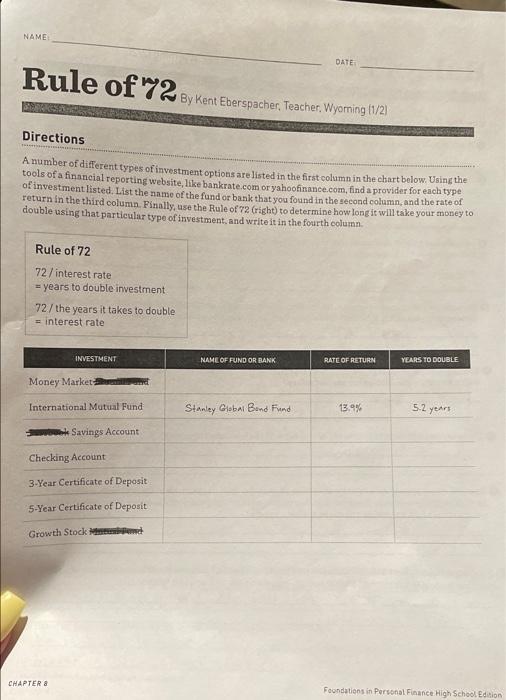
Set up three input columns: one for the starting principal, one for the annual rate, and one for the compounding frequency. The compounding part matters more than most people realize. The classic Rule of 72 assumes annual compounding. If you're working with monthly or quarterly compounding, the effective rate shifts slightly and your doubling time gets shorter. I learned this the hard way when a client compared their 401(k) growth against a certificate of deposit using the same rule and couldn't figure out why the numbers didn't match up. The basic calculation goes in a fourth column. Take 72 and divide it by the rate percentage. That gives you the doubling period in years. From there you can layer in more useful outputs. Add a column that multiplies the years by the rate to verify you're close to 72. Add another that shows what the principal would actually be after one doubling period using the compound formula. That's where you spot the error margin. Here is what a working sheet looks like on paper:
Input section has Principal | Annual Rate (%) | Compounding Frequency. Then a Results section with Doubling Period (Years) | Actual Future Value After One Doubling Period | Difference from Rule of 72 Estimate. The difference column is honestly the most useful part. It shows you when the shortcut is holding up and when it is drifting. For the actual worksheet file, you can build this in any spreadsheet program. Excel, Google Sheets, LibreOffice Calc all work fine. I use a mix of absolute and relative references so you can drag the formula down across rows without breaking anything. Format the rate cells as percentages and the output cells as numbers with two decimal places. That is the only real formatting that matters here.
Get the Full Details

Where the Rule of 72 Breaks Down
At very low rates, below about 4%, the rule starts underestimating the doubling time. The actual math says it takes longer than 72 divided by the rate suggests. At very high rates, above 15%, it overestimates. Your money doubles faster than the rule claims. The curve is nonlinear and 72 sits at a sweet spot somewhere in the middle. If you need precision, especially for rates outside that 4% to 15% band, switch to the natural logarithm approach. The exact doubling time is ln(2) divided by ln(1 plus the periodic rate). That takes one extra step but it is accurate at every rate. I keep a small note in my worksheets flagging when the Rule of 72 estimate diverges by more than half a year from the precise calculation. That threshold catches most real world mistakes before they become problems. Another edge case that catches people out is negative rates. The Rule of 72 does not handle those gracefully. If you are working with European bonds or certain money market accounts that have dipped into negative territory, the formula breaks entirely. You just have to fall back to the compound formula and calculate manually. I ran into this in 2023 when a client was evaluating German bunds and tried to apply the rule. We spent ten minutes just figuring out why the output was returning nonsense values before I told them to stop and use the actual math instead.
Adding Realistic Scenarios to Your Worksheet
Once the basic structure is in place, the next layer is making it useful for actual decisions. Most people building this worksheet want to answer questions like how long until my retirement savings double, or which account gives me the fastest path to a target amount. You can add scenario columns for different rate environments. A conservative scenario at 4%, a balanced one at 7%, and an aggressive one at 10%. Seeing the doubling periods side by side makes the trade offs immediately obvious. Consider adding a contribution column too. The basic Rule of 72 assumes no additional deposits. That is fine for a lump sum, but most people add money regularly. When contributions are part of the equation, the doubling concept itself changes meaning. You are no longer doubling a fixed principal. You are growing a stream of cash flows. I usually add a note in those cases pointing users toward a future value of annuity calculation instead of relying on the rule. The Rule of 72 Worksheet can still live on the same sheet. It just stops being the main tool once contributions enter the picture.
Quick Distribution Note
If you want a ready-made version instead of building from scratch, there are a few free templates floating around the usual spreadsheet communities and personal finance forums. Search for a Rule Of 72 Worksheet on Google Sheets template galleries or Reddit threads focused on personal finance. Grab whatever looks clean, audit the formulas before trusting them, and adjust the compounding assumptions to match your situation. The ones I have used over the years tend to be simple and uncluttered. The slightly more polished versions often bake in incorrect compounding adjustments that look right but are off by a fraction. Always check the difference column I mentioned earlier. It will tell you if something is wrong within a second. The rule itself is old. It has been around long enough that I rarely see anyone need to relearn it. What tends to go wrong is the application. People forget that it is an estimate. They treat it like a precise tool. The worksheet format forces you to see both the estimate and the actual value side by side, which keeps you honest. That is the real point of building one out in a spreadsheet rather than just doing the math in your head.