How RV loan calculations actually work in practice
Most people treating an Rv Loan Calc as a black box end up confused when the payment they see doesn't match what the dealer quotes them. That's usually because they're not accounting for how dealers structure these loans versus how raw formulas work. Let me walk through what's actually happening under the hood and where things tend to go wrong.Start with the basic framework. An RV loan is an installment loan, same mechanics as a car loan. You take the principal amount, apply the annual percentage rate divided into monthly increments, and amortize it over the term. The standard formula is M = P[r(1+r)^n]/[(1+r)^n-1], where P is principal, r is your monthly interest rate, and n is total number of months. That gives you the base payment before taxes, fees, insurance, and any add-ons enter the picture. Here's the part nobody warns you about upfront: the decimal balance method versus the daily interest method. Most online calculators assume a standard 30-day month for simplicity, but some lenders—especially credit unions and larger national banks—calculate interest daily based on the actual outstanding balance. When you're looking at a $85,000 Class A motorhome with a 72-month term, the difference between those two methods can show up as $40 to $90 over the life of the loan. Small individually, but noticeable if you're shopping between lenders.
Using Rv Loan Calc effectively
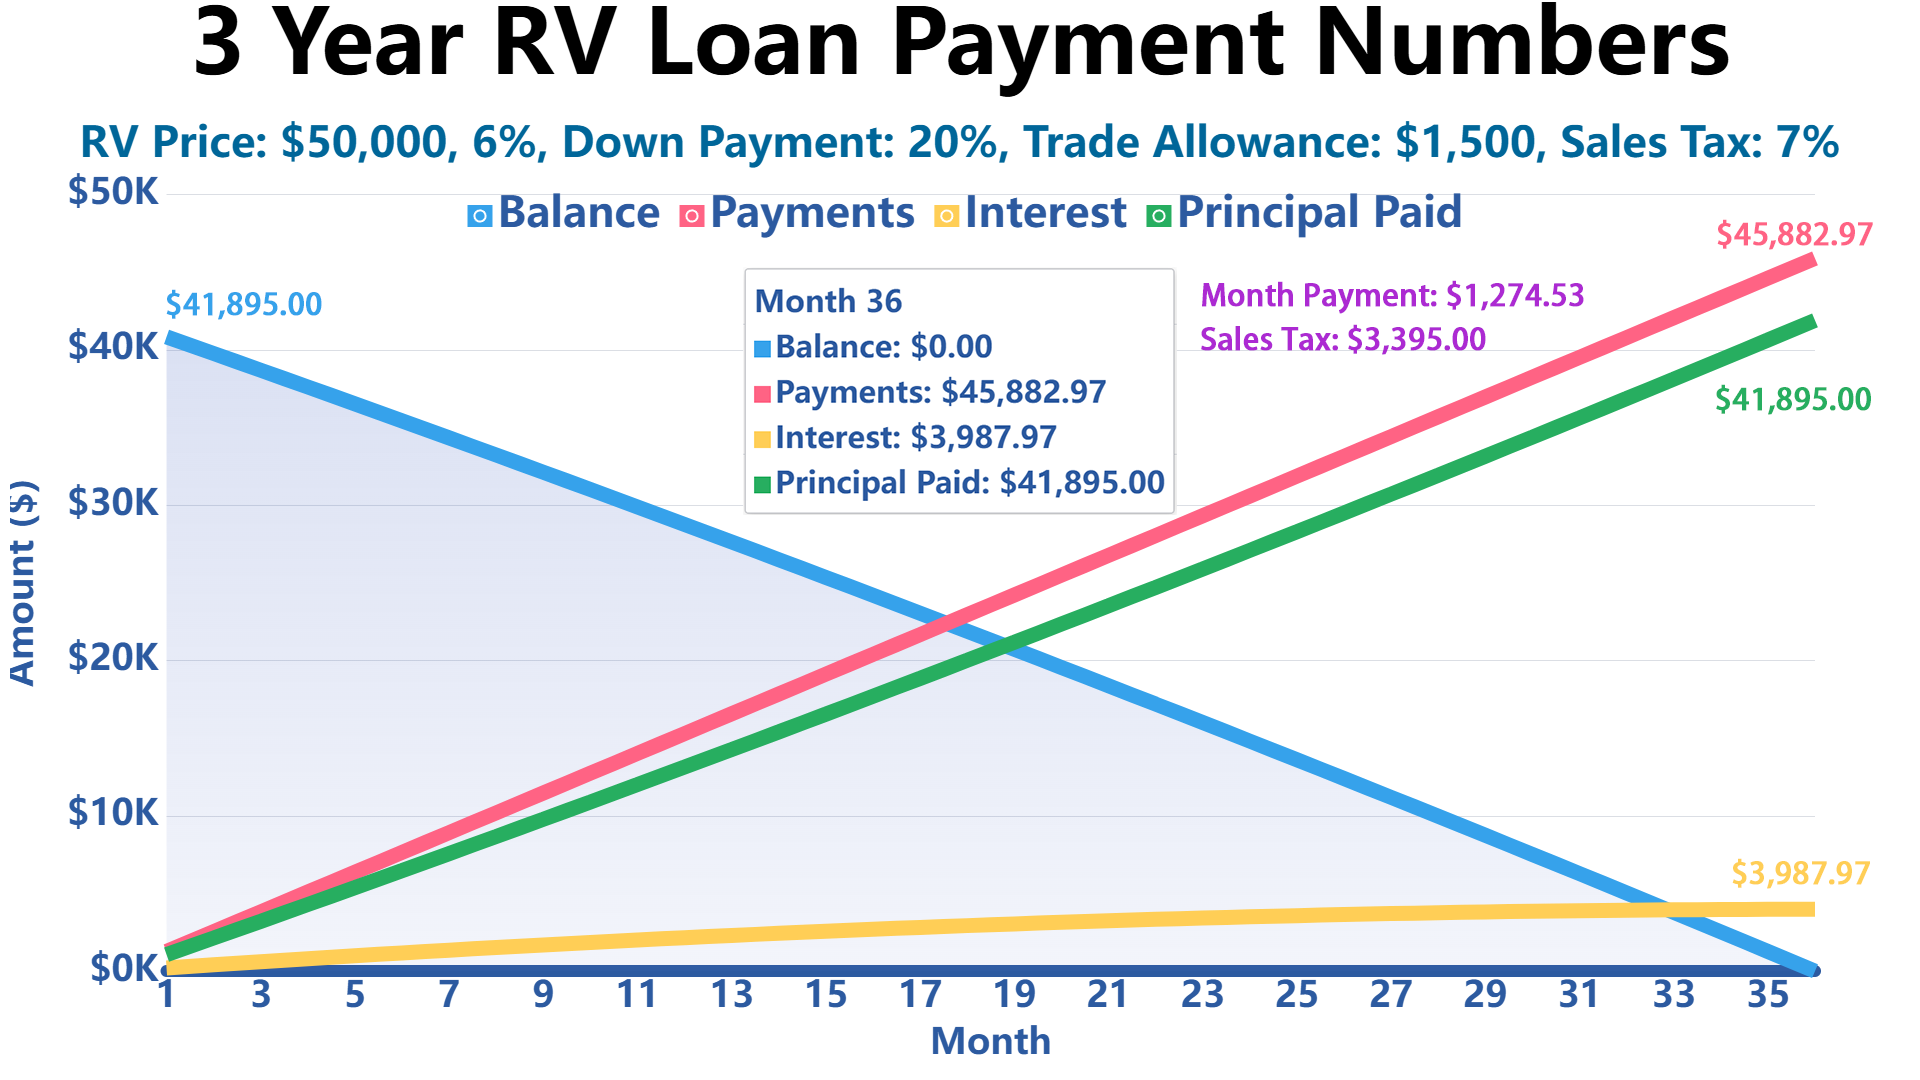
When you run an Rv Loan Calc, the key variables to get right are the loan amount, the annual rate, the term length, and whether you're rolling any fees into the principal. The trap people fall into is plugging in the sticker price instead of the actual financed amount. If the dealer offers $3,000 in incentives or you negotiate the price down, that changes your P value and therefore your monthly payment in a non-linear way. Lower principal means less interest compounding over time, so the payment drops more than a simple proportional calculation would suggest. I ran into a specific issue last year with a client who was comparing quotes between a dealer-financed option and a credit union. The dealer quoted a $1,247 monthly payment on an 84-month term at 6.9%. My Rv Loan Calc showed roughly $1,231, a $16 difference that seemed negligible until I traced where it came from. The dealer had rolled a $2,400 documentation fee and a $600 NTE (National Trade Estimate) gap waiver into the loan balance, bumping the financed amount from $78,000 to $81,000. The payment difference wasn't the rate—it was the hidden principal. Once we stripped those fees out and recalculated at the same 6.9% over 84 months, the payment dropped to $1,203. That $44 monthly difference compounded to about $1,100 over the full term. Another nuance worth noting: prepayment penalties. Some RV loans, particularly through manufacturer captive lending arms like Thor or Winnebago finance, include clauses that charge a fee if you pay off the loan early or refinance within the first 24 to 36 months. This is rarely highlighted in the monthly payment number. A standard Rv Loan Calc won't factor this in because it's not part of the amortization schedule. You need to read the fine print on the promissory note. If you're planning to trade in the RV within three years, that prepayment penalty could easily erase any savings from a lower rate.
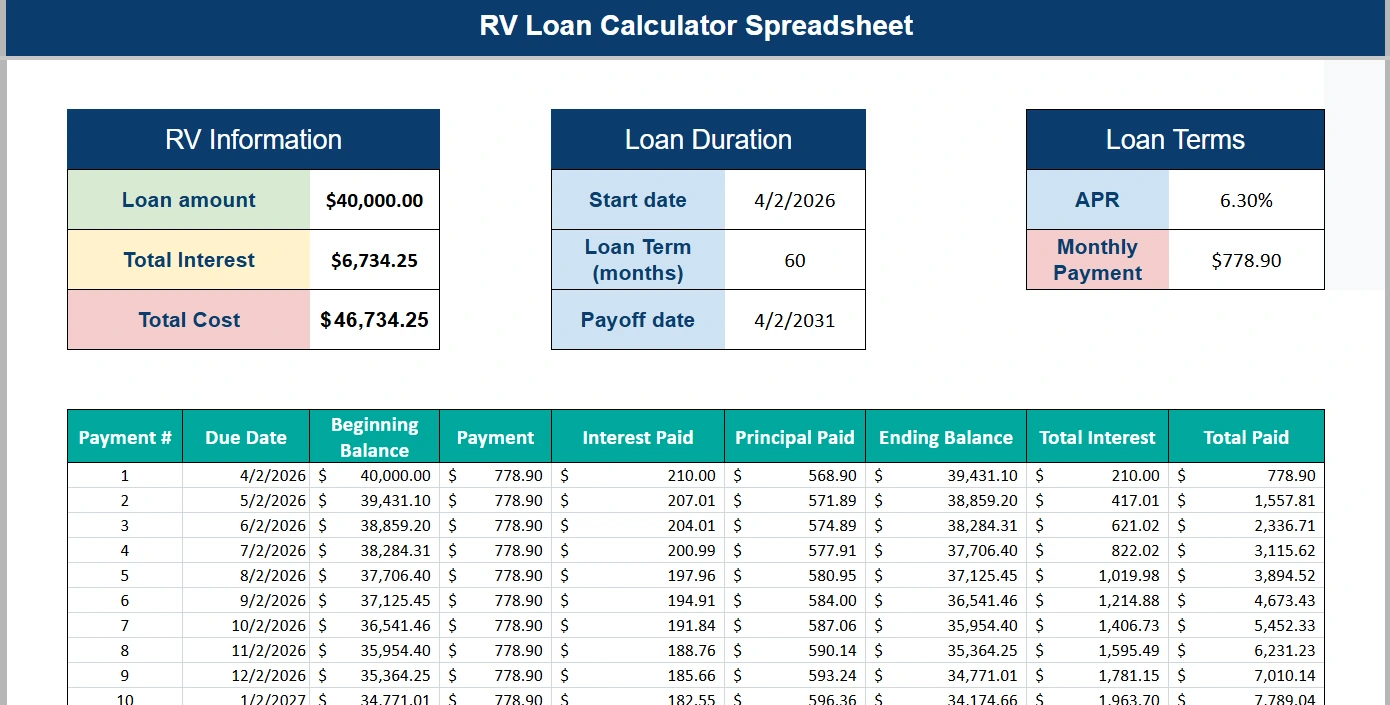
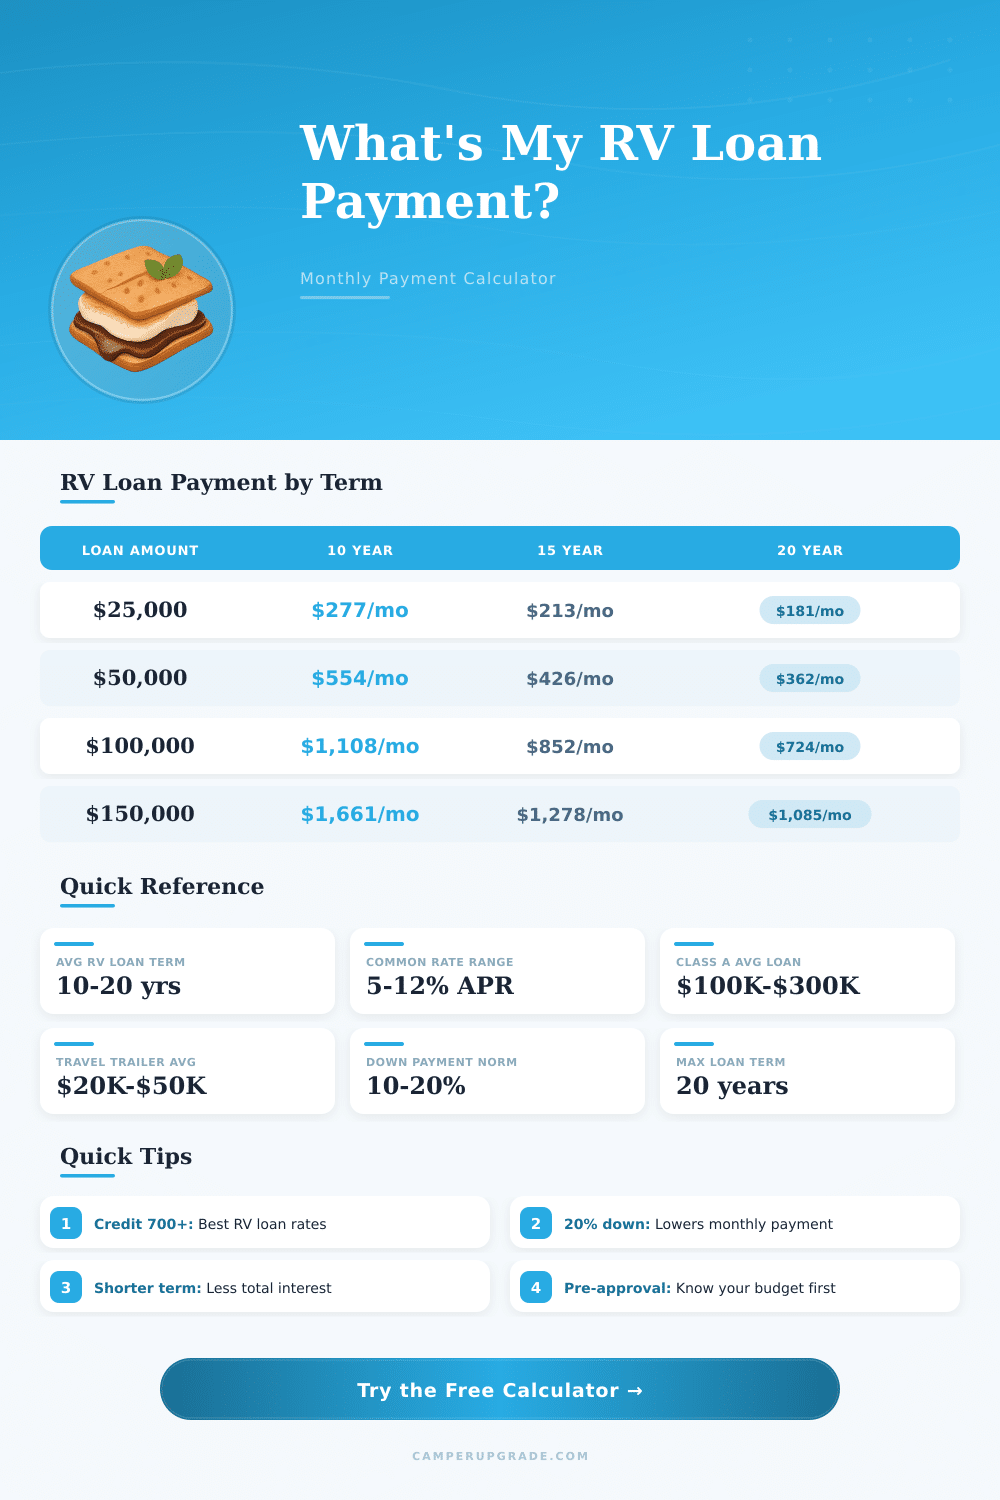
Term length is where most people make expensive mistakes. There's a strong temptation to stretch an RV loan to 120 or even 144 months because the monthly payment looks attractive. The math works against you in a brutal way. On a $90,000 loan at 7.5% over 120 months, you're paying roughly $1,837 monthly. Over the full term that's $220,440 paid against $90,000 borrowed—$130,440 in interest. Extend that to 144 months and the monthly drops to $1,514, but total interest climbs to $128,016. The payment feels better, but you're also carrying debt longer into a asset that depreciates faster than most people expect. Class A RVs typically lose 15 to 20 percent of their value in the first three years. You can easily end up upside-down on the loan while still making payments five years into a twelve-year term. Down payment expectations matter more for RVs than cars. Lenders generally want at least 10 to 20 percent down on an RV purchase. Going below 10 percent often triggers a higher rate or requires a co-signer, which simultaneously raises your cost and reduces your negotiating leverage. A $15,000 down payment on a $75,000 RV versus a $7,500 down payment might look like it only changes the monthly by a few hundred dollars, but it also shifts you from a sub-prime rate tier to a prime rate tier in many lender matrices. The combined effect can be $80 to $120 per month difference, not just from the reduced principal but from the rate improvement itself. If you want something more reliable than a generic web calculator, the best approach is to use Excel or Google Sheets with the PMT function. The formula =PMT(rate/12,term*12,-principal) gives you the exact base payment, and you can layer in additional rows for tax, registration, and insurance to get a true out-the-door monthly figure. This method also lets you create a full amortization schedule in about five minutes, which reveals exactly how much principal you're paying down each month versus how much goes to interest. That schedule becomes useful when you're negotiating—you can point to a specific month and show the lender where your equity position stands.
Get the Full Details

The main limitation of any Rv Loan Calc tool is that they don't account for state-specific taxes and fees. Registration costs, title fees, and sales tax vary wildly depending on where you live and where you register the RV. Some states tax the full purchase price, others tax only the portion financed, and a few have annual weight-based registration that adds hundreds to your monthly cost. A calculator can show you the loan payment, but it won't tell you whether your total monthly housing cost includes an extra $150 in state fees that a neighbor in the next county doesn't pay.