Figuring Out What You Actually Can Afford Before You Walk Into a Dealership
I keep seeing people bring up questions about RV payment estimates at forums and Facebook groups, and almost everyone is asking the same thing: what will my monthly payment look like? The short answer is it depends on the loan term, the interest rate your lender is willing to offer, and whether you put anything down. The long answer involves understanding how RV loans differ from car loans, why the sticker price isn't the whole story, and what happens when you actually sign the paperwork. I've been tracking this space for years, so I'll walk through the math and the gotchas. Most online calculators use the same basic formula. They take your total loan amount, divide the annual interest rate by twelve to get the monthly rate, then plug everything into an amortization equation. The formula looks like this: your monthly payment equals the principal times the monthly rate, divided by one minus one plus the monthly rate raised to the negative of the number of payments. That sounds complicated but it's just standard amortization math that has been used for decades. The tricky part is figuring out what numbers to plug in. Here's where people mess up. They look at the MSRP of the RV and put that in as the loan amount. The actual financed amount is lower because you usually put a down payment in, and sometimes you roll taxes and registration into the loan too. A calculator won't tell you that upfront — you have to do that arithmetic yourself before you enter the numbers. I had a guy once tell me his estimated payment was $900 a month on a $60,000 Class A coach, and when I asked what rate he was using, he said 7.5 percent. He had actually put only $5,000 down on a 120-month loan, which is a terrible deal by most standards. He hadn't realized that extending the term that far costs you thousands in extra interest even though the monthly payment looks manageable.
The Numbers You Actually Need to Gather
Before you run any estimate, collect these figures. The purchase price or listing price of the RV. Your down payment amount, which should ideally be at least ten to fifteen percent for a new motorhome or travel trailer. The interest rate your lender is quoting, which varies wildly depending on your credit score and whether it's a new or used rig. The loan term you're considering, typically ranging from thirty-six months to one hundred twenty months for RVs. Any fees the lender charges, like origination fees or documentation charges, which sometimes get added to the principal. I keep running into a specific edge case that almost no calculator accounts for. Some RV lenders still use pre-computed interest loans, especially on older or subprime products. With a pre-computed loan, the total interest is calculated upfront and added to the principal, then the whole thing is amortized over the term. This makes the monthly payment slightly higher than a standard amortizing loan would produce for the same numbers. I discovered this when I was helping a buddy shop around and two lenders gave me very similar monthly quotes on paper, but one was actually costing him about four hundred dollars more over the life of the loan because of how the interest was structured. Always ask whether the loan is fully amortizing or if it uses pre-computed interest.
Running a Real Example
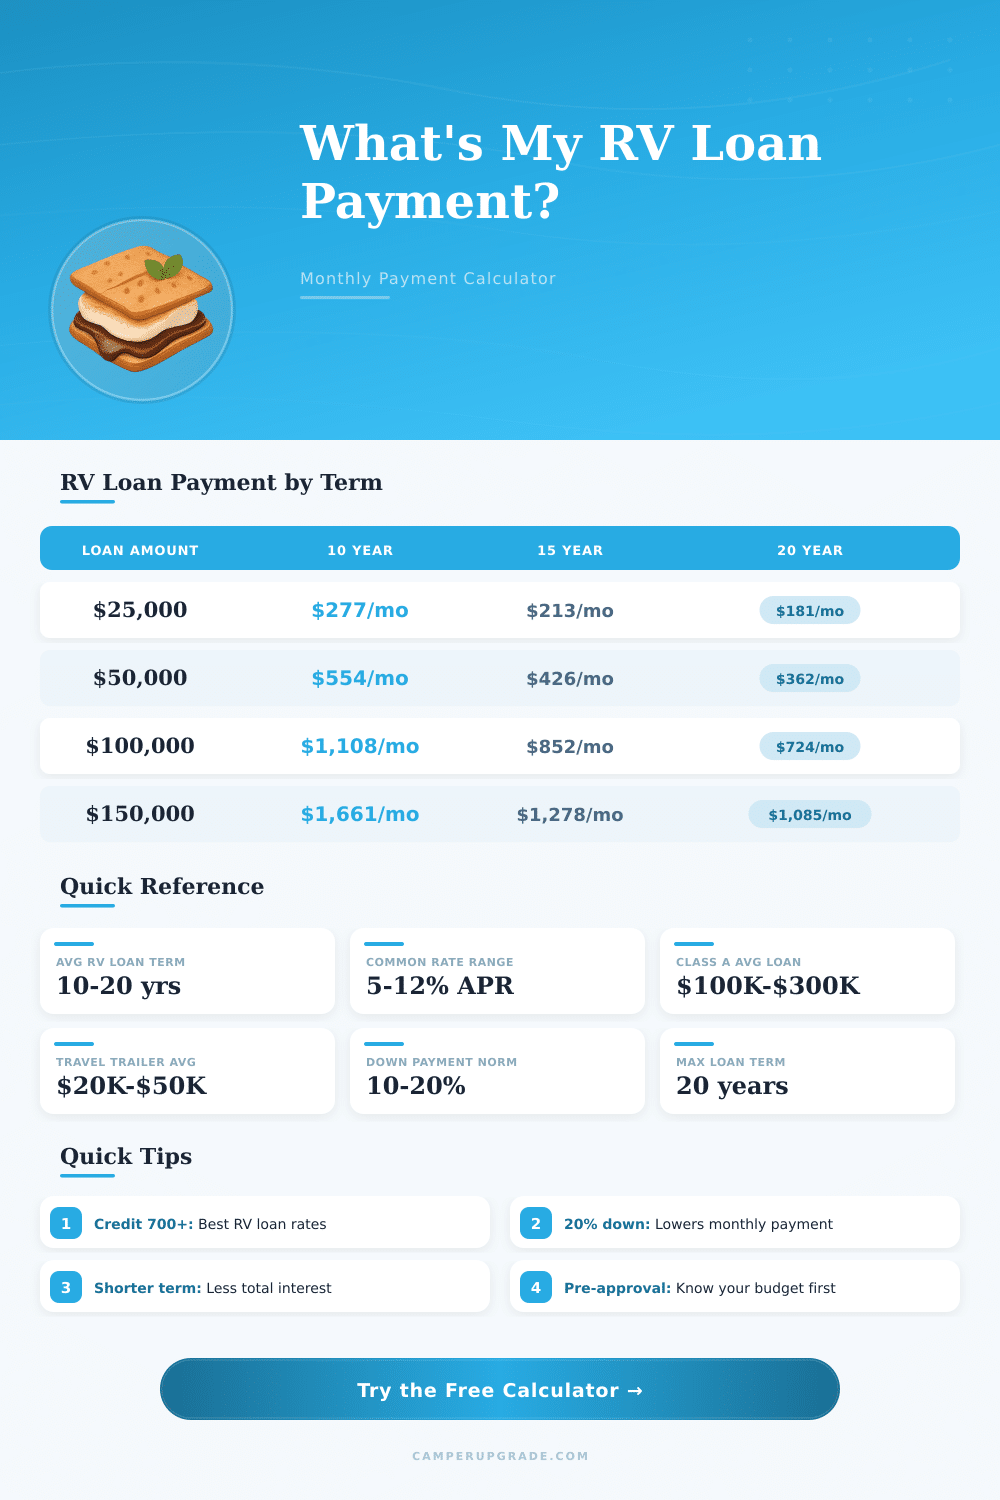
Let's say you're looking at a used fifth wheel listed at forty-two thousand dollars. You have eight thousand to put down, leaving a principal of thirty-four thousand. The lender quotes you six point seven five percent annual interest on a sixty-zero-month term. Your monthly rate is zero point zero six seven five divided by twelve, which equals zero point zero five six two five. Plugging that into the formula gives you a payment of roughly six hundred and twelve dollars per month. That's the mathematical answer. The practical answer is that you should expect to add property tax, insurance, and possibly a dealer prep fee to your actual out-of-pocket cost each month. Now here's something most people don't consider. If you extend that same loan to ninety-six months, your payment drops to about four hundred and seventy-two dollars. It feels better month to month, but you're paying over two thousand dollars more in total interest, and you'll be upside down on the loan for much longer. RVs depreciate faster than most people expect in the first three years, so a longer term means you owe more than the RV is worth for a significant stretch of the loan. That becomes a real problem if you need to sell or if the RV gets damaged and the insurance payout doesn't cover the remaining balance.
Get the Full Details

What Most Estimators Leave Out
Most free calculators online stop at the basic principal and interest number. They don't factor in property tax, which varies by state and can add fifty to two hundred dollars a month depending on where you register the rig. They don't include insurance, which for a full-time or frequently used RV can run anywhere from eighty to two hundred and fifty a month depending on coverage and claims history. They ignore the fact that many RV loans have balloon payment structures or require a large final payment if you're financing through certain channels. And they almost never account for the gap between the quoted rate and the rate you actually qualify for, which can swing by a full percentage point or more depending on credit history and debt-to-income ratio. I've also noticed that some calculators treat the RV like a primary residence for tax purposes when it isn't. If you're using an RV for business or rental income, the interest might be deductible, but that depends on how you're using the vehicle and what your accountant says. Don't assume the calculator will tell you that. It won't.
When an Estimator Actually Helps
The tool is useful for narrowing your search range before you spend time test driving rigs you can't afford. If you know your comfortable monthly payment is around six hundred dollars, you can filter listings accordingly and avoid wasting time on anything that requires a payment well above that. It also helps you compare different term lengths quickly so you can see the tradeoff between lower monthly cost and higher total interest. That's about the extent of its usefulness. It's not a substitute for a real pre-approval. Lenders will run your actual credit profile and give you a firm rate, and that rate might be several percentage points different from the generic estimate you saw online. I've seen people get turned down or offered rates five percent higher than the estimator showed because they had recent collections or a high credit card utilization ratio that the calculator had no way of knowing about.
Alternatives to Consider
If you're shopping for an RV and want something more accurate than a generic estimator, ask your credit union or local bank for a pre-qualification first. They'll give you a real rate range based on a soft credit pull, and that will be closer to what you'll actually get. If you're self-employed or have non-traditional income, some specialty RV lenders work with different documentation methods, so a standard estimator won't reflect your situation accurately anyway. In those cases, talking to a broker who understands RV lending is more useful than running numbers through a website. There's also the option of purchasing an RV outright if your savings allow it. The payment calculation disappears entirely, and you avoid depreciation risk plus interest costs. I know that's not realistic for most people buying a thousand dollar or larger rig, but it's worth mentioning because the best way to estimate a payment you don't have to make is to just not have one.
A Few More Practical Notes
If your credit score is below six hundred and eighty, expect rates in the eight to twelve percent range on most RV loans. That's just the current market. Rates have been higher than they were a few years ago, so any estimator you find that's showing five percent on a new RV loan is probably outdated or showing promotional rates that require excellent credit and a large down payment. Check the date on any calculator you use, and verify the rate against what actual lenders are quoting right now. Also, remember that the down payment doesn't just reduce your principal. It also affects whether you qualify for certain loan programs. Some lenders require at least fifteen percent down on used RVs over a certain age, and dropping below that threshold can push you into a different product category with worse terms. I've seen this happen repeatedly. People bring in estimates showing a comfortable payment, then find out they don't qualify for the rate they were counting on because their down payment was too small. The bottom line is that a Rv Payment Estimator gives you a starting point, not a final answer. Use it to narrow your search, then get pre-approved by a real lender before you start seriously shopping. The difference between an estimate and an actual quote can be hundreds of dollars per month, and that gap matters a lot when you're committing to a payment for four or five years.