What a Personal Financial Statement Actually Is
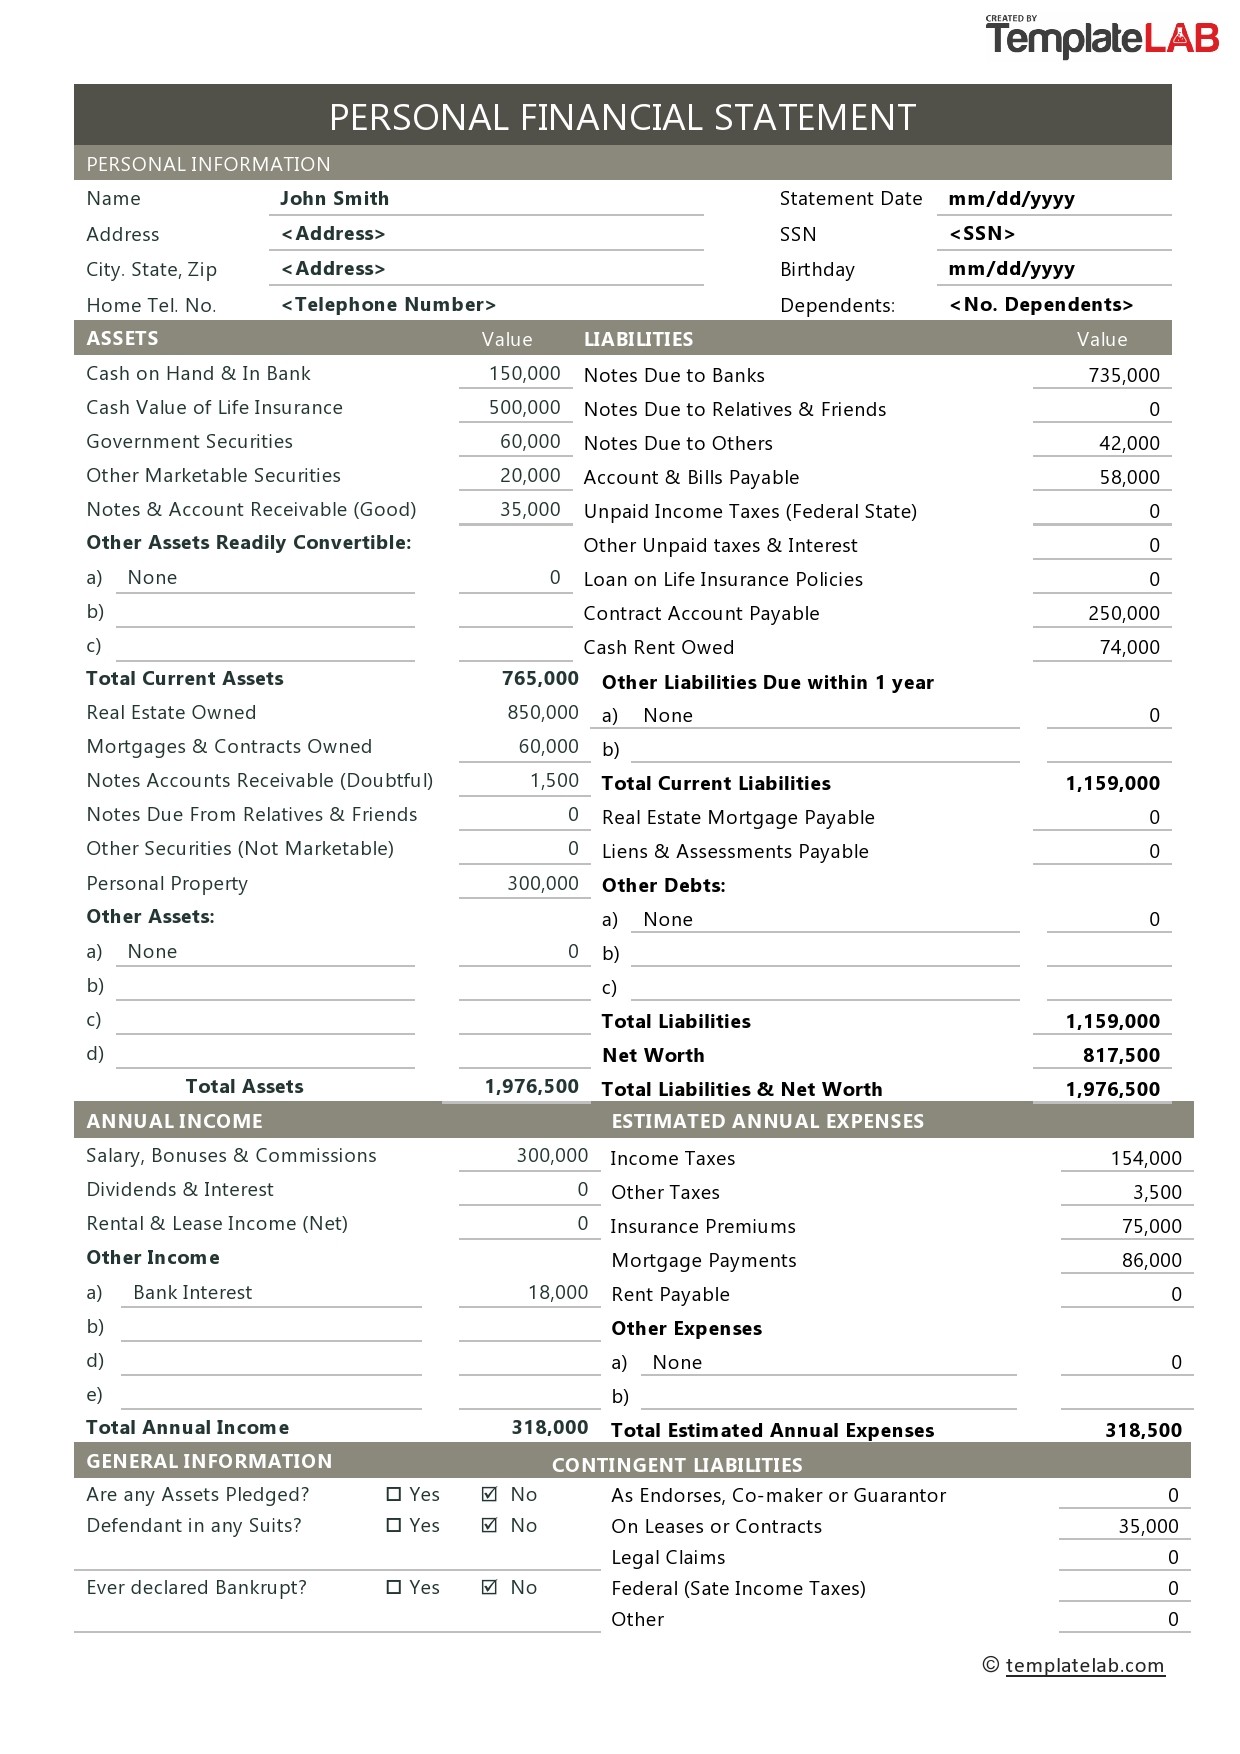
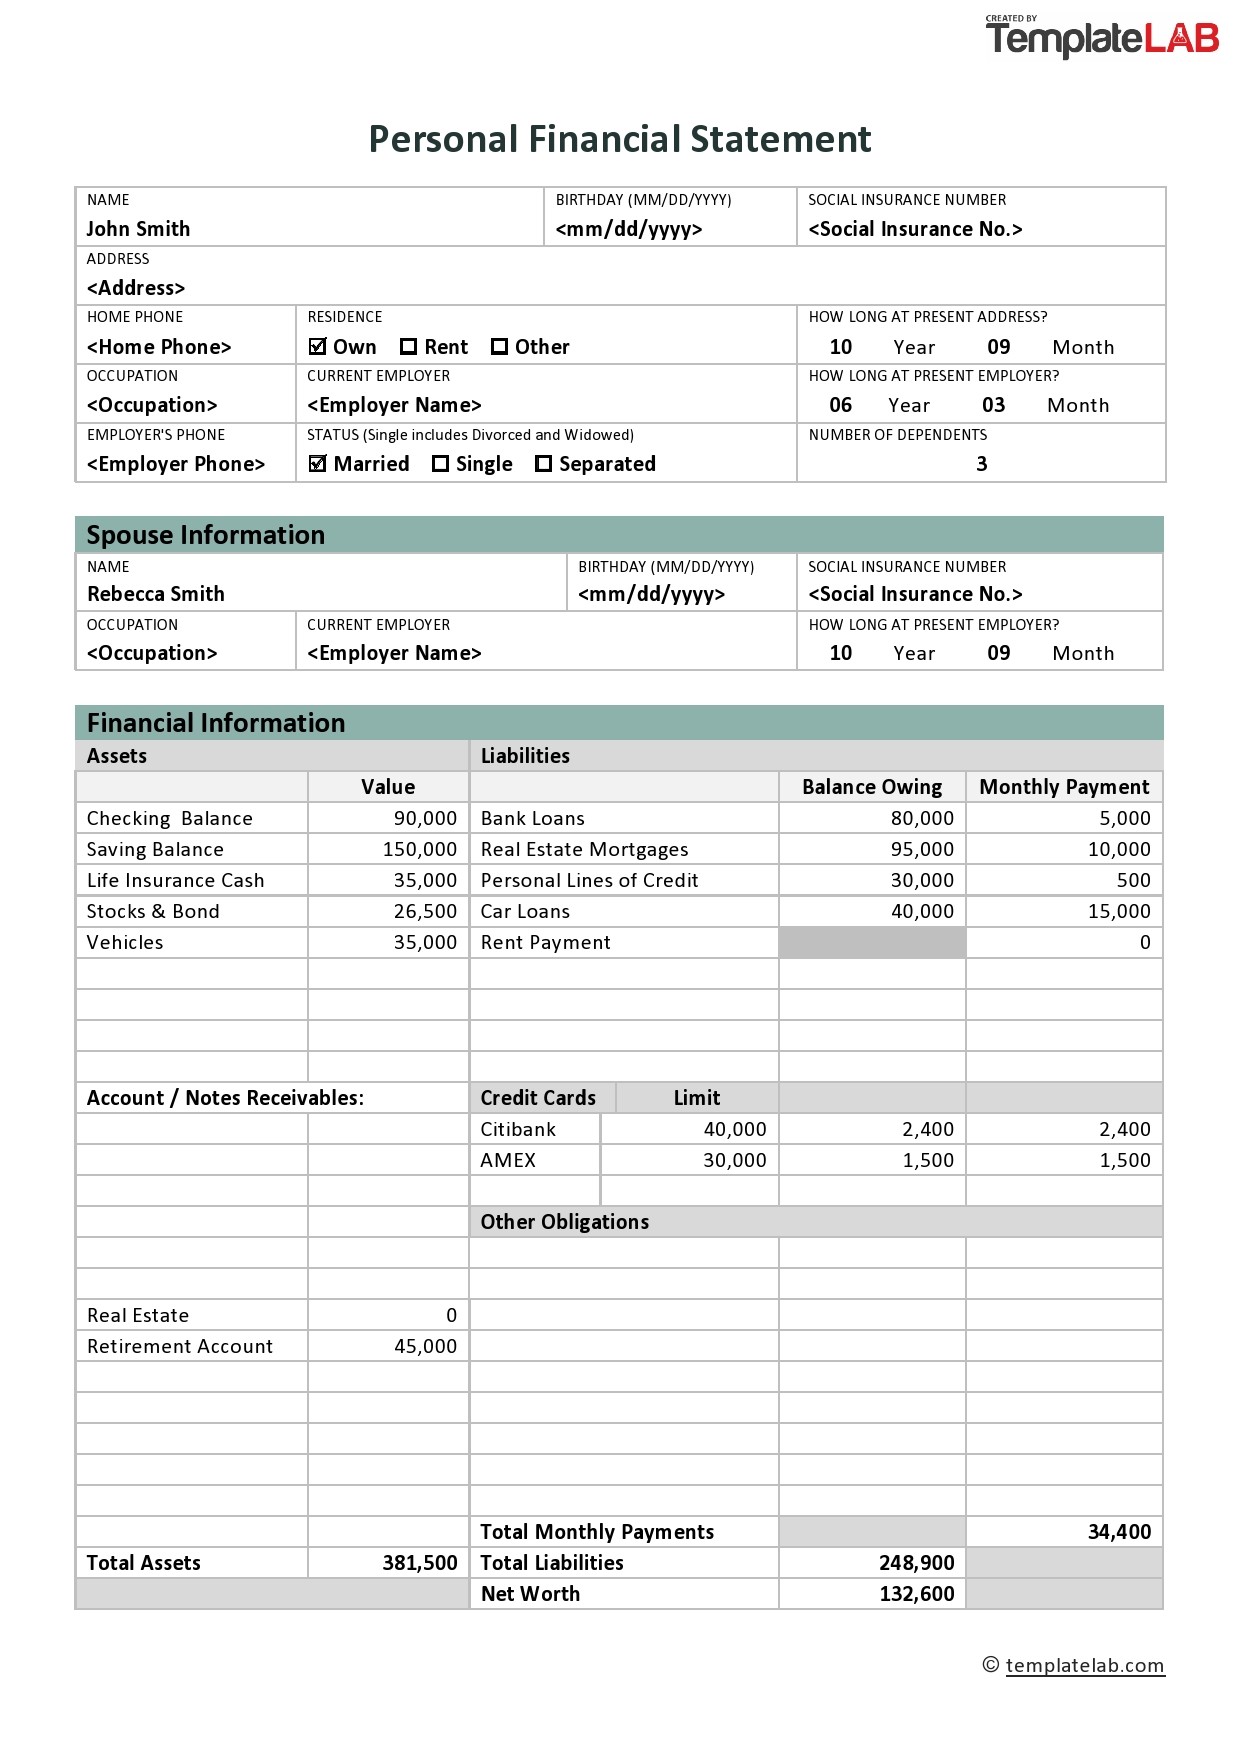
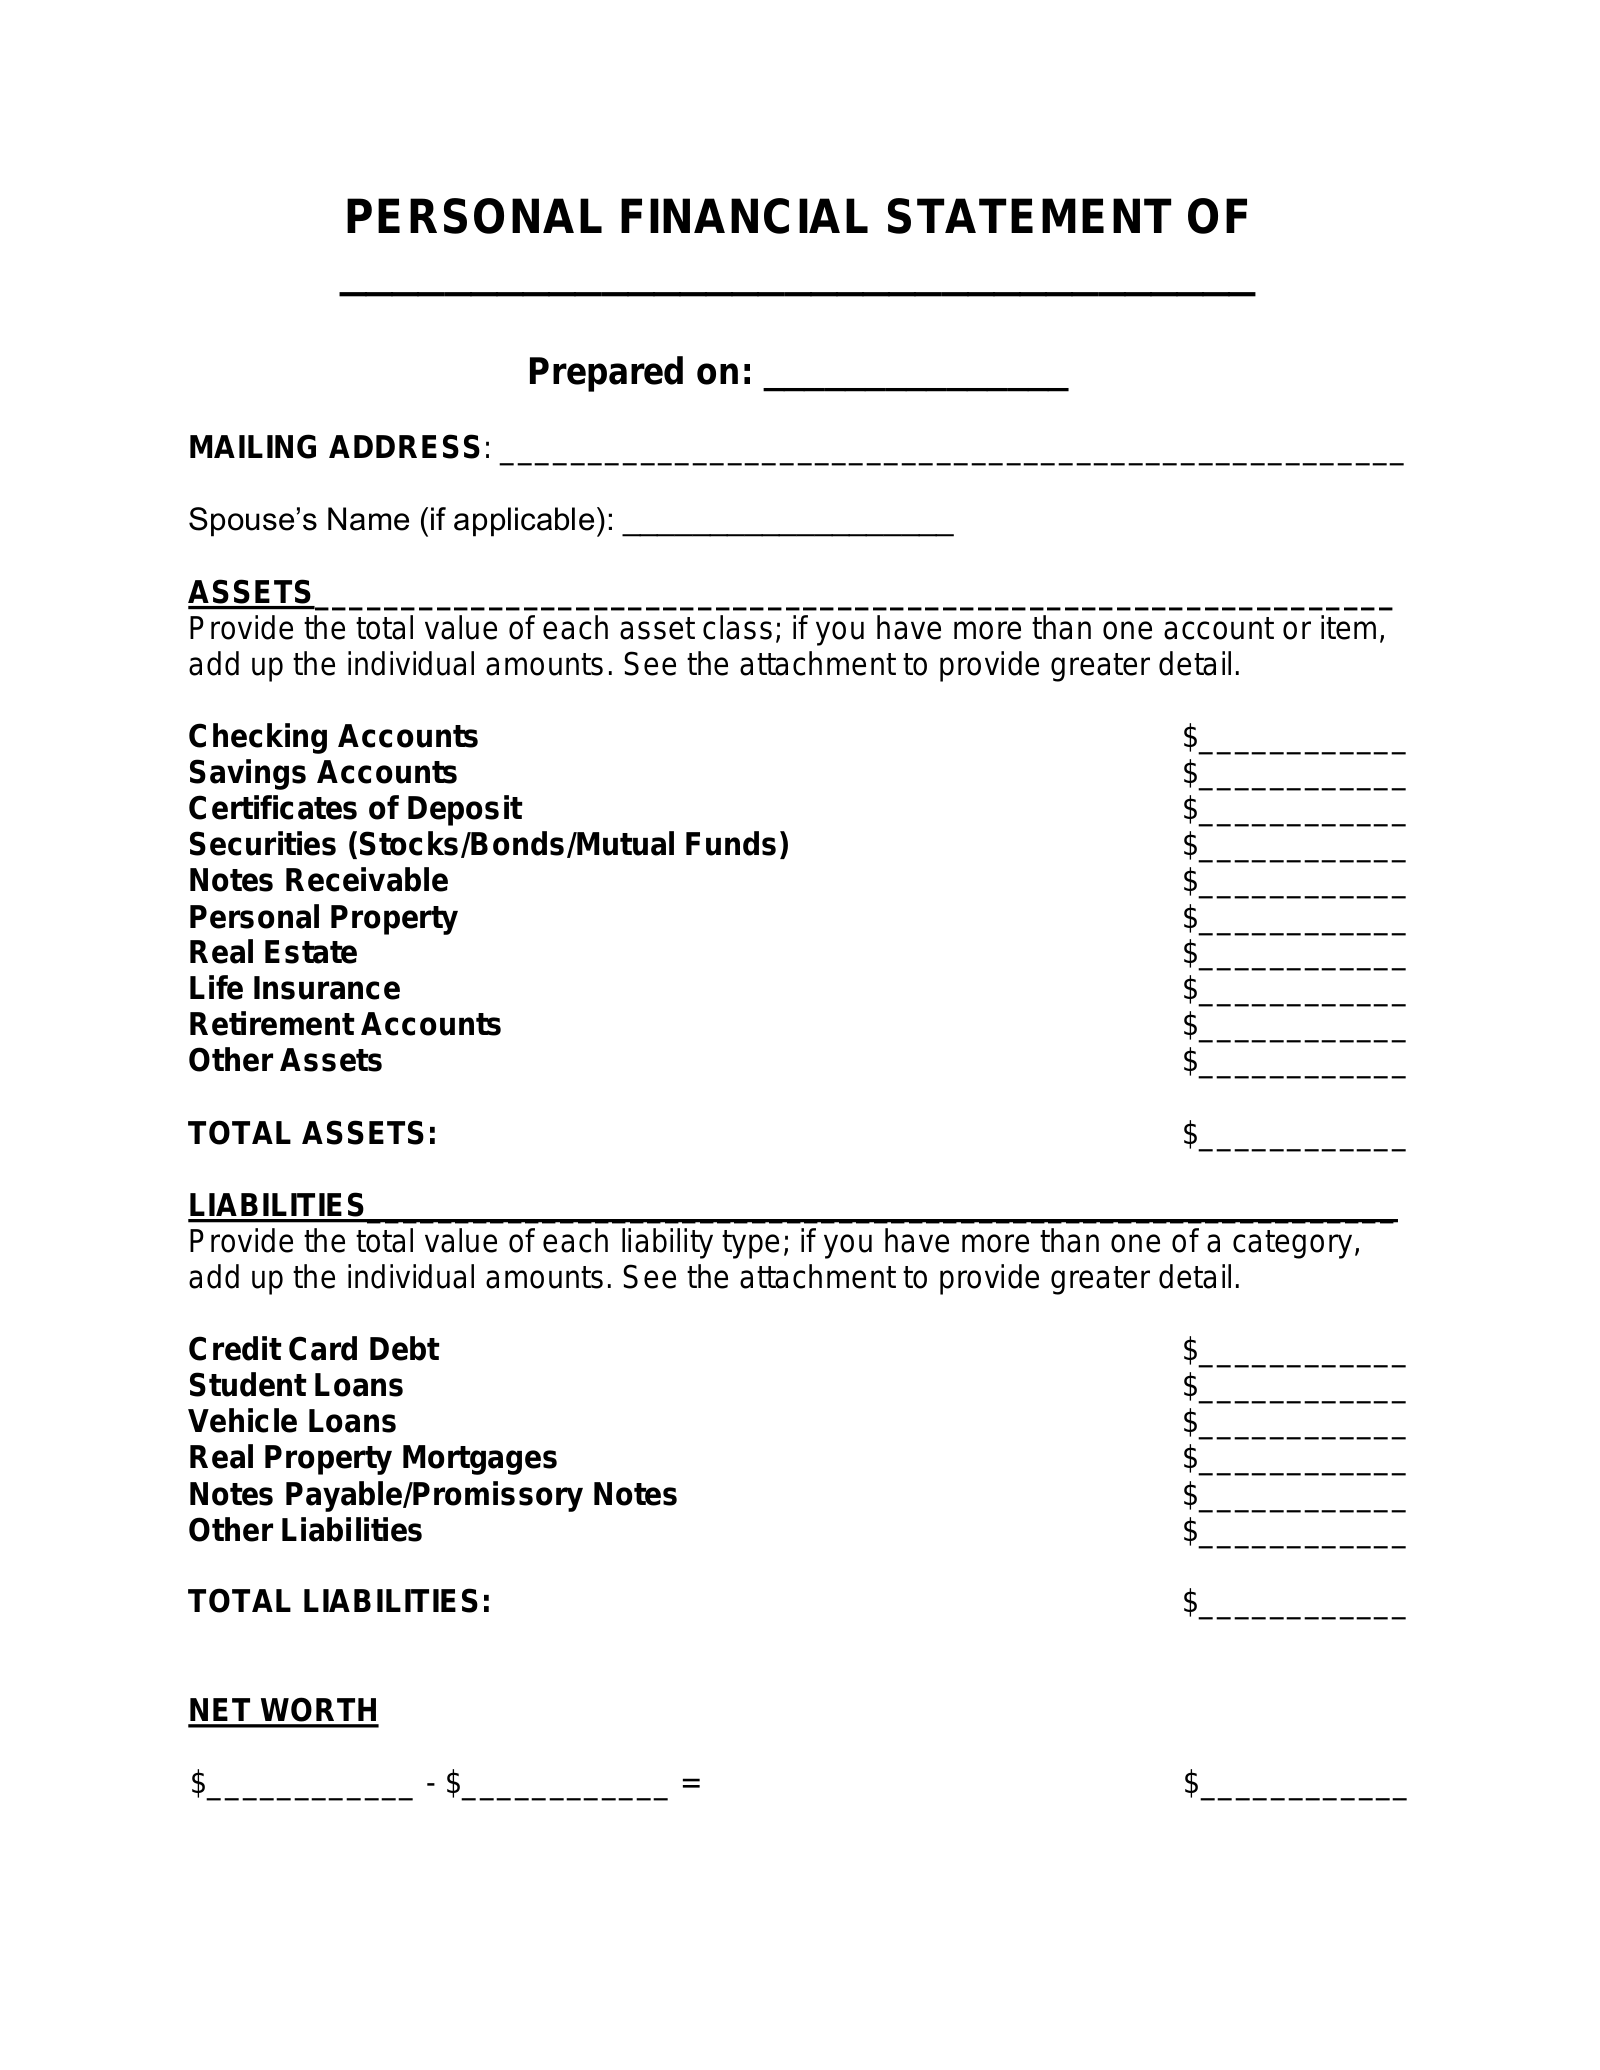
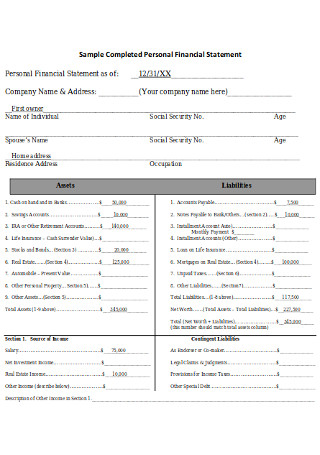
A personal financial statement is simply a snapshot of where you stand financially at a given moment. It lists your assets, your liabilities, and the difference between them—your net worth. Lenders use these when you apply for a loan, buy a house, or start a business. They want to know whether you can repay money and how much skin you have in the game. The document is straightforward on paper but gets messy the moment you try to fill it out correctly. Start with the assets side. List everything you own that has value: cash accounts, checking and savings balances, certificates of deposit, retirement accounts like 401(k)s and IRAs, the current market value of stocks and mutual funds, the fair market value of your primary residence, vehicles, jewelry, art, and any business ownership interests. Do not list personal items like furniture or clothing unless they are high-value collectibles that actually have a liquid market. Next, list your liabilities. Mortgage balances on all properties, home equity lines of credit, auto loans, student loans, credit card balances, personal loans, and any outstanding business debt. Use the current payoff amounts, not the original loan amounts. Credit card balances should reflect what you actually owe as of your statement date, not what you plan to pay next month.
Subtract total liabilities from total assets. The result is your net worth. That is the bottom line a lender cares about most. I typically format this in a two-column layout because it is the standard most banks and credit unions expect. Left column for assets, right column for liabilities, with clear subtotals and a final net worth line. Some lenders provide their own form, but having a clean template in your own spreadsheet means you are never stuck waiting on a PDF that does not match your situation.
Practical Issues I Have Run Into
One specific problem I dealt with recently involved valuing a Roth IRA for a commercial loan application. The account had been open for twelve years and had grown significantly from contributions and market gains. The lender's underwriter initially wanted to see the account at its original contribution amount rather than current fair market value. This is a common point of confusion. Roth IRA contributions are always listed at what you put in, but the earnings portion—the growth—is listed at current value. I resolved this by pulling a current account statement from the custodian, highlighting the contributions section and the earnings section separately, and attaching both to the PFS. The underwriter accepted it once they could see the breakdown. The workaround here is simple: always pull a fresh account statement that shows contribution history separately from earnings, and annotate which line goes where on your form. Another edge case involved a jointly owned rental property where the mortgage was in only one spouse's name. The asset should be listed at 50% of the current market value since ownership was split, but the liability should be listed at 100% of the mortgage balance because one person was solely responsible for repayment. Listing the liability at 50% would have inflated the net worth artificially and raised a red flag during underwriting. I learned this the hard way after a second submission was flagged. The fix was just to be explicit about ownership percentages and liability responsibility on the document itself, with a brief notation next to each item.
Get the Full Details
Common Mistakes That Sink Applications
The biggest mistake people make is using outdated numbers. A balance from six months ago looks nothing like your current situation. Pull everything as of the same date. If your bank statement is from the 15th and your credit card balance is from the 28th, you are introducing noise that underwriters will notice. Another frequent error is overstating asset values. Listing your home at what you think it might sell for in a seller's market rather than at a conservative estimate based on recent comparable sales is a quick way to lose credibility. Use public records or a recent appraisal, not Zillow estimates. Zillow's algorithm has no idea about the condition of your roof or the neighborhood noise problem that makes buyers walk away. People also forget about contingent liabilities. If you have co-signed a loan for a family member, that debt belongs on your statement. It is a real obligation even if the primary borrower is current. Underwriters will ask about co-signatures, and omitting them looks like you are hiding something.
Sample Personal Financial Statement Best Practices
Use a single spreadsheet or a clean one-page template. Keep it to one page if possible. Lenders review dozens of these daily, and a cluttered two-page document with merged cells and inconsistent formatting slows them down and increases the chance of errors. Standardize your number formatting. Use commas for thousands, two decimal places for all currency, and bold your subtotals. Keep it readable. Date everything. Put the as-of date prominently at the top. Include the date next to each account balance so the reader knows how fresh the data is. Underwriters will reject anything older than thirty days without explanation. Organize assets in order of liquidity. Cash and equivalents first, then investments, then real estate, then personal property. This is the convention lenders expect and it makes verification faster. Same with liabilities: shortest-term debt first, longest-term last. Credit cards, then auto loans, then mortgages.
Attach supporting documentation. A PFS without backup is just a claim. Bank statements, brokerage statements, mortgage payoff letters, and vehicle titles should be available to submit alongside the form. Most lenders will ask for these within 48 hours of application, so having them ready prevents delays.
Where This Method Breaks Down
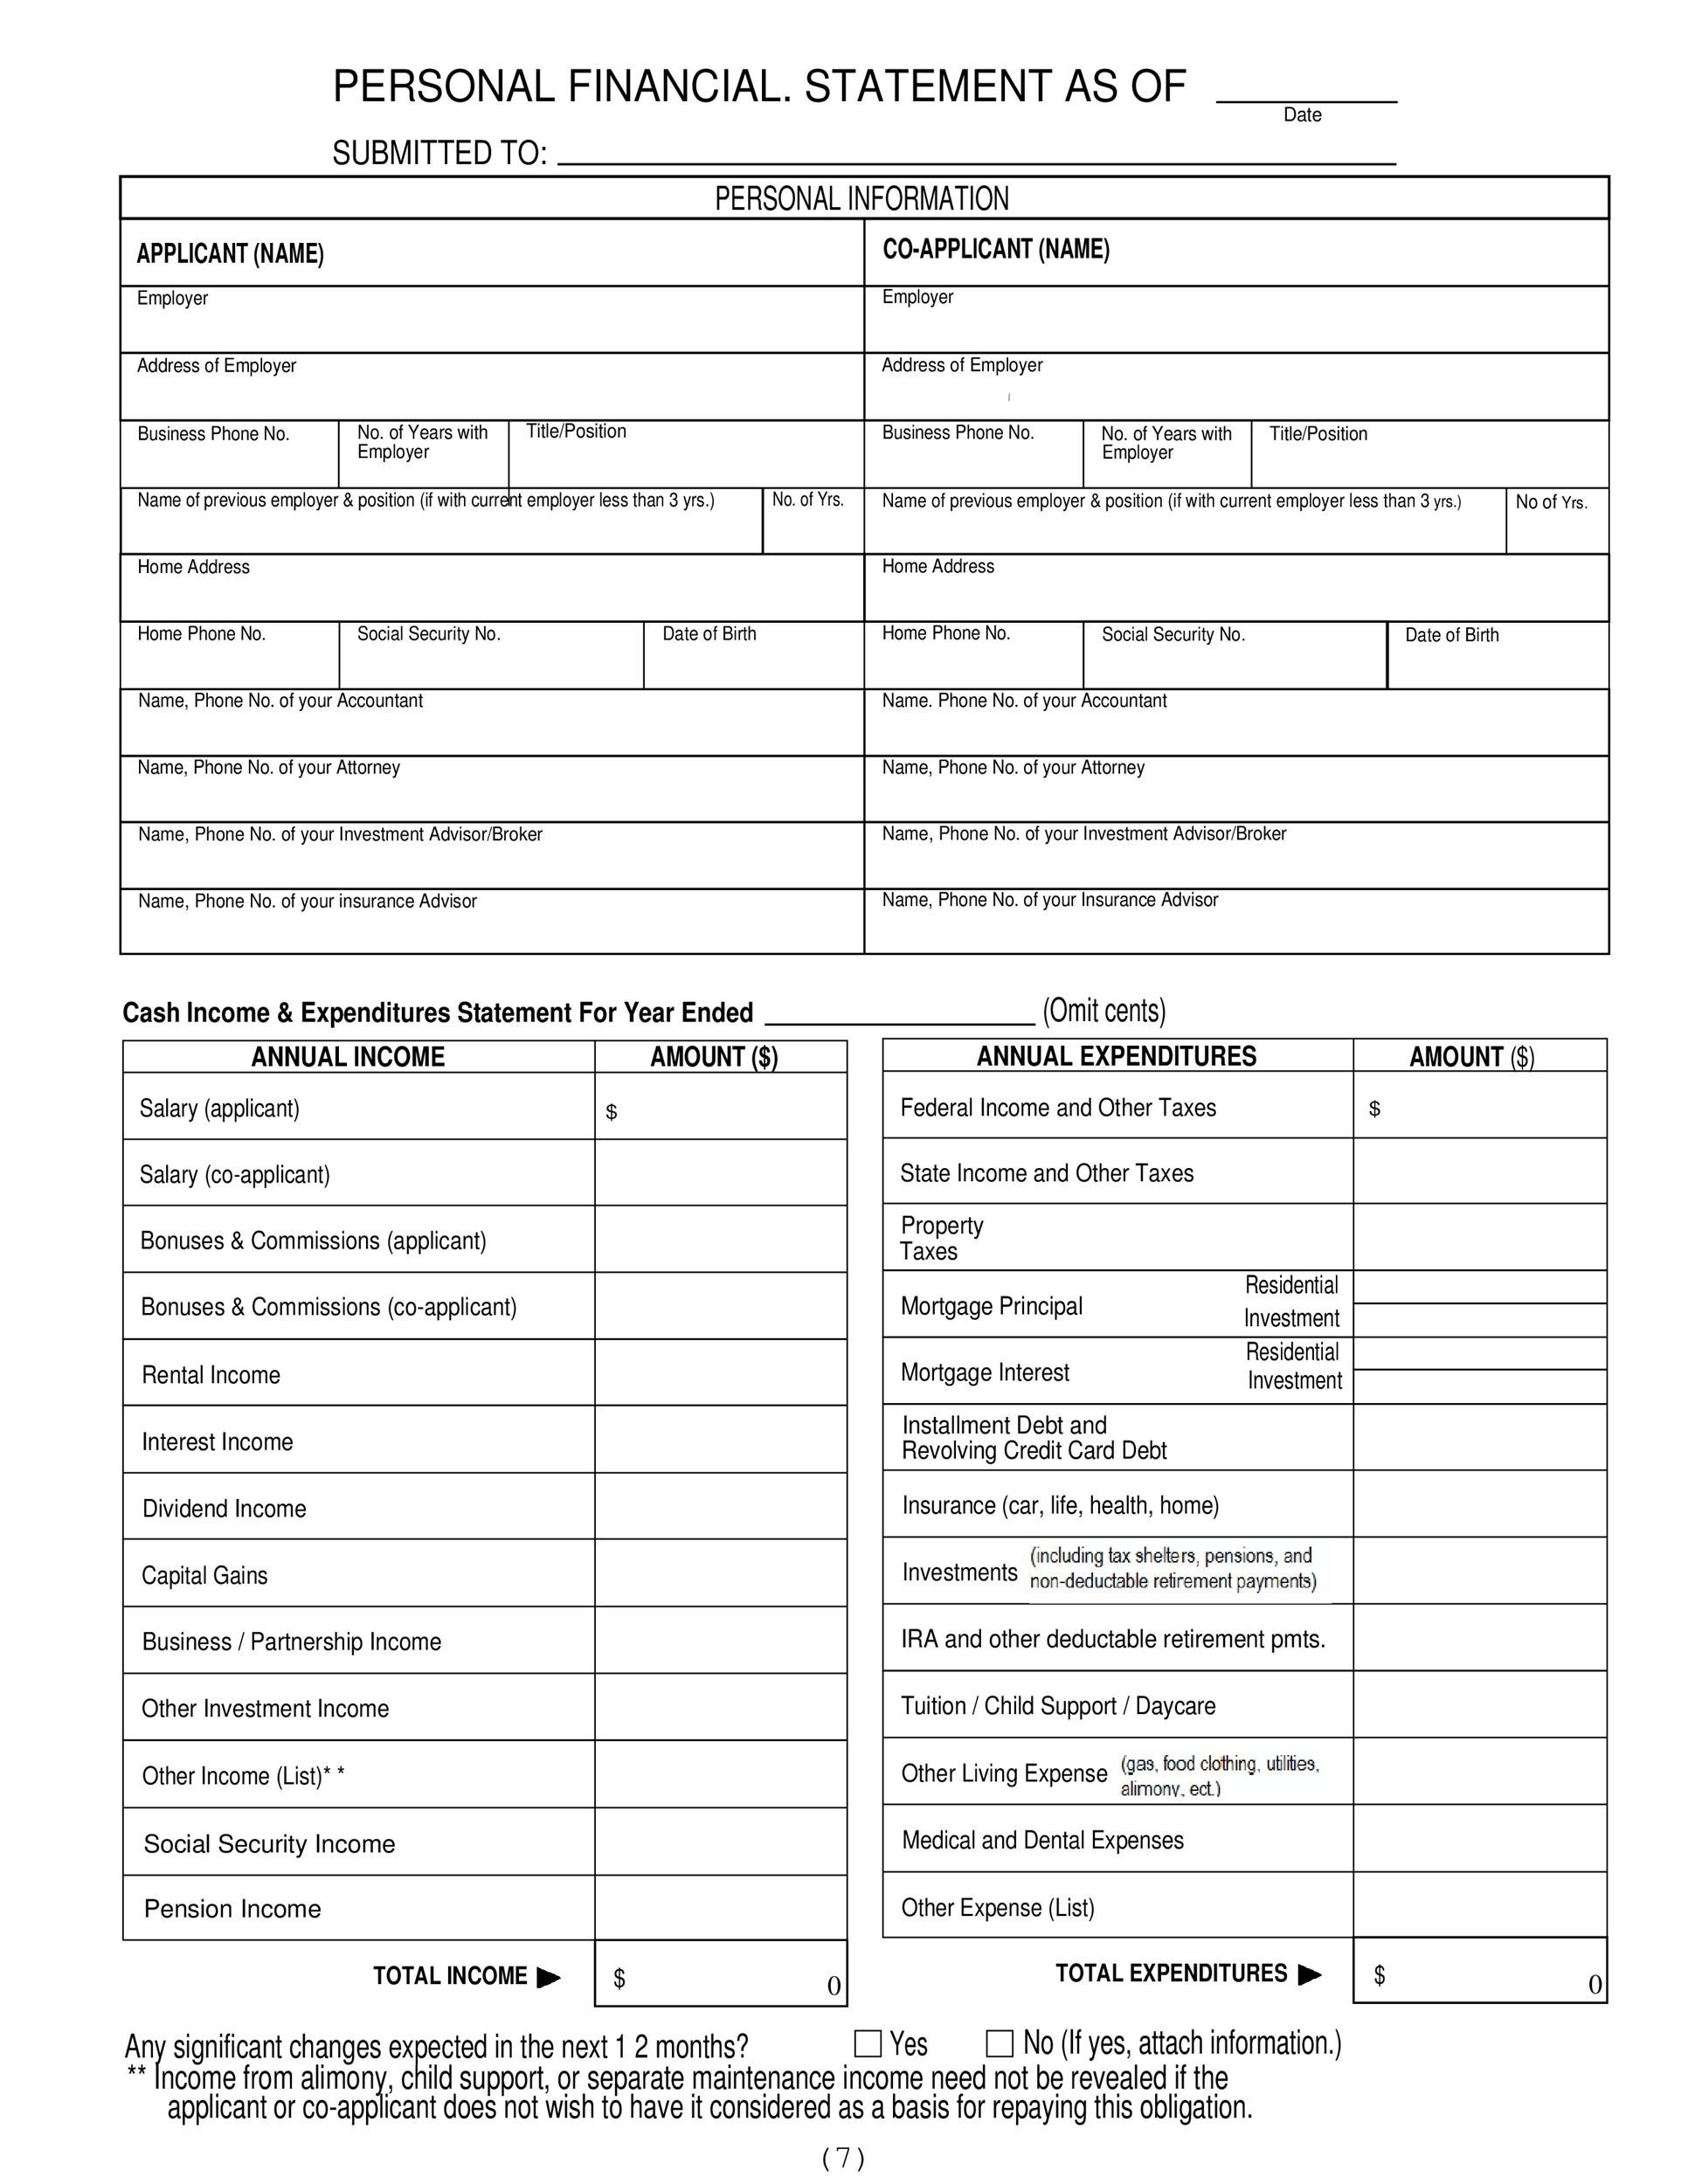
A personal financial statement works well for standard consumer lending, small business loans, and rental applications. It does not work well when your financial situation is complex. If you own multiple businesses, have cross-collateralized loans, hold assets in trusts, or deal with international accounts, a single-page PFS will miss important details. In those cases, you need a full financial disclosure package that includes additional schedules, trust documents, and business financials. The PFS becomes a summary, not the complete picture. The statement also loses relevance when income stability is the real question. A lender might see strong net worth but weak cash flow and still deny a loan. The PFS answers "what do you own," not "can you pay me back." For that, you need profit and loss statements, tax returns, and bank statements showing consistent deposits. Use the PFS as one piece of a broader financial profile, not the whole thing. If you are self-employed with irregular income, the PFS will show you as healthier than you might actually be on a month-to-month basis. High asset values can mask low monthly cash flow. Underwriters in that scenario will look harder at your tax returns and year-to-date profit and loss, not just your balance sheet snapshot.
What to Do if You Need a Template
The SBA provides a standard Personal Financial Statement (Form 413) that is widely accepted by lenders across the United States. It covers the essentials and is the default form for most small business loan applications. Banks and credit unions often have their own versions that are similar but not identical. Always confirm which form your lender prefers before spending time on a custom template. You can find the SBA Form 413 on the SBA website at sba.gov/forms. Most state licensing boards and professional organizations also publish sample forms you can use as reference. The exact format matters less than the accuracy of the numbers and the completeness of the disclosure. I keep a master spreadsheet with all my account balances, current mortgage payoffs, and property valuations updated monthly. When a PFS is needed, I pull from that master file rather than trying to gather information from scratch. This cuts the preparation time from about an hour down to roughly ten minutes, and it reduces the chance of leaving an account off the list. The initial setup takes longer, maybe an afternoon, but it pays off every time a lender asks for documentation.
The key takeaway is that a Sample Personal Financial Statement is not a theoretical exercise. It is a practical document that lenders scrutinize closely, and small inaccuracies can delay or derail an application. Get the numbers right, date them properly, attach proof, and understand what the document can and cannot tell a lender about your financial situation.