Setting Up a Functional P&L That Doesn't Break in Two Weeks
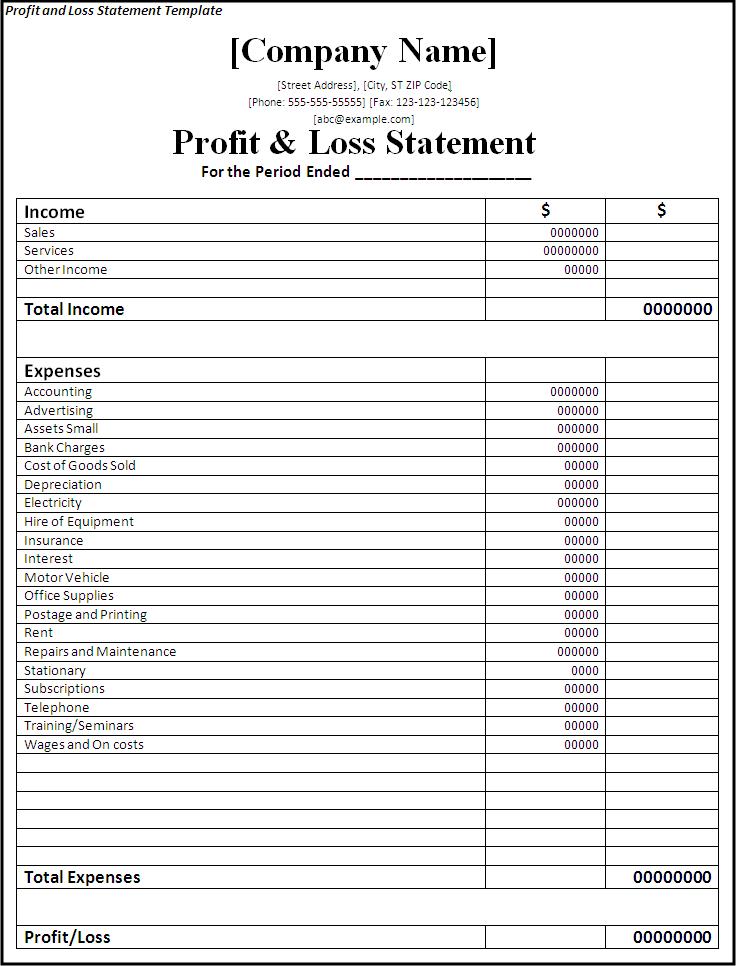
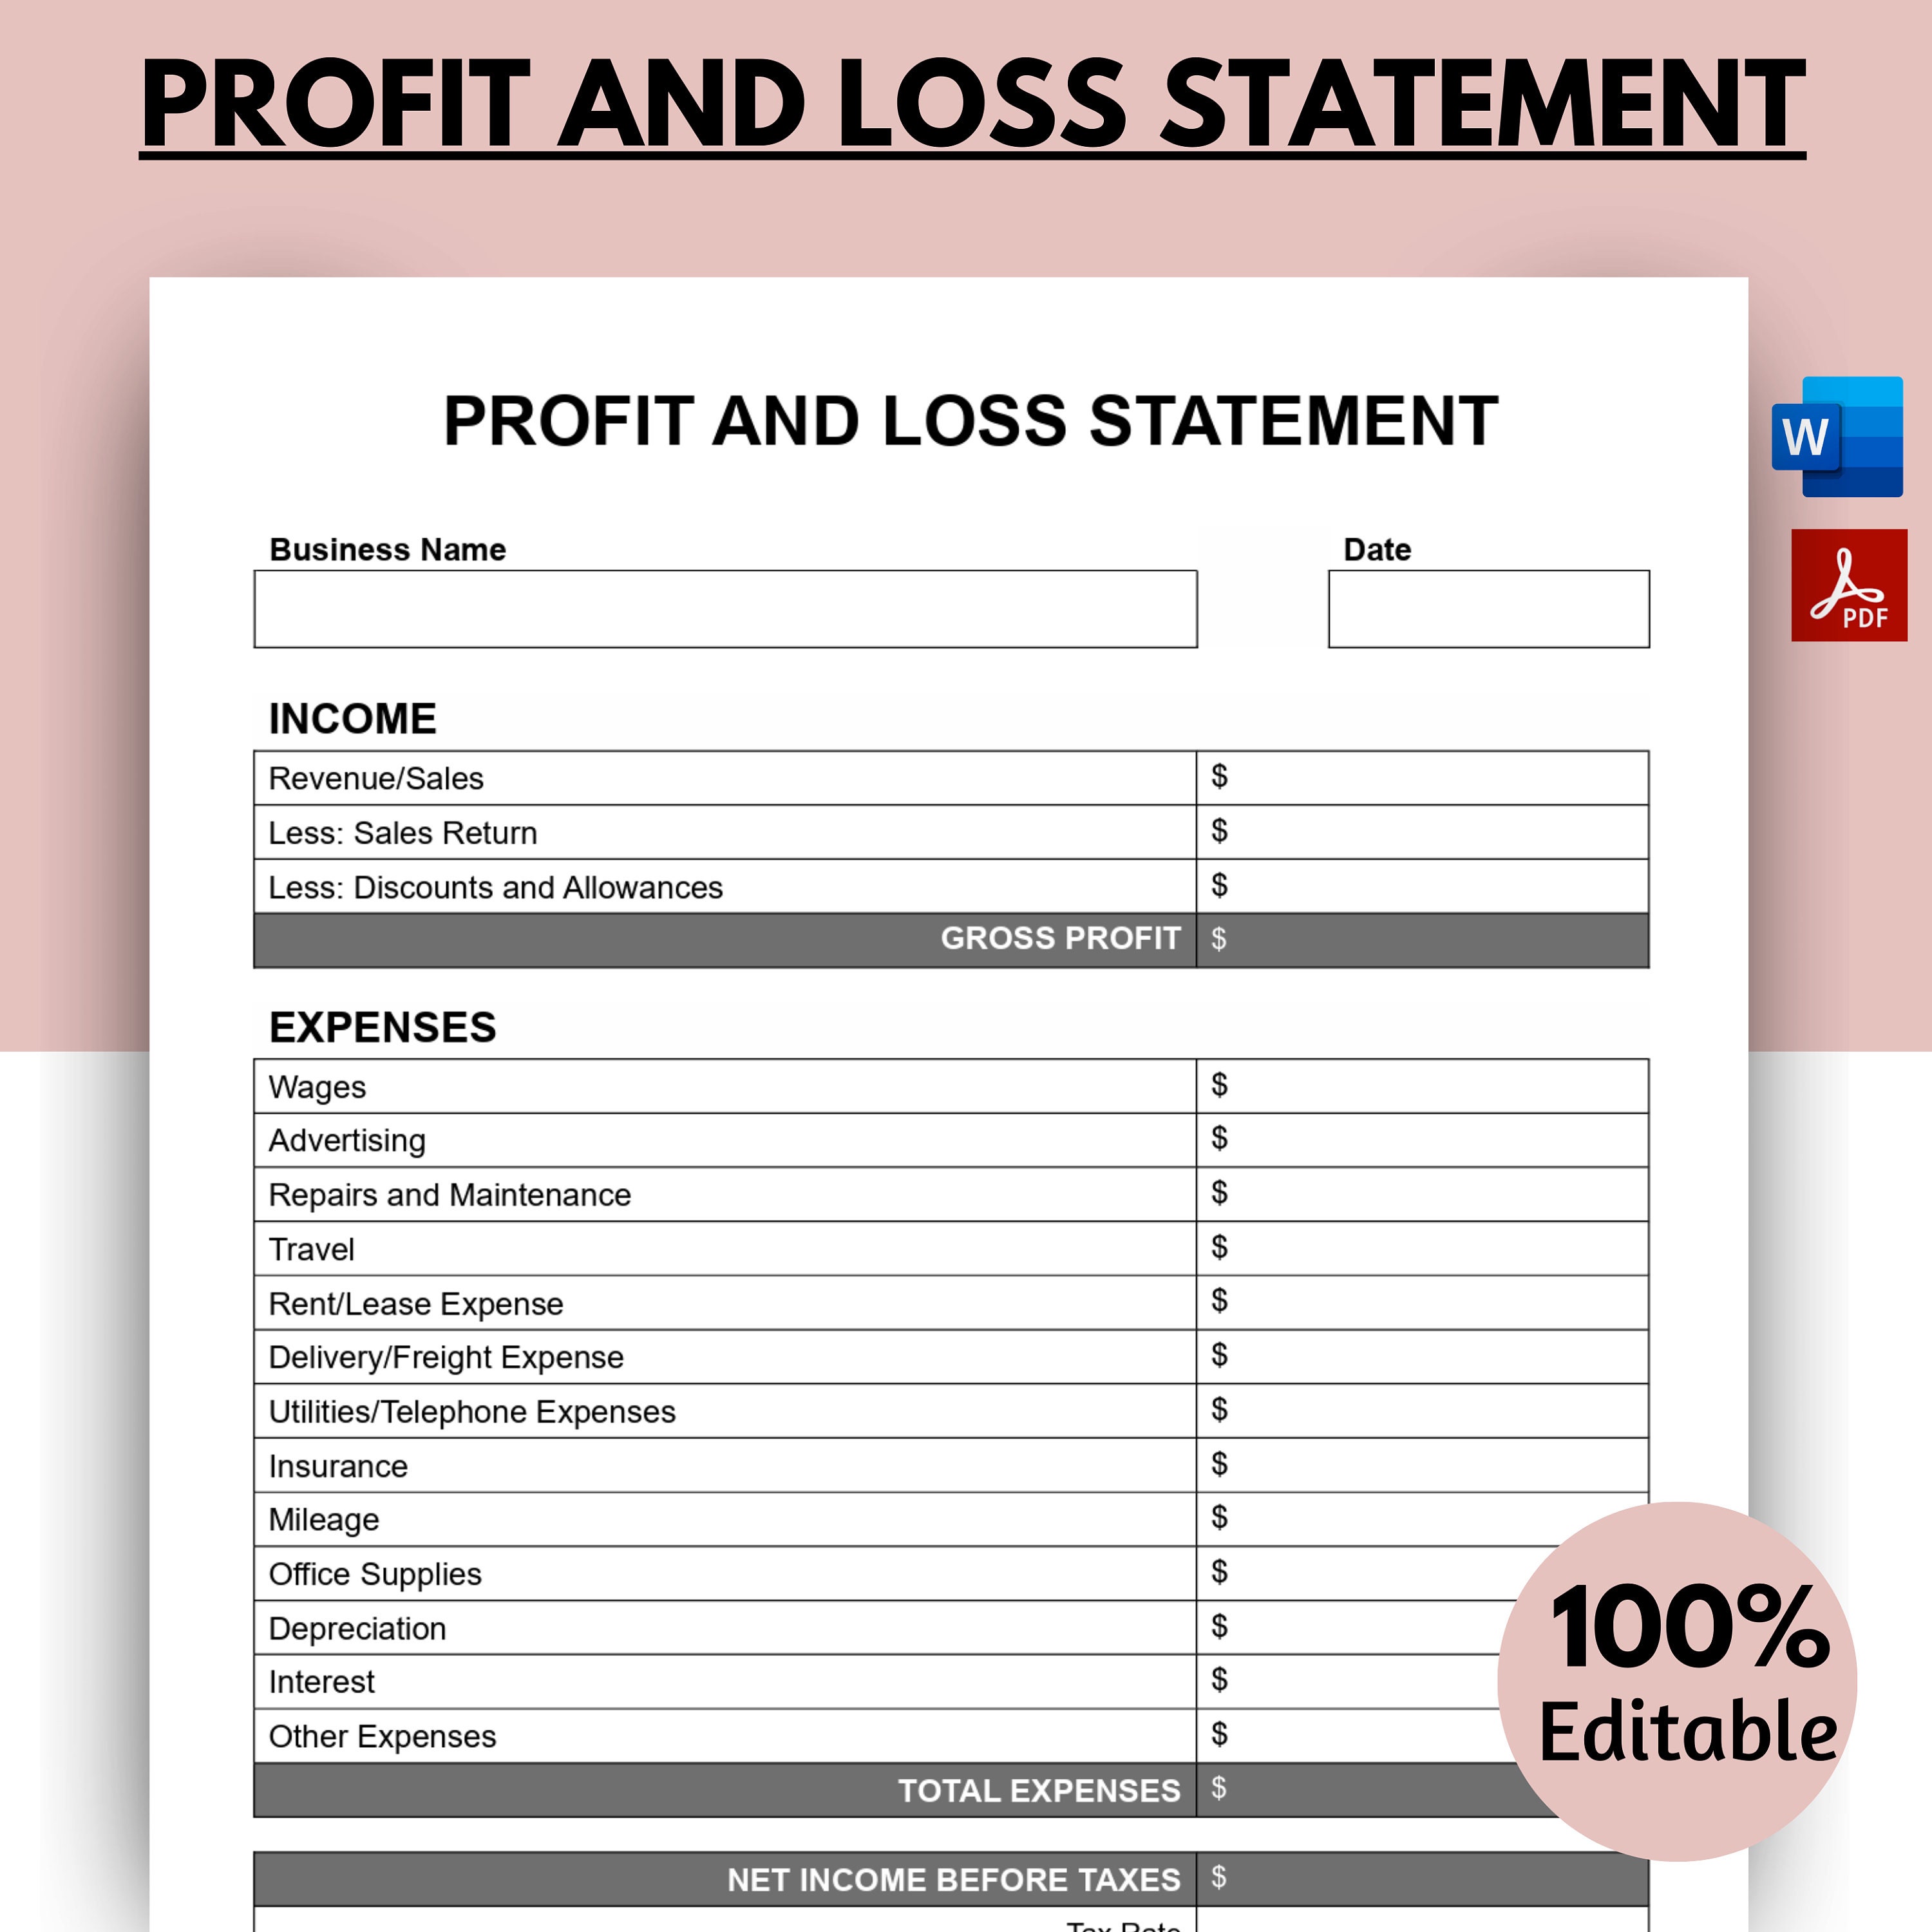
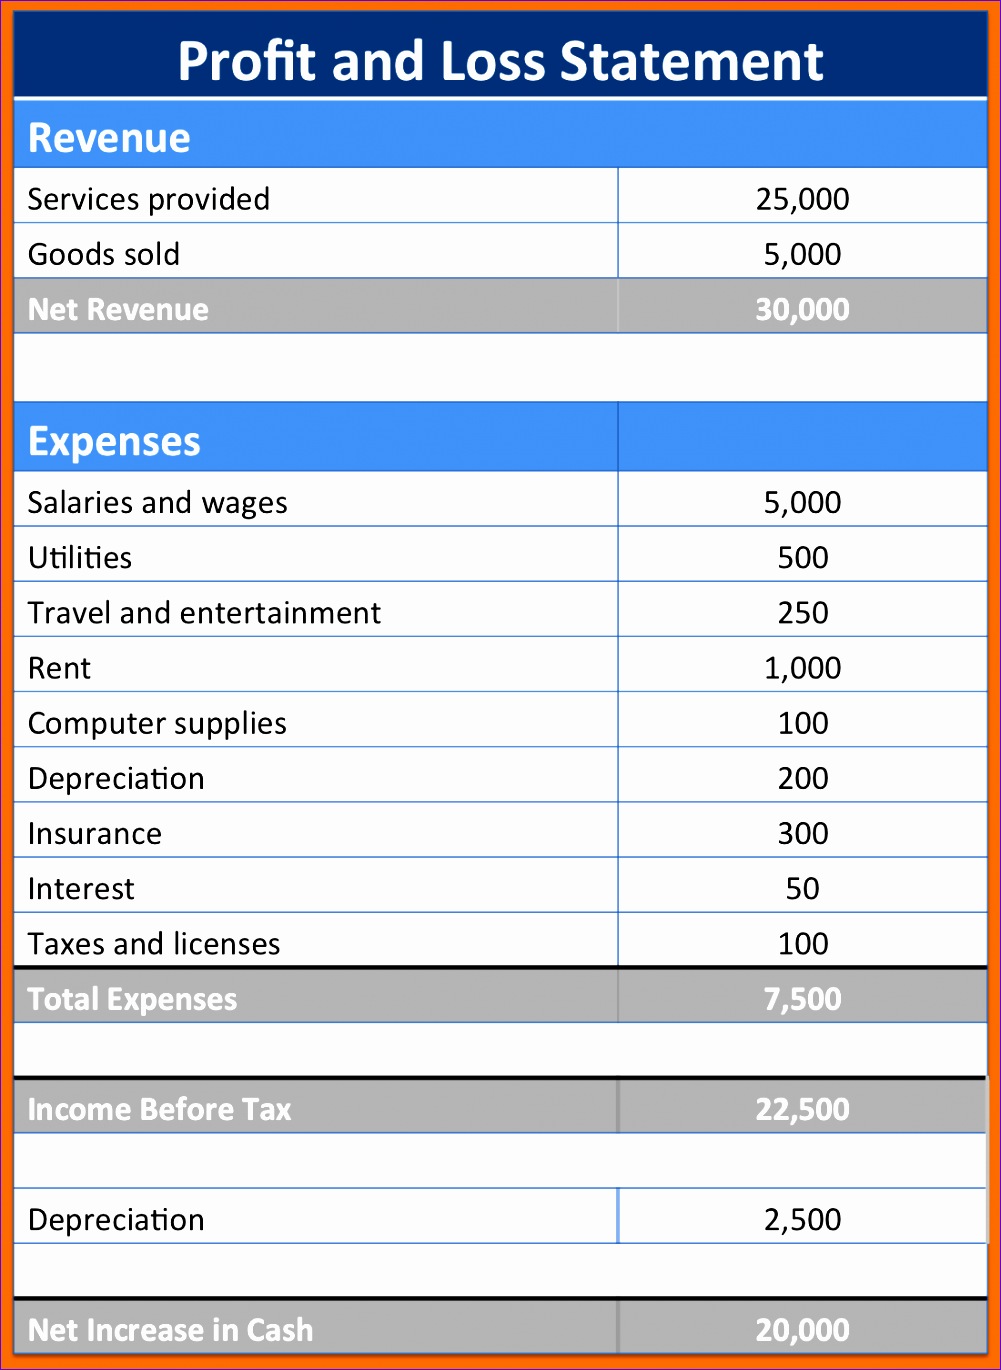
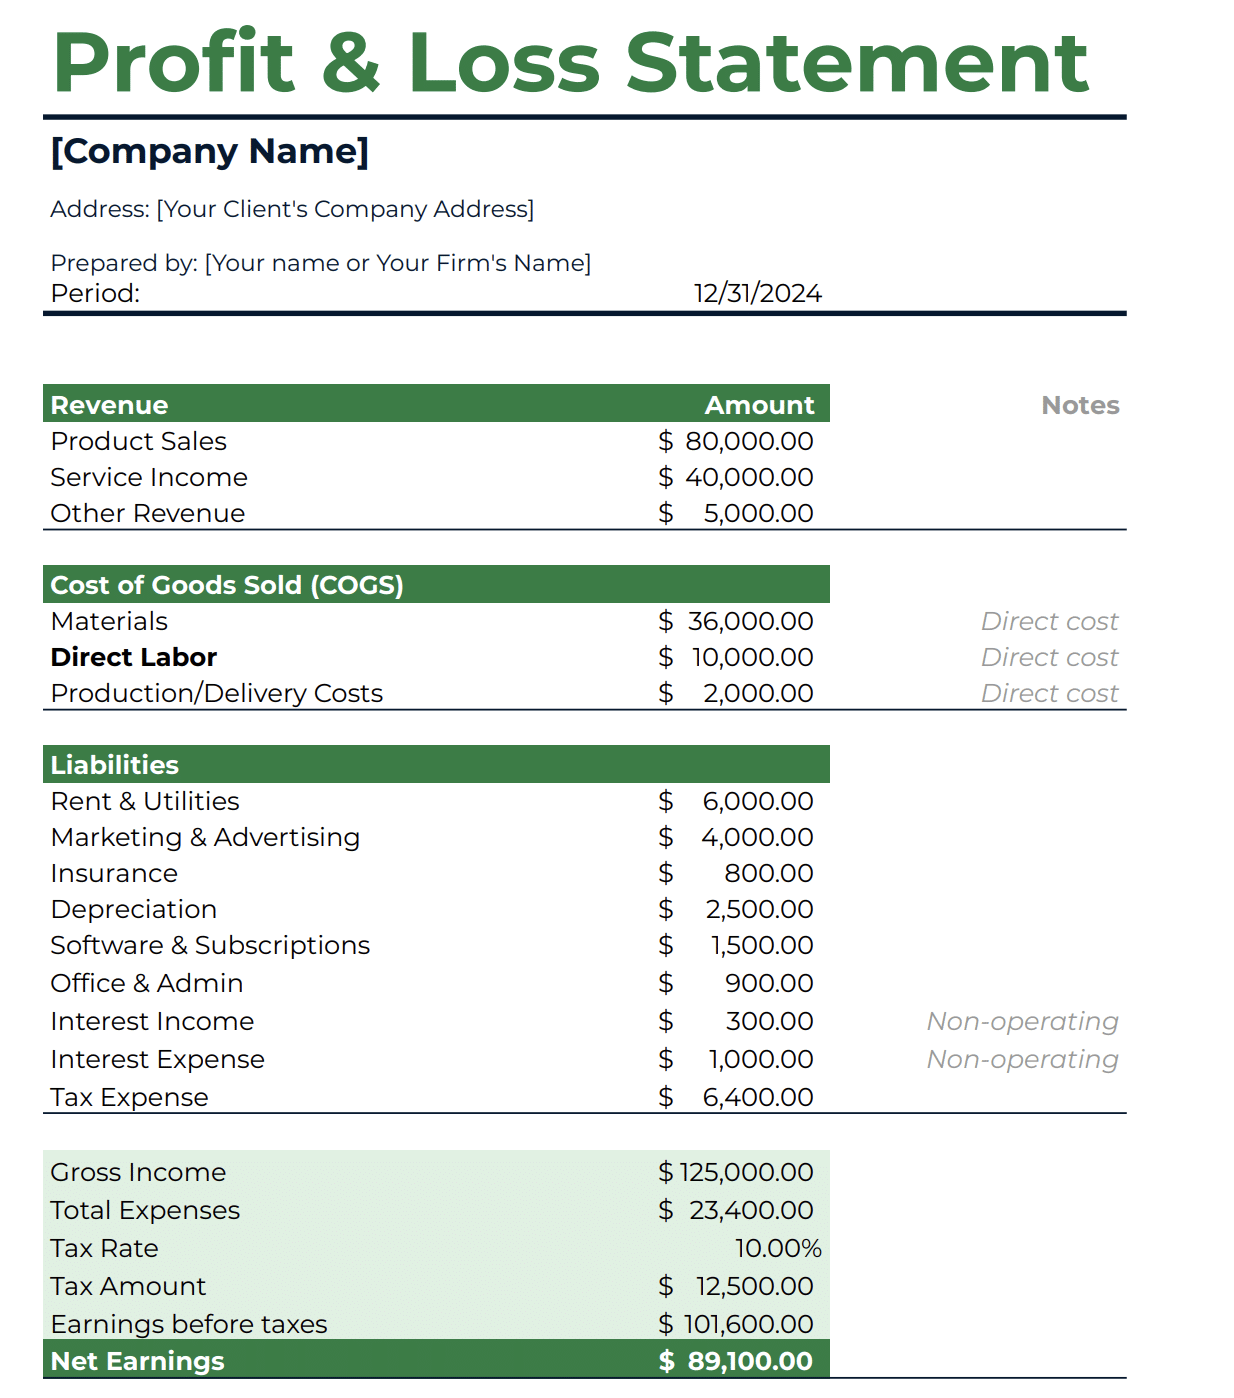
A profit and loss statement is just revenue minus expenses, but the version people actually use in business isn't the one from the textbook. Most free templates you'll find online are garbage. They lump everything into vague categories, don't account for COGS properly, and have hard-coded numbers that make them useless once real data hits them. What follows is how I actually build mine, along with a template structure you can copy. Here's a layout that's held up across a dozen different businesses over the years. It's deliberately simple because complexity in a P&L usually means someone is compensating for not understanding their own margins. Revenue section:
Start with gross revenue, then subtract returns, allowances, and discounts to get net revenue. Don't skip this step. I've seen people present to investors with inflated revenue numbers because they never pulled back the chargebacks and promo credits. Your net revenue figure should match your actual bank deposits minus refunds. If it doesn't, you have a reconciliation problem that this section will expose. Cost of Goods Sold: List raw materials, direct labor, and manufacturing overhead here. This needs to be tracked per unit if you're selling physical products. I worked with a client last year who had a P&L that showed a 40% gross margin, but when I traced the COGS back to individual product lines, two of their six products were actually losing money after accounting for shipping and packaging. The aggregated number was hiding a structural problem. If you can't break COGS down to the product or service level, you're flying blind on pricing decisions.
Gross Profit: Net revenue minus COGS. That's it. Put it on its own line and track it monthly. Month-over-month changes here tell you more about your business health than net income does, especially in early stages. Operating Expenses:
Get the Full Details

Break these into Rent, Salaries (non-direct), Marketing, Software/Tools, Insurance, Professional Fees, and Miscellaneous. Every expense should have a category code so you can sort and filter later. I recommend adding a sub-column for whether each cost is fixed or variable, because that distinction matters more than people realize when you're deciding what to cut during a downturn. EBITDA: Gross profit minus operating expenses. Some people call this operating income. EBITDA is useful because it strips out tax situations and financing decisions, giving you a cleaner picture of operational performance. Add back depreciation and amortization if you need to get to cash flow, but keep them separate for clarity.
Net Income: Take EBITDA, subtract interest, taxes, and any one-time gains or losses. This is your bottom line. Don't celebrate it before you verify it against actual cash in the bank, because accrual accounting can make your P&L look healthier than your bank account for months at a time. The template itself should be a spreadsheet with separate sheets for monthly data entry, annual summaries, and category roll-ups. Color-code the input cells so you know what you're allowed to change versus what formulas will calculate. I've seen too many people accidentally overwrite formula cells and spend three hours debugging why their numbers don't tie out.
Where People Mess This Up
One thing that catches people off guard is timing. If you're on a cash basis, your P&L reflects when money moves. If you're on accrual, it reflects when transactions happen. Mixing the two without realizing it creates phantom profits and losses that show up on paper but never hit your actual balance. I had a contractor client who switched from cash to accrual mid-year and couldn't figure out why his P&L looked terrible for Q2 even though he'd been paid on time. He had invoices sitting in accounts receivable that hadn't cleared yet. The revenue was real, just not liquid. Once I moved him to tracking both metrics side by side, the confusion stopped. Another common error is capitalizing expenses that should be deducted immediately. Equipment purchases under a certain threshold should be expensed, not depreciated over years, unless you have a specific reason to do otherwise. The IRS has rules around this (Section 179 elections, de minimis safe harbor), but the practical effect is that expensing keeps your P&L honest for decision-making purposes. Depreciation schedules are for tax compliance, not for understanding whether your business model works. The template I shared above is meant to be adapted, not copied verbatim. If you're a service business, your COGS will look very different from a manufacturer's. If you're a SaaS company, you'll want to add recurring revenue metrics and customer acquisition cost breakdowns. The structure remains the same, but the line items shift based on what actually drives your costs and revenue. Start with something lean and add complexity only when you hit a blind spot.
 (1).png "Profit and loss statement template | Free download")