What the Book Actually Is
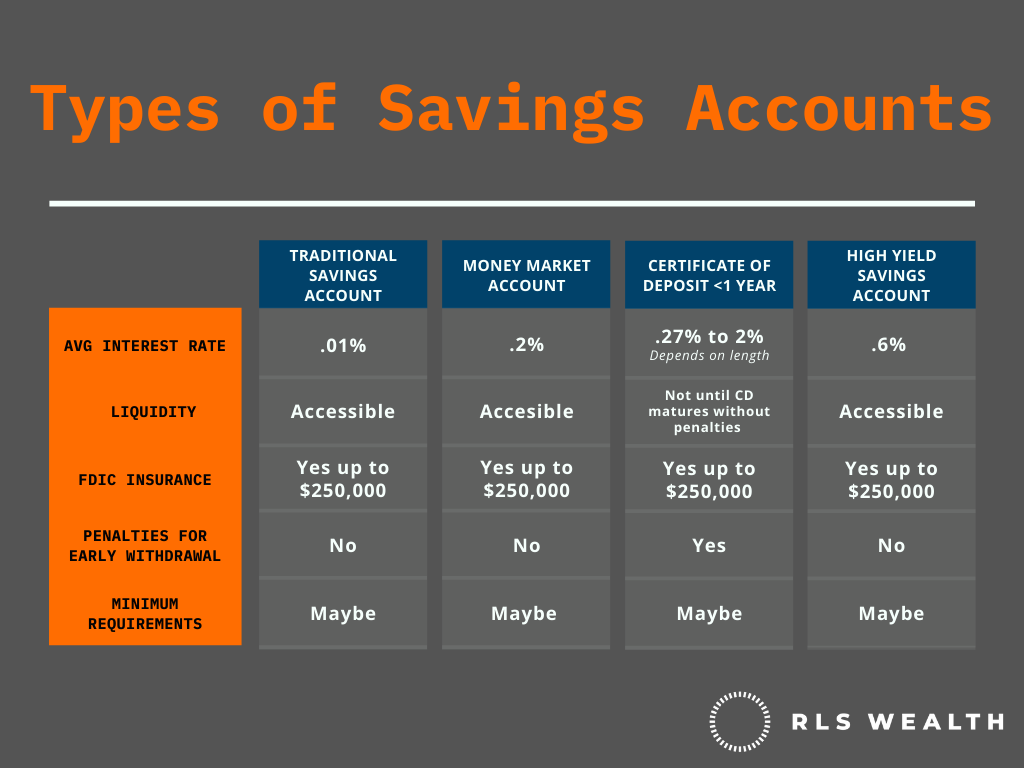
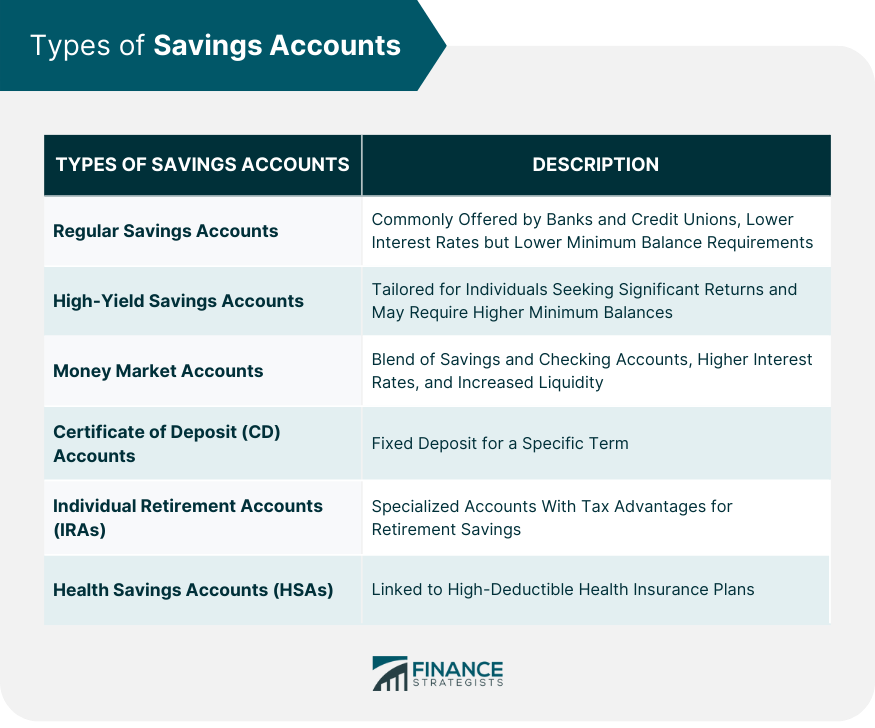
Savings Accounts For Dummies is a real book in Wiley's long-running For Dummies series, aimed at people who want a plain-language walkthrough of how savings accounts work and how to pick one that doesn't waste their money. It's not a course, it's not a software tool, and it's not a substitute for reading your account terms. The 2022 edition covers high-yield savings accounts, online banks, FDIC insurance mechanics, and basic account management strategies. You can find it on Amazon, Barnes & Noble, or directly from Wiley's site in paperback, Kindle, or ebook formats. The book does one thing well: it explains the terminology without assuming you already know it. If you've ever stared at an APY line and had no idea whether 4.5% meant you were getting rich or just slightly less poor than last year, this will clarify that. APY accounts for compound interest; APR does not. That distinction matters more than most people realize when they're comparing two accounts side by side. Where the book falls short is speed. Bank products change faster than print editions get updated. The 2022 edition was written when yields were near zero and most people had no reason to look beyond their local credit union. That context is obsolete now. The underlying concepts—FDIC coverage, compound frequency, fee structures—are still correct, but the competitive landscape has shifted entirely toward online banks offering rates five to ten times what traditional brick-and-mortar institutions pay. The book won't tell you which specific banks are competitive today because that changes quarterly.
I ran into this exact gap when I was helping a relative shop for a savings account back in 2024. The book recommended evaluating annual percentage yield as the primary decision factor, which is sound advice in theory, but it didn't cover the fact that many banks now offer tiered rate structures where your balance has to hit a certain threshold before you unlock the advertised APY. I found this out the hard way after routing money into an account that advertised 4.80% APY, only to discover the rate dropped to 0.01% once your balance fell below $25,000. The workaround was straightforward: I pulled the rate table directly from each bank's fine-print page, filtered for the customer's actual balance tier, and compared effective yields rather than headline numbers. This cut the research time from an afternoon of browsing to about twenty minutes of focused comparison. Another counter-intuitive detail the book glosses over is that not all high-yield savings accounts compound the same way. Some compound daily and credit monthly, some compound monthly, and some only calculate interest on your average daily balance during the month. The difference between daily compounding with monthly crediting versus monthly compounding with monthly crediting on a $10,000 balance at 4.5% APY over one year is roughly $3 to $4. That sounds negligible until you scale it up or hold the account for multiple years, at which point the gap becomes noticeable. The book mentions compounding exists but doesn't walk you through how to calculate the effective difference between structures without using a spreadsheet. There's also the question of relationship pricing, which most beginners never consider. Some institutions will boost your savings rate if you also have a checking account or direct deposit set up with them. This is a common tactic among regional banks trying to compete with online-only players. The book touches on it in passing but doesn't give you a framework for deciding whether bundling products is worth the convenience trade-off. In practice, if you're already maintaining checking accounts at two or three places, adding a savings account for the rate bump makes sense. If you're starting from scratch and value simplicity, the extra relationship maintenance usually isn't worth a quarter-point rate improvement.
The one scenario where the book is genuinely useful is explaining FDIC insurance limits clearly enough that a first-time saver understands they're protected up to $250,000 per depositor, per insured bank, per ownership category. Most people I talk to have a vague sense that their money is "insured" but can't articulate what that actually means in practice. Ownership categories include single accounts, joint accounts, certain retirement accounts, and revocable trust accounts. Keeping balances under the per-bank limit within each category is the only way to maximize that protection, and the book lays this out without the usual financial-industry obfuscation. One limitation worth stating bluntly: the book assumes you're making decisions based on publicly available information. It doesn't teach you how to read between the lines of bank marketing materials, where rates are often advertised with conditions attached. You can find the actual rate table by searching the bank's name plus "rate sheet" or "deposit products," and filtering for your specific balance. This takes thirty seconds and prevents the most common mistake I see, which is opening an account based on a homepage banner ad and then wondering six months later why the interest payments look wrong. If you want the full walkthrough, the book runs about 300 pages and costs around $14 in paperback or less as an ebook. It's structured more like a reference than a novel, so flipping through it section by section before you open an account is more efficient than reading cover to cover. The chapters on choosing a bank, understanding fees, and setting up automatic deposits are the ones most people actually use. The chapters on inheritance tax implications and estate planning considerations are useful if you have that context already, but irrelevant for someone just trying to park an emergency fund somewhere safe.
Get the Full Details