Understanding Why Scarcity Drives Everything in Economics
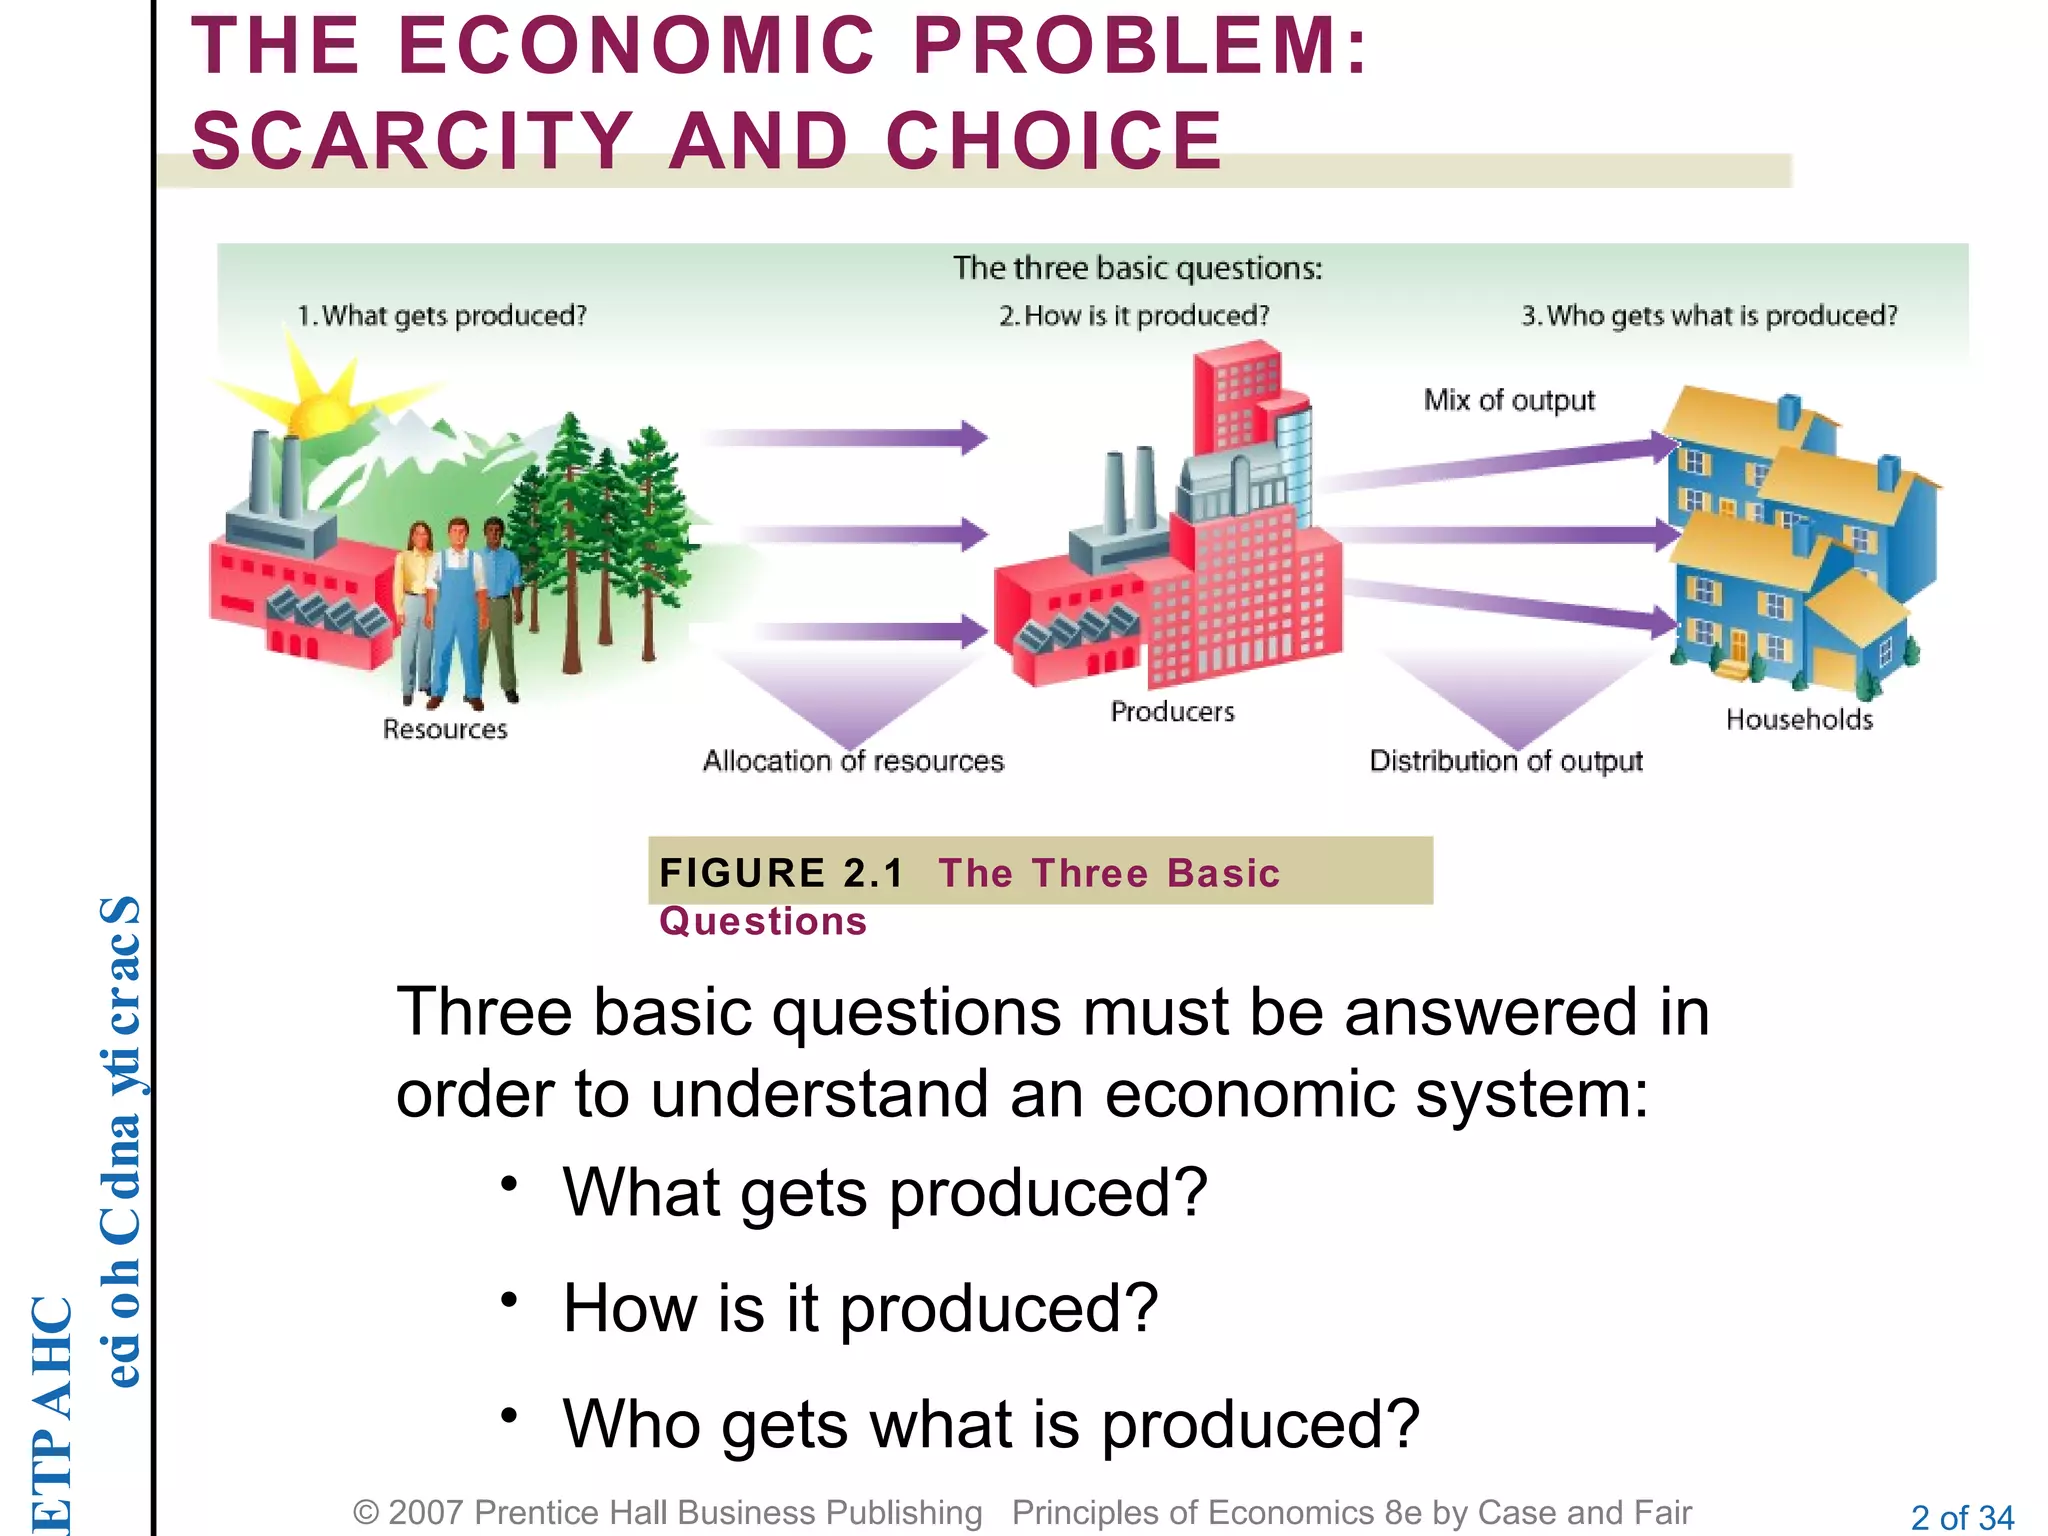
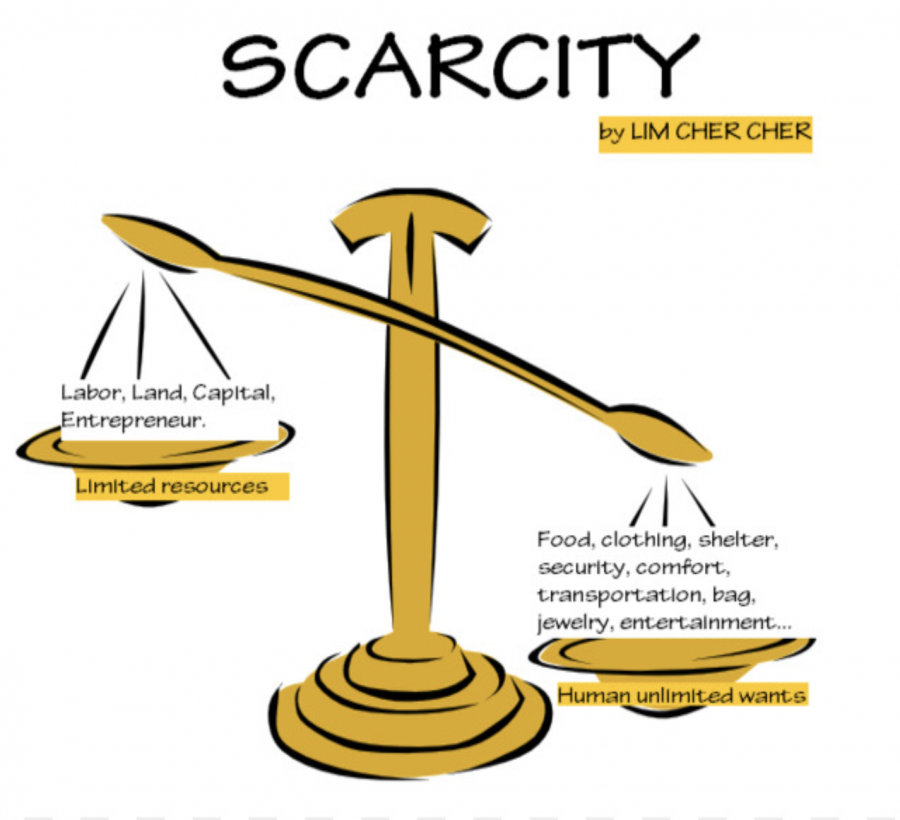
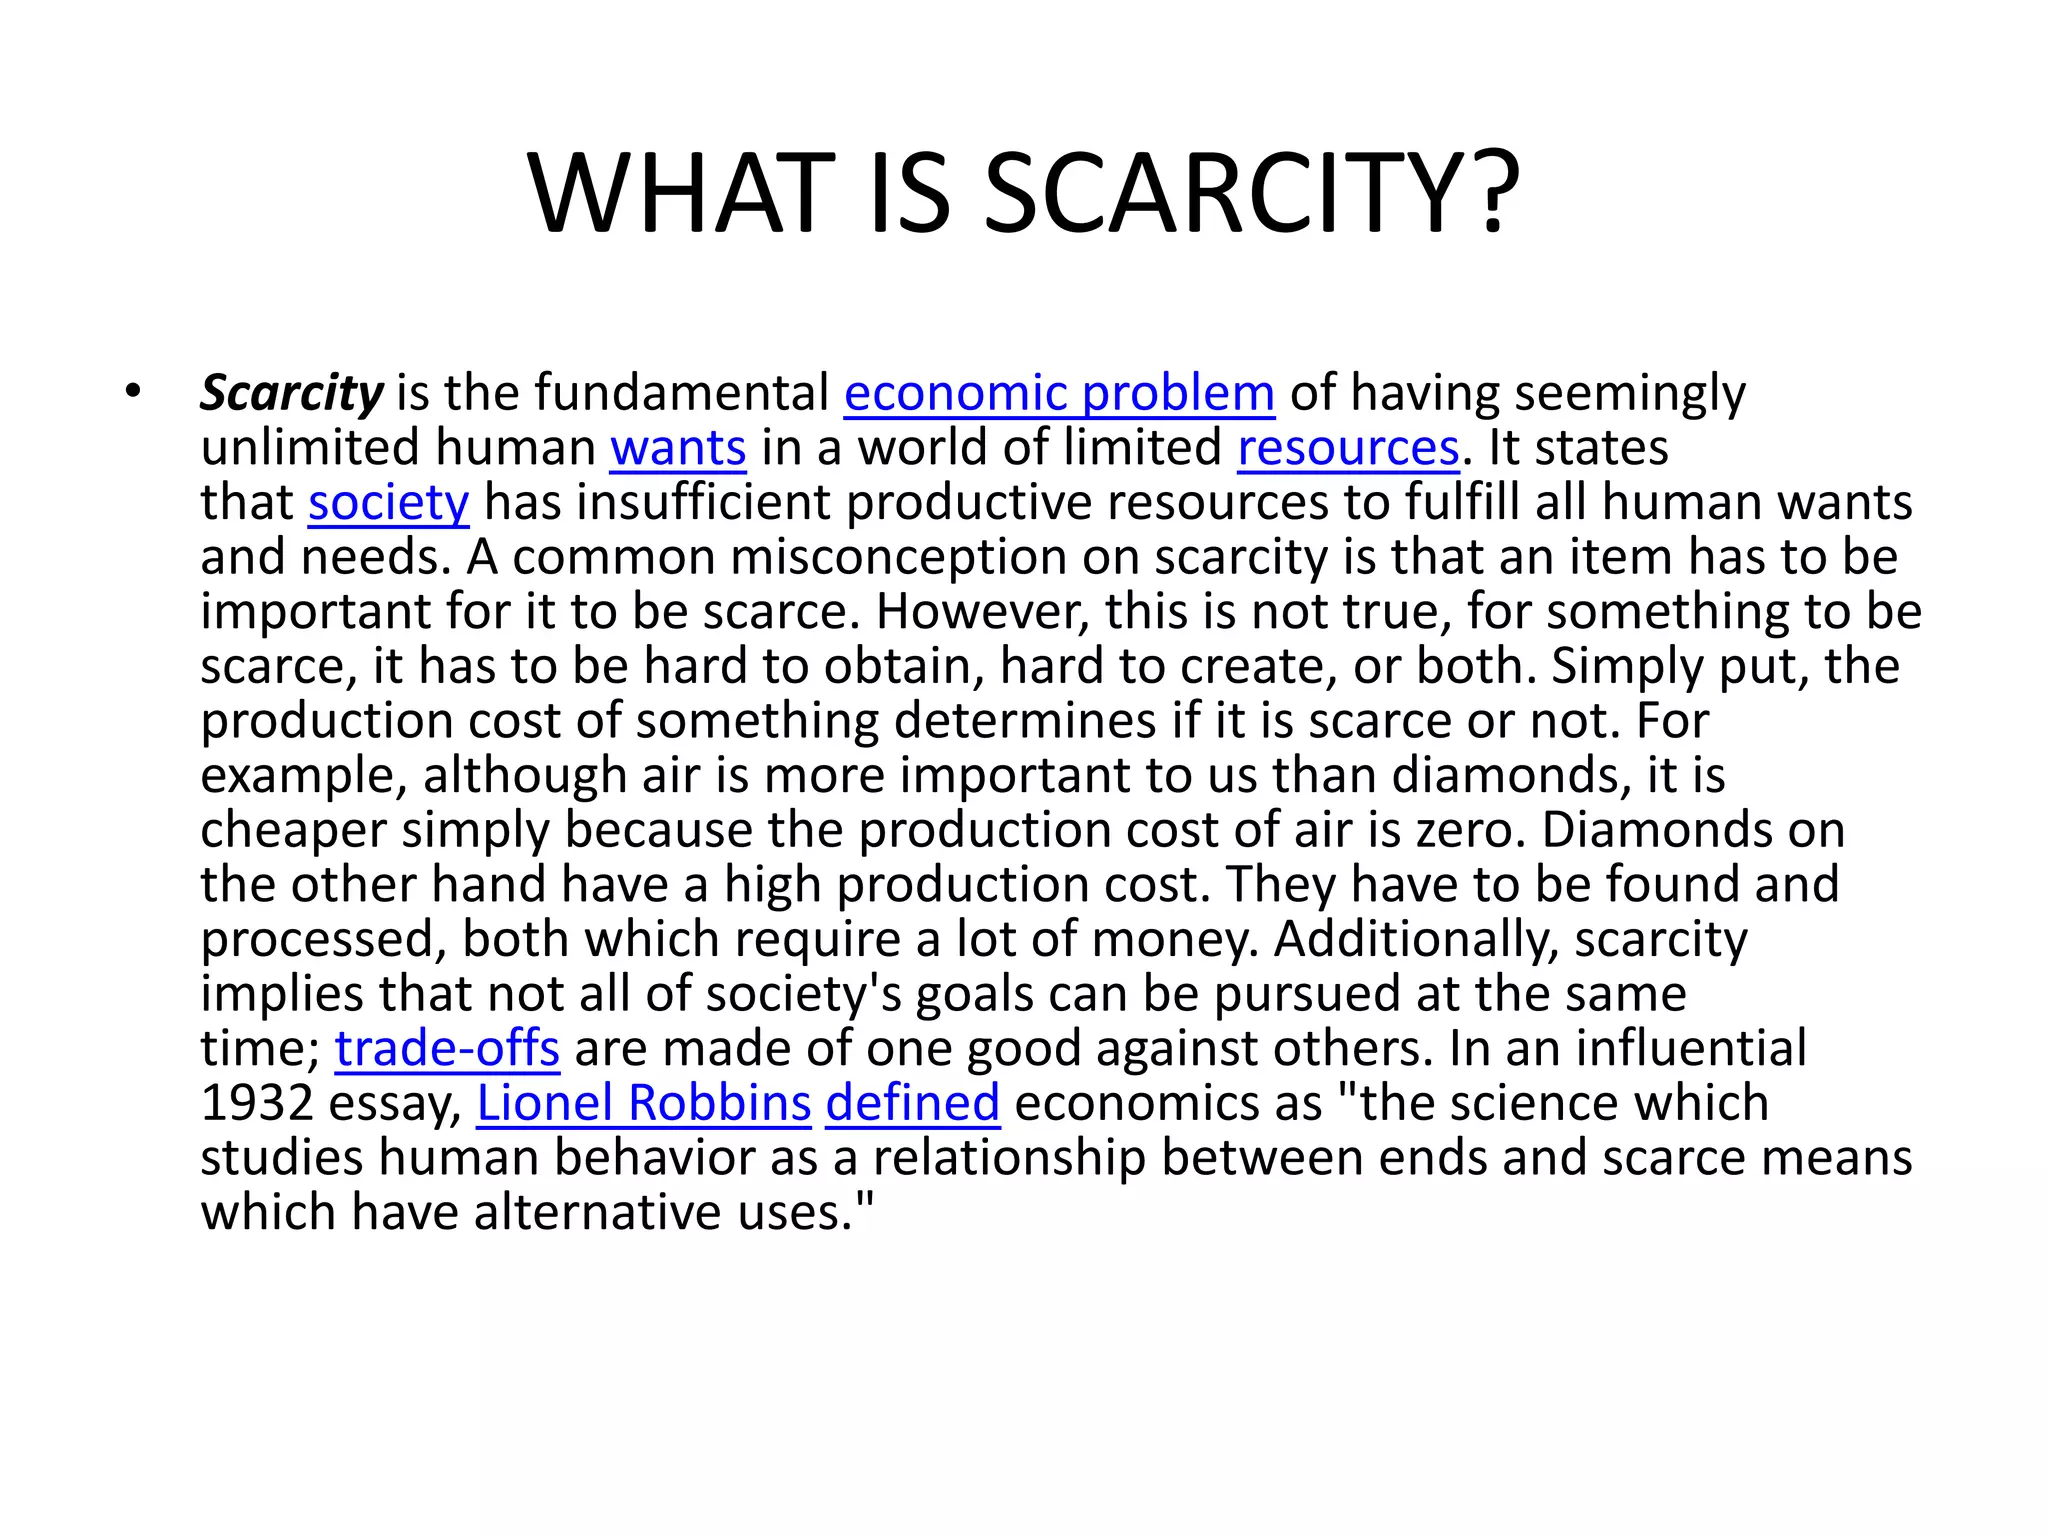
You pick up any intro economics textbook and the first chapter talks about scarcity. It sounds simple at first glance, but the way it actually plays out in real markets is where things get interesting. Scarcity is the foundational constraint that forces every economy to answer three questions: what to produce, how to produce it, and for whom. Without limited resources against unlimited wants, none of the machinery of economics would need to exist. Resources are finite. Human desires are not. That tension creates scarcity, and scarcity creates the need for choice. Every decision to allocate a resource to one use means taking it away from another. This is the opportunity cost that economists obsess over, and it shows up everywhere from personal budgeting to national policy. I spent years working on resource allocation models for municipal planning, and the thing that always tripped people up was assuming scarcity only applied to physical goods. It applies to time, attention, bandwidth, capital, even political will. When I was modeling water distribution for a drought-stricken region, we had to treat time of day as a scarce resource alongside the water itself. Peak usage windows created bottlenecks that were just as constraining as the total volume available. The workaround was implementing tiered pricing that shifted demand to off-peak hours rather than trying to expand supply, which was physically impossible given the aquifer depletion we were dealing with.
The standard definition tells you scarcity means limited resources and unlimited wants. The practical version is messier. Scarcity is relative, not absolute. Something is scarce only in relation to the demand placed on it. Land in Manhattan is scarce. Land in rural Nebraska is not, at least not in the same way. The scarcity emerges from the intersection of desire and availability, and that intersection shifts constantly.
How Scarcity Actually Functions in Markets
Price mechanisms exist primarily to manage scarcity. When a resource becomes scarcer, the price rises, which dampens demand and signals producers to find more. This is the basic feedback loop. But it breaks down in several important edge cases that beginner economics courses rarely cover adequately. Consider merit goods and demerit goods. Healthcare, education, clean air. These are goods where the market price fails to reflect true scarcity because access is tied to income rather than genuine resource constraints. I worked on a project analyzing school funding formulas and the disconnect between actual classroom resource scarcity and the funding mechanism was staggering. Property tax-based funding meant that the communities with the highest need often had the least capacity to address it, creating a scarcity multiplier effect that pure price theory couldn't account for. Another common pitfall is assuming that technology eliminates scarcity. It doesn't. It changes the nature of it. When smartphones became ubiquitous, screen time became the new scarce resource. Not the device itself, but the attention it consumes. We saw this play out in digital advertising markets where inventory expanded infinitely but human attention remained the binding constraint. The CPM rates didn't collapse because the scarcity shifted from impression inventory to viewer engagement.
Get the Full Details

Government intervention adds another layer of complexity. Price ceilings and floors distort the scarcity signal. Rent control in cities like New York and San Francisco is a textbook example. By suppressing prices below the equilibrium level, you create artificial scarcity in housing supply while simultaneously discouraging new construction. The result is a black market for apartments and a decades-long backlog that no single policy fix has resolved. I've seen cities try lottery systems and preference-based allocation, and they all introduce their own inefficiencies. There is no clean solution because the underlying problem is political, not technical.
The Dark Side of Scarcity Thinking
One counter-intuitive reality is that artificial scarcity can be more damaging than natural scarcity. When resources are genuinely scarce, markets adapt. When scarcity is manufactured through patents, quotas, or regulatory capture, adaptation is blocked. The pharmaceutical industry runs on this model. Drug patents create legal scarcity that persists long after the marginal cost of production would suggest competitive pricing should apply. Similarly, subscription economies have created a new category of scarcity: access rather than ownership. You don't own the software, the media library, or the e-book. You pay for continued access to something that could be revoked at any time. This shifts scarcity from a one-time transaction problem to a perpetual revenue problem for providers and a perpetual vulnerability for consumers. The economic efficiency argument here is thin at best. There is also the psychological dimension that standard economics models largely ignore. Scarcity mindset, studied by researchers like Sendhil Mullainathan, shows that perceived scarcity actually reduces cognitive capacity. When people are operating under scarcity constraints, their decision-making quality degrades in measurable ways. This creates a feedback loop where scarcity induces poor decisions that perpetuate scarcity. Policy interventions that only address the material dimension without accounting for the cognitive toll tend to underperform their models predict.
What This Means Practically
If you are making resource allocation decisions, whether personal or organizational, the first step is identifying the actual binding constraint. Most people default to assuming money is the constraint when it rarely is. Time, attention, specialized skills, regulatory approval, or institutional knowledge are more commonly the real bottlenecks. Misidentifying the constraint leads to throwing money at problems that money cannot solve. The second step is understanding that eliminating scarcity is usually the wrong goal. The right goal is managing it efficiently. This means building flexibility into your allocation decisions so that when constraints shift, you can reroute without systemic failure. Redundancy is expensive but it is the insurance premium against catastrophic scarcity events. I learned this the hard way during a supply chain disruption where our just-in-time inventory model collapsed because we had optimized away all slack. The cost of restoring operations was roughly six times what the redundancy would have cost to maintain. For individuals, the practical takeaway is that recognizing your personal scarcity constraints honestly is harder than it sounds. Most people overestimate their available time and underestimate their cognitive bandwidth depletion. Tracking actual time expenditure for two weeks will usually reveal a different picture than your intuition suggests. The same applies to organizational resource planning. Forecast models that don't account for scarcity-induced decision degradation will consistently overperform reality.
The broader economic implication is that scarcity is not a problem to be solved but a condition to be managed. Any system that claims to have eliminated scarcity is either lying or has created new forms of it that are less visible but equally constraining. The useful analytical tool is not asking whether scarcity exists but identifying which scarcity is binding at any given moment and whether it is natural, artificial, or self-imposed.