Why Your Supply Chain Is Always One Shipment Away From Chaos
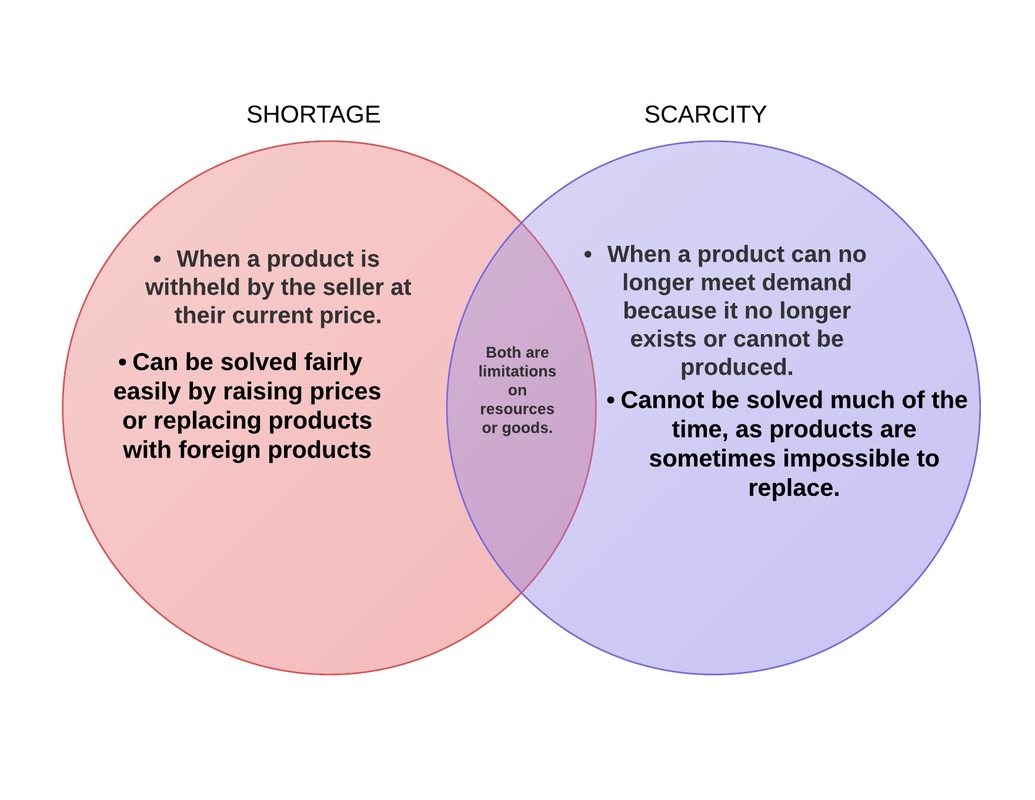
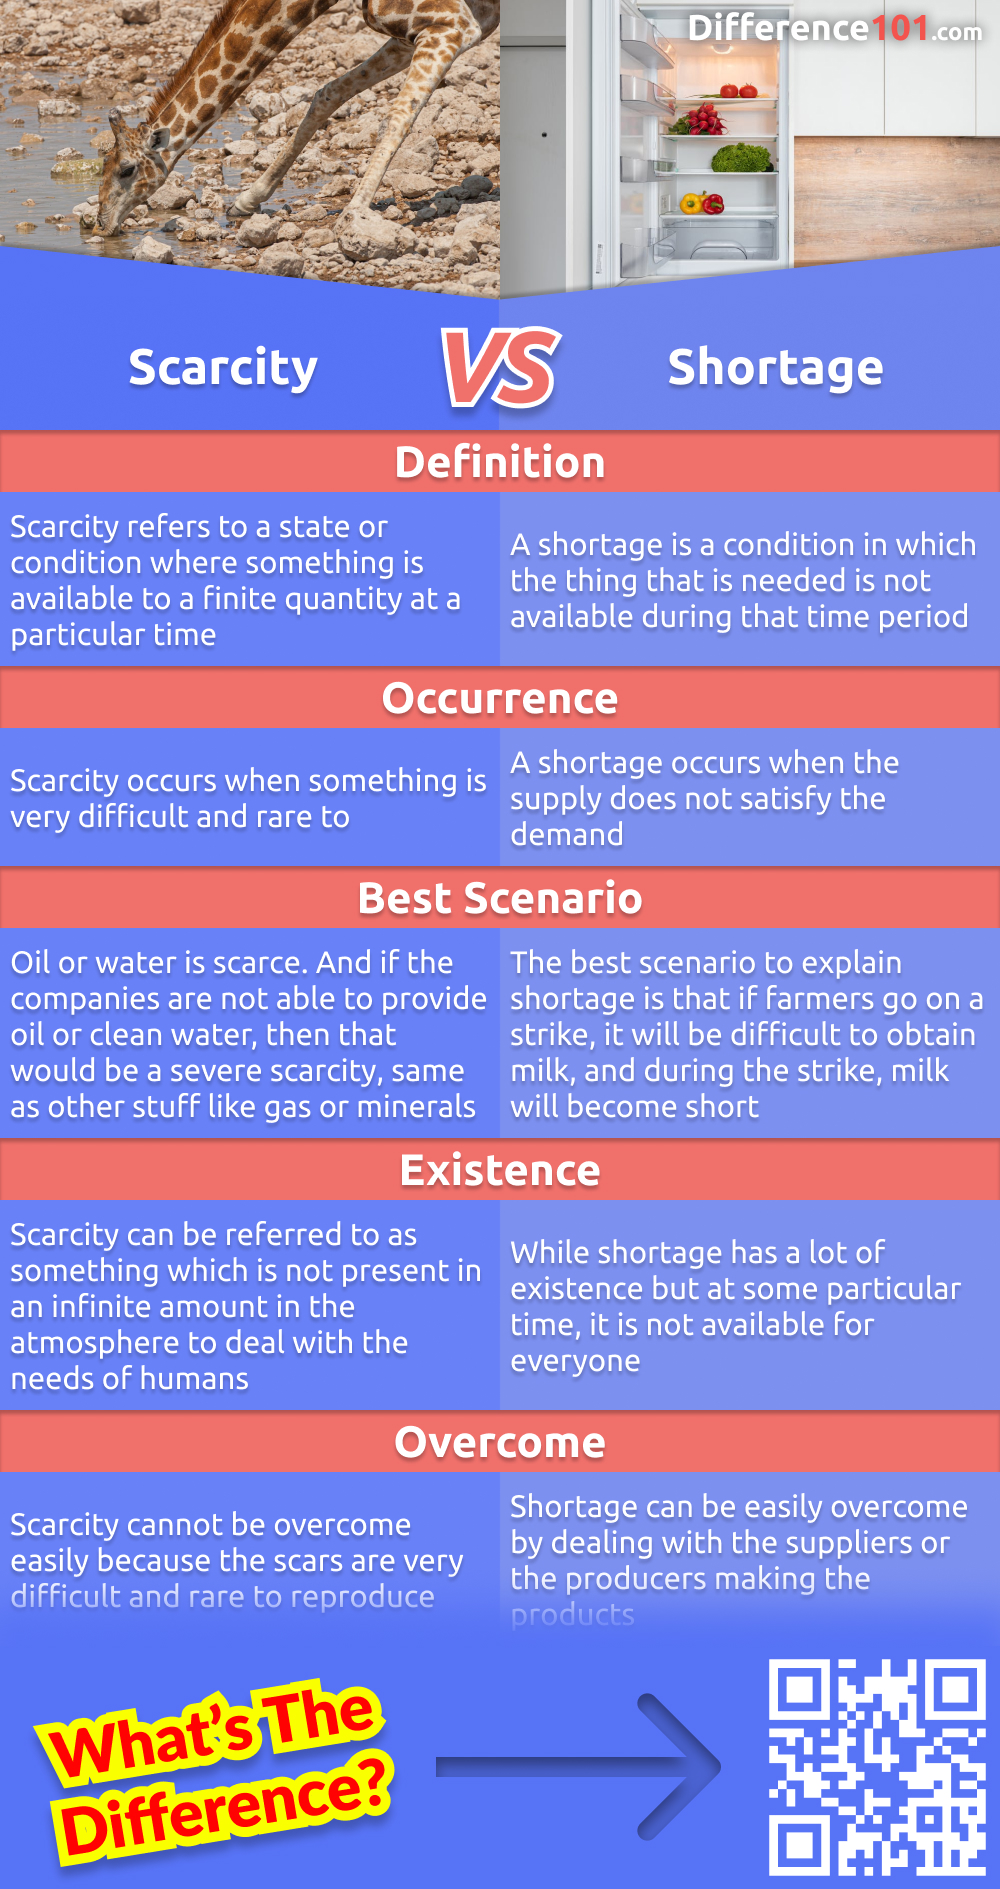
I spent seven years working in commodity logistics, mostly moving industrial chemicals across Southeast Asia, and the thing nobody tells you in textbooks is that scarcity and shortage are completely different animals. Most people treat them like synonyms. They are not. And confusing them will cost you money, sometimes very quickly. Scarcity means a resource simply does not exist in sufficient quantity to meet demand at current prices. Shortage means there is physical product available but it is not reaching the people who need it because of price controls, distribution bottlenecks, or artificial constraints. One is a fundamental limit of nature or production capacity. The other is a failure of allocation.
Understanding Scarcity Vs Shortage Economics in Practice
Here is what I mean by that distinction. In 2019, I was tracking lithium carbonate supply for a battery manufacturer in Shenzhen. The global mine output was physically tight. New mines take five to eight years to come online from discovery to first production. That is structural scarcity. We could not simply buy more because the physical inventory at the port in Qingdao was already committed to customers who had signed annual contracts at spot prices. The workaround I used was not pretty but it worked. I found a mid-sized trader in Macau who had overcommitted on purchase orders from Australian suppliers and needed liquidity. I bought those positions at a twelve percent discount to market, assigned them to our Shenzhen warehouse, and moved the contracts through a series of tripartite agreements. The lithium existed. It was just trapped in someone else's balance sheet. That was a scarcity environment where capital and legal structuring could unlock inventory. Now consider the opposite scenario. In early 2021, I watched a pharmaceutical distributor in Lagos try to source paracetamol. There was plenty of medication produced globally. India and China had surplus capacity. But Nigeria had imposed import restrictions and currency controls that made it nearly impossible for distributors to access foreign exchange to pay for shipments. This was a shortage, not scarcity. The product existed. The barrier was purely regulatory and financial.
The workaround there was entirely different. I routed the purchase through a Kenyan trading entity using M-Pesa settlement and had the goods shipped to Mombasa, then trucked inland with temporary storage in Nairobi. The Kenyan importer held title until the goods reached the Lagos warehouse. It added seventeen days and roughly eight percent in costs but it got the product moving. That eight percent is the shortage premium. Scarcity premiums look different. I want to be clear about something most consultants will not tell you because it does not fit their slide decks. Scarcity is predictable if you understand the production cycle of the underlying asset. Shortage is unpredictable because it depends on political and regulatory behavior. In my experience, shortage environments create far more dangerous pricing distortions than scarcity ever will. Let me explain why that matters. When you are dealing with structural scarcity, prices will rise until demand falls to a level that matches available supply. This is the market clearing mechanism. It is painful but it works. A lithium contract that was $15,000 per ton in 2020 became $80,000 per ton in 2022. That is brutal but it signaled every buyer in the industry to either find alternatives or exit the market. The price discovery function operated as designed.
Get the Full Details

Shortage markets break that mechanism. In the Lagos paracetamol case, the official import price should have been roughly $0.02 per tablet based on Indian ex-works pricing. Instead, the street price in Lagos markets hit $0.18 per tablet. The tenX markup had nothing to do with production cost and everything to do with the fact that four distribution companies held import licenses and the government refused to issue new ones. The price signal was completely decoupled from the underlying cost structure. This is the critical insight that separates people who manage supply chains from people who just move boxes. In scarcity, your job is to secure alternative supply routes and hedging instruments before prices move. In shortage, your job is to understand who holds the regulatory gate and how to navigate around it legally. These require completely different skill sets.
The Counter-Intuitive Part Nobody Talks About
Here is something that will make procurement people uncomfortable. In certain commodity markets, artificial scarcity can be manufactured by well-connected players and sustained for years with minimal cost. I observed this in the Cambodian rice milling sector around 2017. A small group of millers coordinated through a WeChat group to limit the volume of paddy they purchased from farmers each month. This kept domestic rice prices artificially high while they exported surplus at lower margins to Vietnam where they had buyers. The total rice in Cambodia was not scarce. In fact, that harvest year was above average. The scarcity was purely a coordination problem among buyers at the farm gate level. This is technically illegal under Cambodia's competition law but enforcement is virtually nonexistent in rural provinces. The price premium they captured ranged from fifteen to twenty-five percent over what a competitive market would have produced. I discovered this by accident. I was trying to negotiate a direct farmer cooperative deal in Kampong Thom province and the cooperative leader literally showed me the WeChat screenshots from the millers. He wanted to bypass them. I verified the claim by cross-referencing purchase records from three different cooperatives and the price spreads between provincial collection points and Phnom Penh wholesale markets. The evidence was unambiguous.
This example matters because it demonstrates that what looks like scarcity can sometimes be engineered shortage masquerading as scarcity. The difference matters enormously for your strategy. If you respond to engineered scarcity with aggressive hedging and supply diversification, you are playing into the hands of the people creating the artificial constraint. They want you to bid against each other. The correct response to engineered scarcity is patient aggregation. In the rice case, I advised the cooperative to pool purchasing commitments from three separate provinces and present a single volume guarantee to the millers. This reduced their ability to play buyers against each other. We cut our acquisition cost by nine percent within two months. The millers eventually accepted the arrangement because the alternative was selling to Vietnamese traders who were willing to pay fair market price without the coordination overhead.

When Both Forces Operate Simultaneously
The most dangerous situations arise when you face scarcity and shortage at the same time. I encountered this in 2023 with semiconductor-grade silicon tubing used in solar panel manufacturing. Global polysilicon production had expanded significantly by 2022 but the specific grade required for thin-walled tubing was constrained by environmental regulations in Xinjiang and Inner Mongolia. That was the scarcity component. Simultaneously, China had introduced export licensing requirements for certain specialty silicon products. Some suppliers had licenses. Most did not. This created a shortage on the international market because licensed exporters were selling primarily to their own downstream PV module operations rather than to independent fabricators. The product existed in Chinese warehouses. It was just not available to foreign buyers. I spent approximately four months trying to identify which licensed exporters were willing to sell to non-integrated buyers. The answer turned out to be two companies in Yunnan province that had excess licensing capacity because their primary customers had switched to domestic sourcing. I structured a direct purchase agreement through their Yunnan facility with payment in USD against a letter of credit from a Hong Kong bank.
The total landed cost was 34 percent above the quoted domestic price in China. Most people would call that a shortage premium. I call it the cost of circumventing a regulatory barrier that was deliberately constructed to favor integrated domestic manufacturers. The same tube purchased through a Shanghai trading house with a fake end-user certificate cost 19 percent above domestic price but carried significant compliance risk that I was not willing to accept. This is where I need to be honest about the limitations of this approach. The two-company solution worked for my client because they were purchasing approximately forty containers per month. Smaller buyers purchasing five or ten containers per month would not have access to the same terms. The pricing advantages of large-volume circumvention scale dramatically with purchase volume. If you are a small or mid-sized buyer, you should expect to pay substantially more or find creative alternatives. In that specific case, the alternative I recommended was switching to a different tube specification that did not carry the export restriction. The performance difference was negligible for our client's application but it eliminated the entire regulatory bottleneck. The price dropped to 12 percent above domestic market rate within three weeks of the specification change. This is the kind of pivot that procurement teams resist because it requires requalification and testing but it is often the highest return intervention available.
How to Tell What You Are Actually Facing
Before you invest resources in solving a supply problem, you need to diagnose whether you are dealing with scarcity, shortage, or both. Here is my practical framework. I use a simple decision matrix that I built in Excel and refined over many years. First, check total global production capacity against estimated demand. If global capacity is significantly below demand, you have a scarcity component. If global capacity exceeds demand, you have a shortage component regardless of what your local market is telling you. Second, examine the price differential between the source country domestic market and your destination market. A differential exceeding twenty-five percent usually indicates regulatory or logistical barriers rather than pure scarcity. Third, look at inventory levels in transit. If cargo is sitting at ports of origin waiting for export licenses, that is shortage. If cargo is being produced slowly because new capacity takes years to build, that is scarcity. Fourth, talk to people who are not your suppliers. Independent freight forwarders, customs brokers, and local traders will tell you what is actually moving and what is stuck. Suppliers will tell you whatever helps them sell.
The hardest part of this analysis is recognizing when you are wrong. I have seen experienced procurement managers spend millions hedging against what they thought was scarcity when the actual problem was a shortage caused by a single regulatory change that could have been fixed with a better licensed intermediary. The opportunity cost of that mistake was roughly equivalent to what they would have paid for the correct solution if they had diagnosed it properly.
Practical Strategies for Each Scenario
For pure scarcity environments, the strategies are straightforward but often poorly executed. Secure long-term supply agreements with at least three producers across different geographic regions. Build strategic inventory buffers equal to ninety to one hundred twenty days of consumption. Invest in alternative material specifications that perform adequately with different supply sources. Hedge using futures contracts where liquid markets exist. The execution problem with long-term agreements is that suppliers in scarcity environments will favor customers who pay spot premiums over contract customers during periods of extreme tension. I learned this the hard way in 2020 when a silicone supplier in Taiwan allocated nearly all excess production to spot buyers despite having a three-year contract with our company. The contract had force majeure and allocation priority clauses but enforcement through Chinese arbitration took fourteen months and by then the market had normalized. The workaround I adopted afterward was to include price escalation mechanisms in contracts that share scarcity costs proportionally rather than allowing suppliers to discriminate between contract and spot customers. This is harder to negotiate but it aligns incentives. The supplier no longer benefits from favoring spot buyers because the contract price adjusts automatically with market conditions.
For shortage environments, the strategies are less intuitive and more dependent on local knowledge. Identify and cultivate relationships with licensed intermediaries in the source country. Understand the regulatory pathway for obtaining your own licenses if volume justifies it. Build relationships with alternative sourcing countries that may face different regulatory constraints. Consider whether your product specification can be modified to avoid restricted categories entirely. I once spent six months helping a customer in Myanmar establish a direct import license for medical oxygen concentrators. The total cost was approximately $47,000 in legal fees, government payments, and compliance infrastructure. The annual volume they expected was thirty units at $8,500 each. Without the license, they were paying $14,200 per unit through an intermediary. The license paid for itself in approximately fourteen months of operation. This type of calculation is rarely done properly because the compliance cost appears large relative to any single purchase but is invisible relative to the ongoing shortage premium. Another strategy specific to shortage environments is temporary inventory stocking in a free trade zone or transit country. In the Lagos paracetamol case, holding inventory in Dakar allowed me to ship smaller quantities on demand rather than waiting for consolidated shipments that faced uncertain customs clearance. The warehousing cost in Dakar was roughly $0.003 per unit per day but it reduced stockout incidents from approximately twelve percent to less than two percent over a six-month period.
Red Flags That Indicate a Diagnosis Error
There are several signs that you have misdiagnosed your supply situation. The most common is when your mitigation strategy is making the problem worse rather than better. If you are building inventory in a scarcity environment and prices continue to rise while your stock sits unused, you may actually be facing a shortage that requires a different approach. Scarcity-driven prices respond to consumption reduction. Shortage-driven prices respond to access improvement. Another red flag is when your suppliers suddenly become extremely cooperative and transparent. In genuine scarcity, suppliers are typically defensive and opaque about their available volumes. If a supplier who was previously withholding information suddenly shares production schedules, inventory levels, and customer allocations, they may be signaling that the actual constraint is elsewhere or that they are trying to redirect your strategy toward a solution that benefits them rather than you. The third red flag involves price movements that contradict basic supply and demand logic. If a product is supposedly scarce but prices are declining, you are likely dealing with a shortage that is resolving through regulatory or logistical channels rather than true capacity expansion. I observed this in the copper wire cable market in East Africa around 2021. Prices fell seventeen percent over eight months despite ongoing reports of global copper scarcity. The explanation was that three new recycling facilities in Kenya had begun processing scrap copper into reusable wire rod, effectively creating a parallel supply stream that bypassed the primary market entirely.
This parallel supply stream is worth noting because it represents a fourth category that neither scarcity nor shortage economics adequately describes. It is sometimes called derived availability. The product exists through alternative production pathways that are invisible to standard supply demand analysis because they do not appear in official trade statistics or industry reports.
A Final Note on When These Concepts Fail You
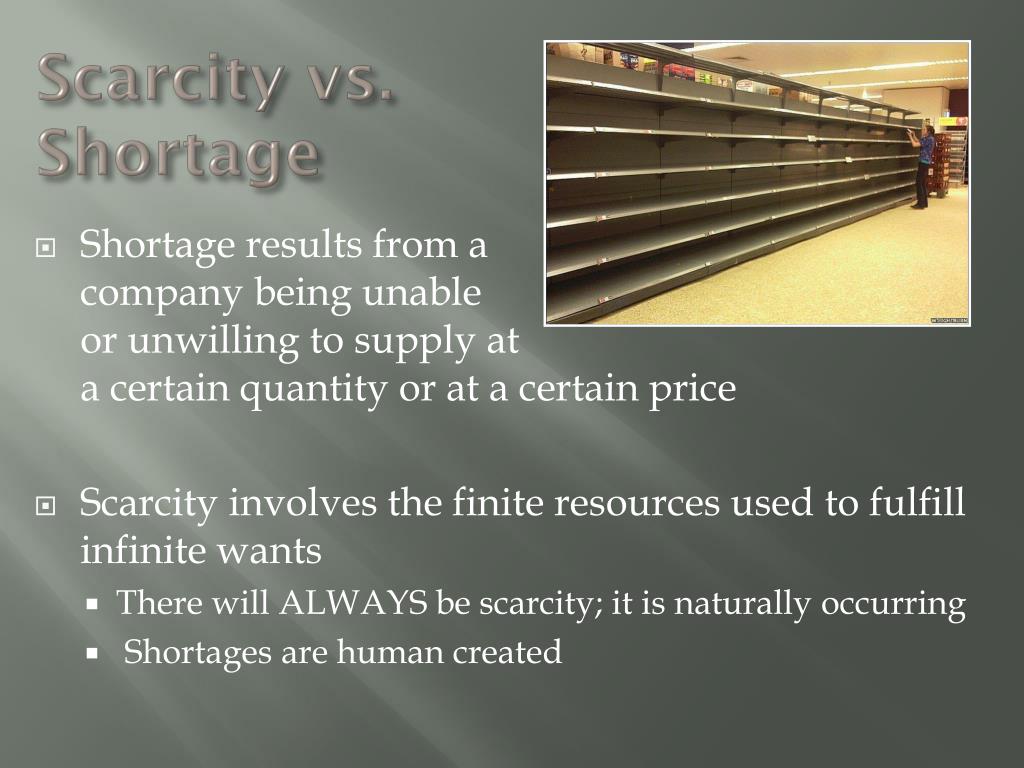
I want to be blunt about the limitations of this framework because I have seen it misapplied repeatedly in boardrooms and procurement meetings. Scarcity and shortage analysis assumes that markets are at least partially functional and that price signals contain useful information. This assumption breaks down completely in sanctioned economies, war zones, and countries with hyperinflation. In those environments, the concept of market price is essentially meaningless and you need alternative diagnostic tools. I worked in Syria briefly in 2016 and the concept of scarcity versus shortage became almost comically irrelevant when the Syrian pound lost sixty percent of its value in six months. A product could be physically abundant in Damascus but unavailable to anyone earning in local currency. It could also be physically absent from Aleppo but available to anyone with Turkish lira. The scarcity shortage distinction was not useful. The real question was always about currency and access. Even in normal markets, this framework has blind spots. It does not account well for speculative hoarding, which creates artificial scarcity that behaves like real scarcity but disappears rapidly once speculation reverses. It does not handle quality deterioration over time, which can turn a shortage into a scarcity as usable inventory degrades. And it completely fails when geopolitical events abruptly reshape global supply chains in ways that neither production capacity nor regulatory analysis can predict.
The practical takeaway is that scarcity and shortage diagnosis should be treated as a starting point for strategy rather than a definitive conclusion. The most effective supply chain professionals I have worked with constantly revised their diagnoses as new information emerged. They understood that the label they applied to a supply problem determines the tools they reach for, and reaching for the wrong tool is more costly than not having a label at all.
