Understanding how Schedule C income actually gets calculated
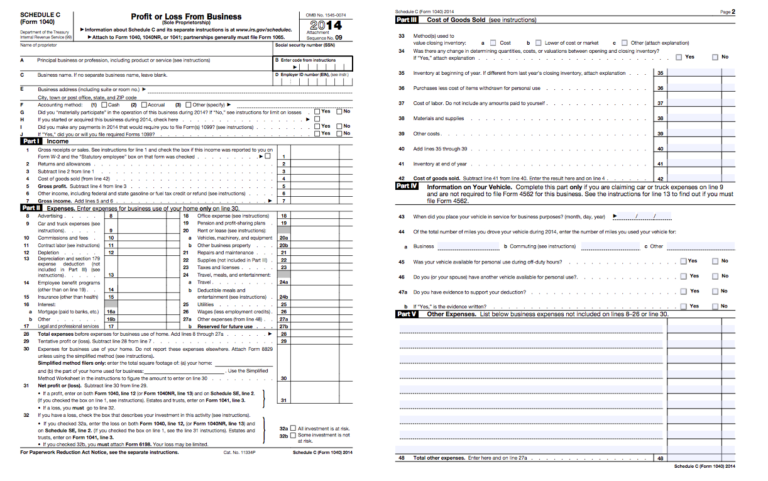
The Schedule C Income Calculation Worksheet is basically a piece of paper that keeps you from making arithmetic mistakes when figuring out your self-employment profit. The IRS form itself is fine, but the worksheet sits between your raw numbers and the final figure you carry onto your 1040. It catches the stuff that trips people up, like gross receipts minus returns and allowances, then subtracting business expenses that fall into specific buckets. Without one, you either overstate or understate your net profit, and both options have consequences. Start with your total gross income. This is the money that came in before anything was taken out. If you ran a freelance design business and invoiced $84,000 in a year, that's your starting line. Then subtract any returns, refunds, or chargebacks. If a client disputed a $2,000 invoice and you gave the money back, your adjusted gross income drops to $82,000. That number matters because every expense ratio downstream is built on it. Next, list your deductible business expenses by category. Advertising, contract labor, supplies, vehicle expenses, home office deduction, insurance premiums, and depreciation are the usual suspects. I keep a running spreadsheet during the year so I'm not digging through receipts in April. When I fill out the worksheet, I total each category separately before plugging the numbers in. The form asks for certain totals on specific lines, and mixing categories up will throw off your final calculation. A common workflow is to write the gross income at the top, stack your expense subtotals beneath it, and subtract everything in one clean pass.
One edge case that I ran into recently involved a client who had both W-2 income and self-employment income in the same year. They tried to offset their Schedule C losses against their W-2 wages using the worksheet, which is not how the form works. The worksheet shows your net profit or loss from the business, but that loss only offsets other income on the main 1040, and it may be subject to the basis at-risk rules if there are debts involved. I had to restructure the numbers and make sure the loss was properly reported on Form 1040 Schedule 1 instead. The worksheet itself is correct, but people misuse it when they think it does more than just summarize business income and expenses.
A detail most beginners miss about net profit calculation
The worksheet result feeds into your adjusted gross income, but it also determines your self-employment tax. The math is straightforward until you hit the 92.35 percent adjustment. You do not pay self-employment tax on your full net profit. You multiply the Schedule C net profit by 0.9235 first, and then apply the SE tax rate. That adjustment exists because the law treats the employer portion of Social Security and Medicare as a deductible business expense, even though you are both employer and employee. I have seen several people skip this step and calculate SE tax on the full amount, which overstates their tax liability by a few hundred dollars depending on the profit level. Another counter-intuitive point is that vehicle expenses can be calculated two ways: the standard mileage rate or actual costs. The worksheet does not decide which method you use, but the method you pick affects your net profit and therefore your self-employment tax. If you drove 14,000 miles in the year and used the standard mileage rate, the calculation is simpler and uses the IRS published rate. If you tracked gas, oil, repairs, insurance, depreciation, and parking, the actual cost method usually requires more documentation but sometimes yields a higher deduction. I switched one of my clients from actual costs to the standard mileage rate after comparing the two numbers, and the mileage method produced a better outcome while cutting the record-keeping burden by about half.
Get the Full Details
Where the worksheet falls short
The Schedule C Income Calculation Worksheet is useful, but it is not a complete compliance tool. It does not handle multi-entity situations, passthrough allocations, or international income reporting. If you operate through an LLC that elects partnership treatment, the worksheet on Schedule C is the wrong form entirely. You would be working with K-1 schedules and a separate set of calculations. The same applies if you have rental real estate income, which goes on Schedule E, not Schedule C. I have watched people try to force rental repairs into the Schedule C worksheet and end up with incorrect deductions that the IRS flags during review. The worksheet also does not account for the qualified business income deduction under Section 199A. That deduction is claimed on your individual return and depends on your taxable income, business type, and whether you are in a specified service trade. It interacts with your Schedule C net profit, but it is calculated elsewhere. Relying on the worksheet alone will not show you your total tax position.
A practical note on documentation
Keep bank statements, invoices, receipts, and mileage logs alongside your worksheet calculations. The worksheet itself is not required to be filed with your return, but the numbers on it should match the numbers you report on Schedule C. If the IRS asks for supporting details, a cleanly completed worksheet makes it easy to trace each figure back to its source. I recommend saving a PDF copy with timestamps after you finish each year's worksheet. It saves time if you need to reference a prior year's numbers or reconstruct a deduction during an audit.