Understanding the Schedule E Worksheet for Rental Property
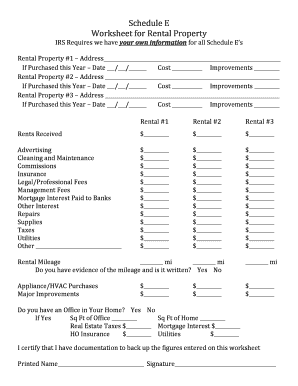
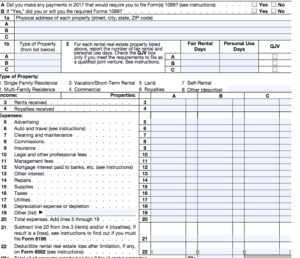
Most people who fill out Schedule E for rental income do it with a worksheet tucked into their tax prep software or a PDF they found online. The IRS doesn't actually require a worksheet. They require the Schedule E form itself. But the worksheet is where the actual work happens before anything gets transferred onto the official form. Without it, you'll be staring at line 13 with no idea where the numbers came from. The worksheet is essentially a tracking document. It captures every income item and every deductible expense so that when you sit down to fill out Schedule E, everything is already organized and totaled. You can build your own in a spreadsheet, buy a dedicated rental property worksheet, or use one that comes packaged with your tax software. The format varies but the data requirements are the same. You need to track gross rents received, security deposits that were actually kept as income rather than returned, parking fees, pet fees, laundry income, and any other money a tenant paid you during the tax year. Then on the expense side you are logging advertising, repairs, utilities, insurance, property taxes, mortgage interest, depreciation, property management fees, and legal or professional services. Each category needs its own column or section so that the totals flow cleanly into the corresponding Schedule E lines.
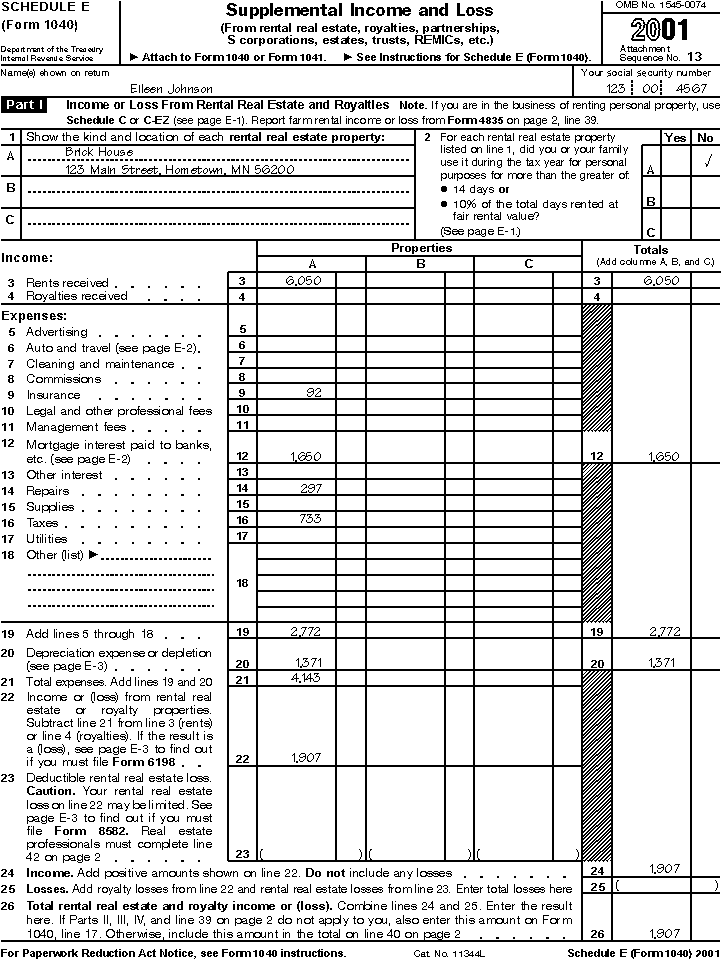
Here is where it gets specific. Line 4 of Schedule E is for supplies, line 6 is for repairs, and line 8 is for depreciation. Beginners routinely dump supplies into repairs because both are deductible and the distinction seems minor until the IRS notices a $4,000 "repair" that was actually a new HVAC system. That is a capital improvement, not a repair. A proper worksheet forces you to separate them because you have to categorize each expense upfront. If you keep it all in one bucket you will make this mistake every single time.
Building Your Own Worksheet
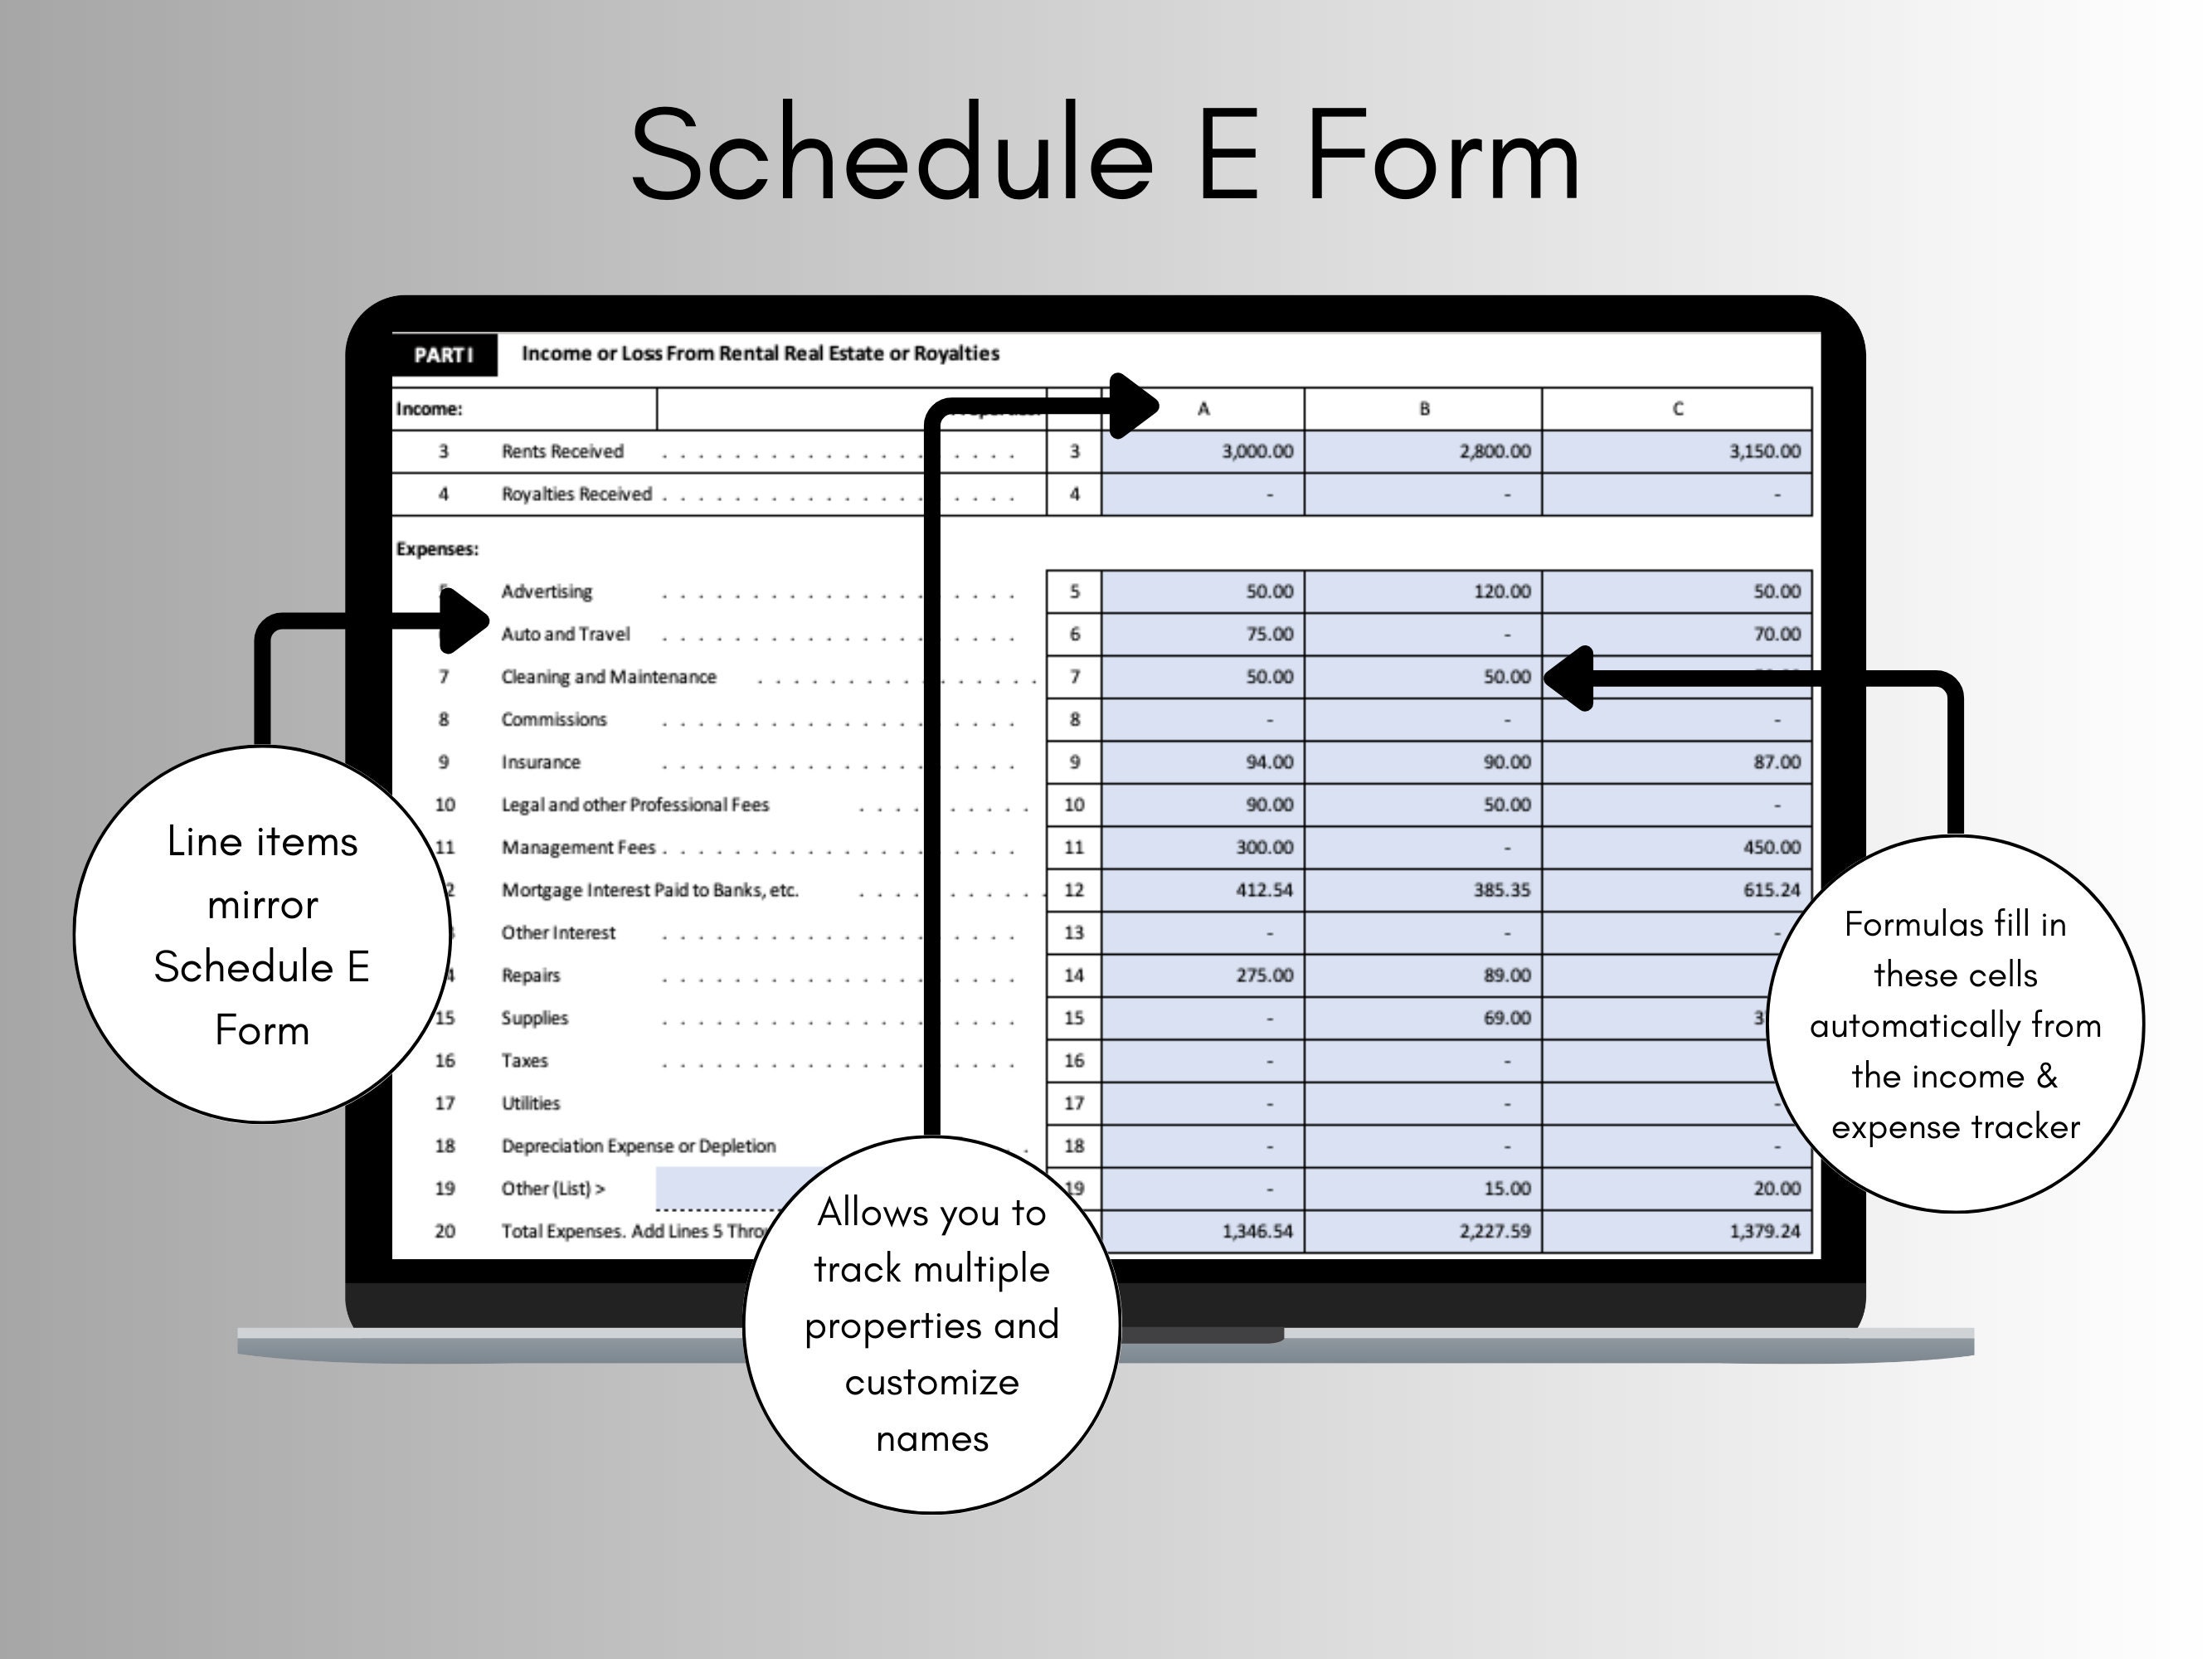
Setting up a spreadsheet is straightforward and usually takes about twenty minutes if you already use Excel or Google Sheets. Create columns for date, vendor or payer, description, amount, and category. Assign each category to a Schedule E line number so you never have to guess during tax season. The categories should match the form exactly: advertising goes to line 5, repairs to line 6, supplies to line 4, insurance to line 7, property taxes to line 8, mortgage interest to line 9, depreciation to line 18, and so on. I used to keep a separate sheet for each rental unit. That worked fine for one or two properties but when I had four units with different tenants paying through different payment platforms, the sheets multiplied and I lost track of which totals went where. I switched to one master sheet with a property column. Every expense gets tagged with the property it belongs to, and then I use a pivot table or simple filter to pull totals per property whenever I need them. That process cuts my prep time down to roughly fifteen minutes per property instead of the hour or more it used to take me digging through mismatched spreadsheets. If you are using tax software, the worksheet is often automatic. TurboTax, Drake, and Lacerte all generate a rental income and expense summary as you enter data. The tradeoff is that you lose visibility into exactly where each number comes from unless you go back and audit the entry screen. I recommend keeping a parallel spreadsheet even if you use software. It gives you a backup in case the software miscalculates something or you need to justify an expense during an audit. Software errors happen more often than people expect, especially with depreciation calculations.
Get the Full Details
Common Mistakes That Create Problems Later
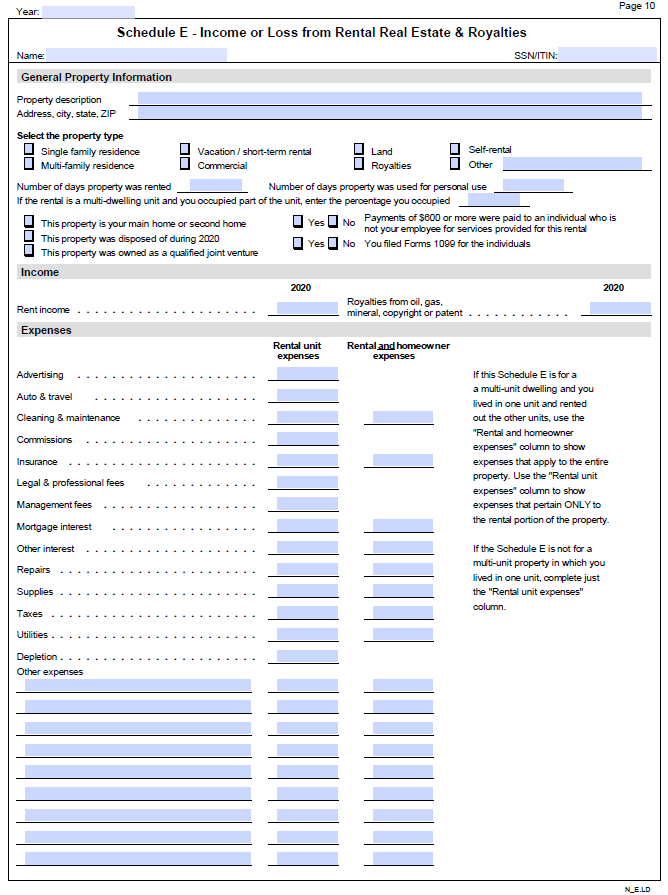
The biggest error I see involves personal use of a rental property. If you use the property yourself for more than the greater of fourteen days or ten percent of the days it is rented at fair market value, the deductions get severely limited. You have to allocate expenses between rental and personal use based on square footage or days used. I once had a client who forgot he stayed in his vacation rental for three weeks in July while his tenant was on an extended lease. He had claimed 100 percent of the utilities and maintenance as rental expenses. That triggered a red flag on the return. The fix required recalculating everything on a day-use basis and amending the return, which cost him about three hundred dollars in additional filing fees and several hours of my time trying to reconstruct the expense allocation from bank statements that were months old. Another frequent problem is mixing home office deductions with rental property deductions. The home office deduction belongs on Form 8829, not Schedule E. If you use a portion of your home to manage your rental properties, that expense goes on Form 8829 and then a portion may flow to Schedule E depending on how you structure things. I have seen people skip Form 8829 entirely and just slap a home office number onto Schedule E. The IRS does not care about your convenience. They will disallow it and potentially assess penalties if they catch it. Depreciation is where most people get tripped up on the worksheet. Residential rental property is depreciated over twenty-seven point five years using the straight-line method. The land itself is never depreciated. When you acquire a property, you must separate the land value from the building value. The worksheet should have a dedicated section for depreciation with columns for the basis, the land portion, the building portion, the placed-in-service date, and the annual depreciation amount. If you skip this section and just throw a depreciation number on the form without the supporting calculation, you will either get it wrong or fail to document it properly if audited.
Passive activity loss rules are another area that surprises people. Rental income is generally considered passive income, which means losses can only offset passive income unless you qualify for the special $25,000 allowance for active participants. That allowance phases out between $100,000 and $150,000 of modified adjusted gross income. If you do not understand these rules, your worksheet might show a large rental loss that you assume you can use to reduce your ordinary income. It does not work that way. The loss carries forward to future years whether you realize it or not. I learned this the hard way when a client realized three years after filing that his rental losses were suspended and he had no idea why his tax bill was higher than expected each year. The worksheet he was using did not include a column for passive loss carryover, so the problem was invisible until the amendment process.
What the Worksheet Should Look Like in Practice
A functional worksheet has a summary section at the top showing total rental income and total deductions, a detailed expense schedule organized by category, a depreciation calculation, and a section for any adjustments or special rules like the passive loss limitation. Each property gets its own block if you have multiple units. The data should be entered throughout the year, not dumped in all at once in April. I recommend entering expenses monthly or at least quarterly. Waiting until tax season means receipts are scattered, memories are fuzzy, and you are working under a deadline with incomplete information. Income tracking deserves equal attention. Gross rents include everything a tenant pays you, even if you issue a refund later. Security deposits are not income unless you keep them permanently due to damage or lease violation. Advance rent payments are income in the year received regardless of the period they cover. If a tenant pays you in December for January rent, that December payment is income on your Schedule E for that tax year. This is a common source of errors because people want to match the payment to the month it covers rather than the month it was received. The tax rule is clear on receipt date. The worksheet should reflect this by capturing income when it is received, not when it applies.
Download and Template Sources
The IRS does not publish a standalone Schedule E worksheet. What they do provide is the Schedule E form itself with instructions that include examples of how to calculate certain lines. Many tax professionals and accounting firms create their own worksheets based on the IRS instructions. You can find free templates on sites like Nolo, Investopedia, and various accounting blogs. Paid options from major tax software providers usually come bundled with the software rather than sold separately. If you want a free, reliable starting point, the IRS Schedule E instructions PDF is the best reference document available. It includes sample calculations and explains each line in enough detail to build a working spreadsheet from scratch. For those who prefer a ready-made template, several third-party sites offer downloadable Excel files that are structured around Schedule E line numbers. These vary in quality, so before you rely on one, verify that the categories match the current IRS form. Tax forms get updated occasionally and a template from two years ago might still have old line numbers or missing categories. Cross-reference any template you download against the current year's Schedule E form before entering your first dollar of data.
When a Worksheet Is Not Enough
A worksheet organizes your data but it does not solve complex problems. If you are dealing with like-kind exchanges, casualty losses, partnership rentals, or properties acquired through inheritance, the worksheet becomes inadequate because those situations require additional forms and calculations that do not fit into a simple income-and-expense grid. A like-kind exchange under Section 1031 defers gain recognition and requires Form 8824. Casualty losses need Form 4684. Partnership rentals need to flow through a K-1 and may involve basis adjustments. In these cases the worksheet is still useful as a supplementary tracking tool, but you cannot rely on it alone to produce a correct return. The real limitation of any worksheet approach is that it assumes your records are complete and accurate. If you are losing receipts or mixing personal and business bank accounts, no amount of spreadsheet formatting will save you from incorrect deductions. I have worked with clients who claimed thousands in expenses that turned out to be personal costs once their bank statements were pulled for verification. The worksheet made it look organized. The underlying data was wrong. The solution is maintaining clean separation between personal and rental finances from the start, not rearranging bad data into a prettier format. If you have a small number of rental properties with straightforward expenses, a well-organized worksheet in a spreadsheet program will handle the task efficiently. If your situation involves multiple properties, contractors, depreciation schedules, or any passive loss complications, you are better off working with a tax professional who can integrate the worksheet data into the proper forms and catch issues that a standalone spreadsheet will never surface. The worksheet is a tool, not a substitute for understanding the tax rules behind it.