What the Schedule Enrolled Agent Exam Actually Looks Like
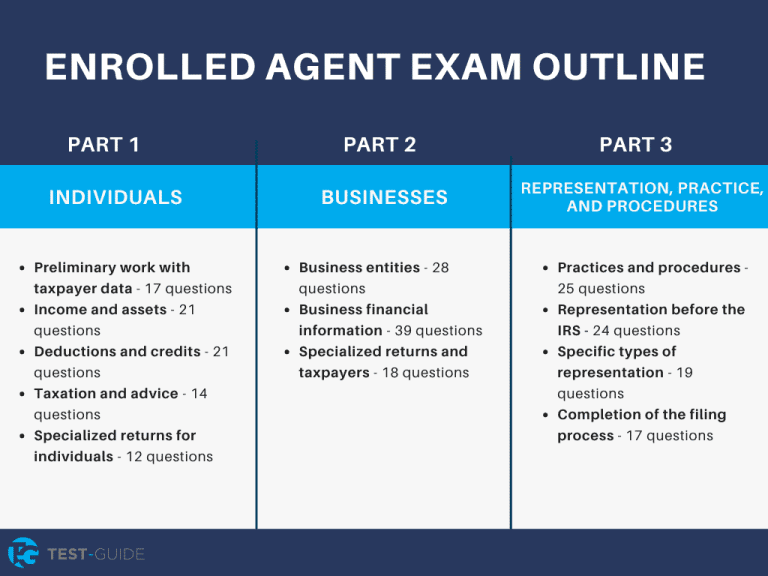
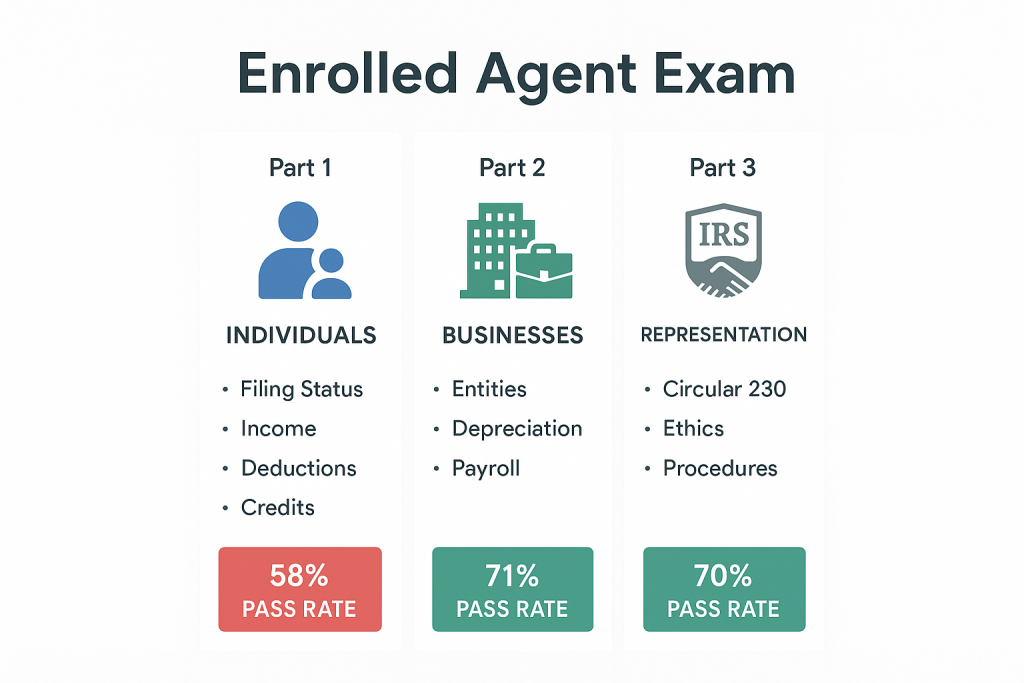
The IRS Enrolled Agent exam is split into three parts, but calling it a "three-part exam" undersells how different each section feels when you sit down to take it. Part 1 covers individuals, Part 2 covers businesses, and Part 3 covers representation, practices, and procedures. The whole thing runs about 3.5 hours total if you push through without overthinking. Most people who fail aren't failing because they don't know the tax code—they're failing because they spend too long on single questions and run out of time on the easy ones at the end. You schedule through the Prometric website, and you pick a test center location that's convenient for you. The exam is computer-based, which means you're clicking through questions on a screen, not filling in bubbles. You get a notepad and a pen at the test center. There's a whiteboard you can request if you need to work through calculations by hand. Don't try to do complex multiplication in your head during Part 2—that's where people lose points. Here's what nobody tells you upfront: each part is scored separately, and you can take them in any order. I've seen people start with Part 3 because it's the most memorization-heavy and easiest to grind through quickly. Then they tackle Part 1 and 2 when they still have mental fuel left. Others do it straight through 1, 2, 3. Both approaches work. The order doesn't affect your score.
You need a score of 650 or higher on each part to pass. The scoring scale runs from 215 to 1575. That 650 threshold sounds low until you realize the questions are designed so that guessing randomly would put you solidly below that line. The average passing score hovers around 1100 to 1200 for people who actually studied. I ran into a weird edge case last year with a client who had taken the exam twice and failed Part 2 both times. She was getting stuck on partnership distributions—specifically, the ordering rules under Section 705 and how basis adjustments cascade through multiple partners with different capital account structures. The official study materials treat this topic in maybe four pages across two chapters. In practice, the exam can throw a multi-step distribution problem at you that requires tracking basis through three separate entities. I had her work through the actual IRS Publication 541 examples and then do five variations where I changed one variable at a time. She passed on her third attempt. The takeaway is that Part 2 partnerships and S corporations are where most people hit their wall, and the study guides massively underweight them. The registration process itself is straightforward. You apply through the IRS website, pay the fee, get your Authorization to Test, and then book your Prometric appointment. The current fee is around $160 per part, so all three will set you back roughly $480. Some people take all three at once. That's possible but brutally exhausting. A two-hour block on Part 1 followed immediately by another two-hour block on Part 2 leaves most people cognitively drained by the time they hit Part 3. Spacing them out over a few weeks is usually smarter.
There's also a credit availability quirk. If you use a tax preparation company to file returns professionally, they may cover some or all of the exam fees as a professional development expense. Check with your employer's HR or education reimbursement policy before you pay out of pocket. I've seen at least one person get the full amount reimbursed after submitting the receipt and a brief note about how the EA credential supports their role.
Get the Full Details
What Each Section Actually Tests
Part 1 is individual taxation. It covers filing status, dependents, deductions, credits, capital gains, retirement accounts, and a handful of other standard individual tax topics. The tricky part is that the IRS updates the tax code every year, so questions about standard deduction amounts, credit phaseout thresholds, and contribution limits will reflect the current tax year. If you're studying from outdated materials, you'll memorize numbers that are already wrong. Make sure your review course is current for the tax year you plan to test in. Part 2 is business taxation. This is where S corporations, C corporations, partnerships, and fiduciary income are tested. It also touches on employment taxes and excise taxes, though those get lighter coverage than the entity-level questions. The depth here is deeper than most people expect. You need to understand not just how to fill out a Form 1120 or 1065, but how the underlying mechanics flow through to the shareholders and partners. Basis calculations, at-risk rules, and passive activity loss limitations come up more often than the study guides suggest. Part 3 is the smallest section by content volume but it's the most procedurally dense. It covers IRS audits, collections, refunds, powers and duties of representatives, and the Code of Federal Regulations title that governs practice before the IRS. You need to know what documents you can sign, what you can't, how the Statutory Penalty Framework works, and the difference between a summons and a notice. This section rewards rote memorization. If you can memorize the key timelines and thresholds, you can pass Part 3 without deeply understanding the underlying theory. That's unusual for a tax exam, but it's how the questions are structured.
One counter-intuitive point about Part 3: many people assume it's the easiest part because it's mostly memorization, but the questions are written to be deliberately ambiguous. A typical question will describe a scenario where two procedural rules seem to apply simultaneously, and you have to pick the one that takes precedence. The answer choices are all technically defensible. You're looking for the most correct answer, not the only correct answer. This trips up people who are used to black-and-white testing formats.
Studying Efficiently
The review courses available range from free IRS-produced materials to expensive prep programs that run a few hundred dollars. The IRS publishes a comprehensive study guide for free, but it's essentially a textbook. It explains the rules without giving you the exam-style questions you'll see. A paid review course fills that gap with practice questions and timed exams. The biggest mistake people make is studying passively. Reading the material isn't enough. You need to do problems under timed conditions. The exam is a speed test as much as a knowledge test. I recommend doing at least 50 practice questions per section before you schedule your exam date. If you can't comfortably score above 75% on timed practice sets, you're not ready. Pushing through unprepared wastes the exam fee and the time. Another overlooked detail: the Prometric testing system allows you to flag questions and come back to them later. Use that feature. If a question takes more than 90 seconds to read and think through, flag it and move on. Most people who fail do so because they get locked into hard questions early and then panic through the easy ones at the end. The easy questions are worth the same points as the hard ones.

For Part 2 specifically, I recommend creating your own reference sheet of the key formulas and ordering rules before the exam. Writing them out by hand reinforces the memory. The notepad you get at the test center is scratch paper—you can't take it with you after the exam. But you can transfer your personal reference sheet notes onto it during the exam if you want. Just don't bring your own paper into the testing room.
On the Day of the Exam
Arrive at the test center 15 minutes early. Bring two forms of ID, one of which must be a government-issued photo ID. The name on your ID has to match the name on your Authorization to Test exactly. I've seen people turned away because their license said "Robert" and their registration said "Rob." It happens more often than you'd think. The testing room environment is generic and uninspiring. Climate control varies by location. Some centers are too warm, some too cold. Bring a light layer just in case. You'll be allowed a bottle of water and a snack, but nothing with a strong smell. Don't bring anything that could be construed as a communication device. Phones, smartwatches, and Bluetooth headphones are confiscated at check-in. When you sit down at the computer, you'll get a brief tutorial on how to navigate the interface. It takes about three minutes. Learn it quickly. The navigation buttons are straightforward, but if you accidentally submit an answer and move on before realizing you made a mistake, you can't go back. The flagging system is your safety net, so use it proactively.
After you finish each part, you'll get an unofficial score right there at the test center. It's not the final score, but it's usually within 10 to 20 points of the official result. If you pass, congratulations. If you don't, you can retake the part after 24 hours. There's no penalty for multiple attempts, but each retake costs the full fee again. The official scores come back within a few weeks through your IRS online account. Once you've passed all three parts, you'll receive your Enrolled Agent credential and your PTIN will be updated to reflect your EA status. From there, you're authorized to represent taxpayers before the IRS on any matter, anywhere in the United States. That's the main practical benefit—the unrestricted representation rights that come with the designation. A final note on study strategy: don't underestimate the value of doing full-length practice exams that simulate the actual testing conditions. Sitting for two hours straight without breaks is harder than it sounds. Your focus degrades. Building that stamina beforehand prevents surprises on exam day.