Working Through Schumer Boxes Without Losing Your Mind
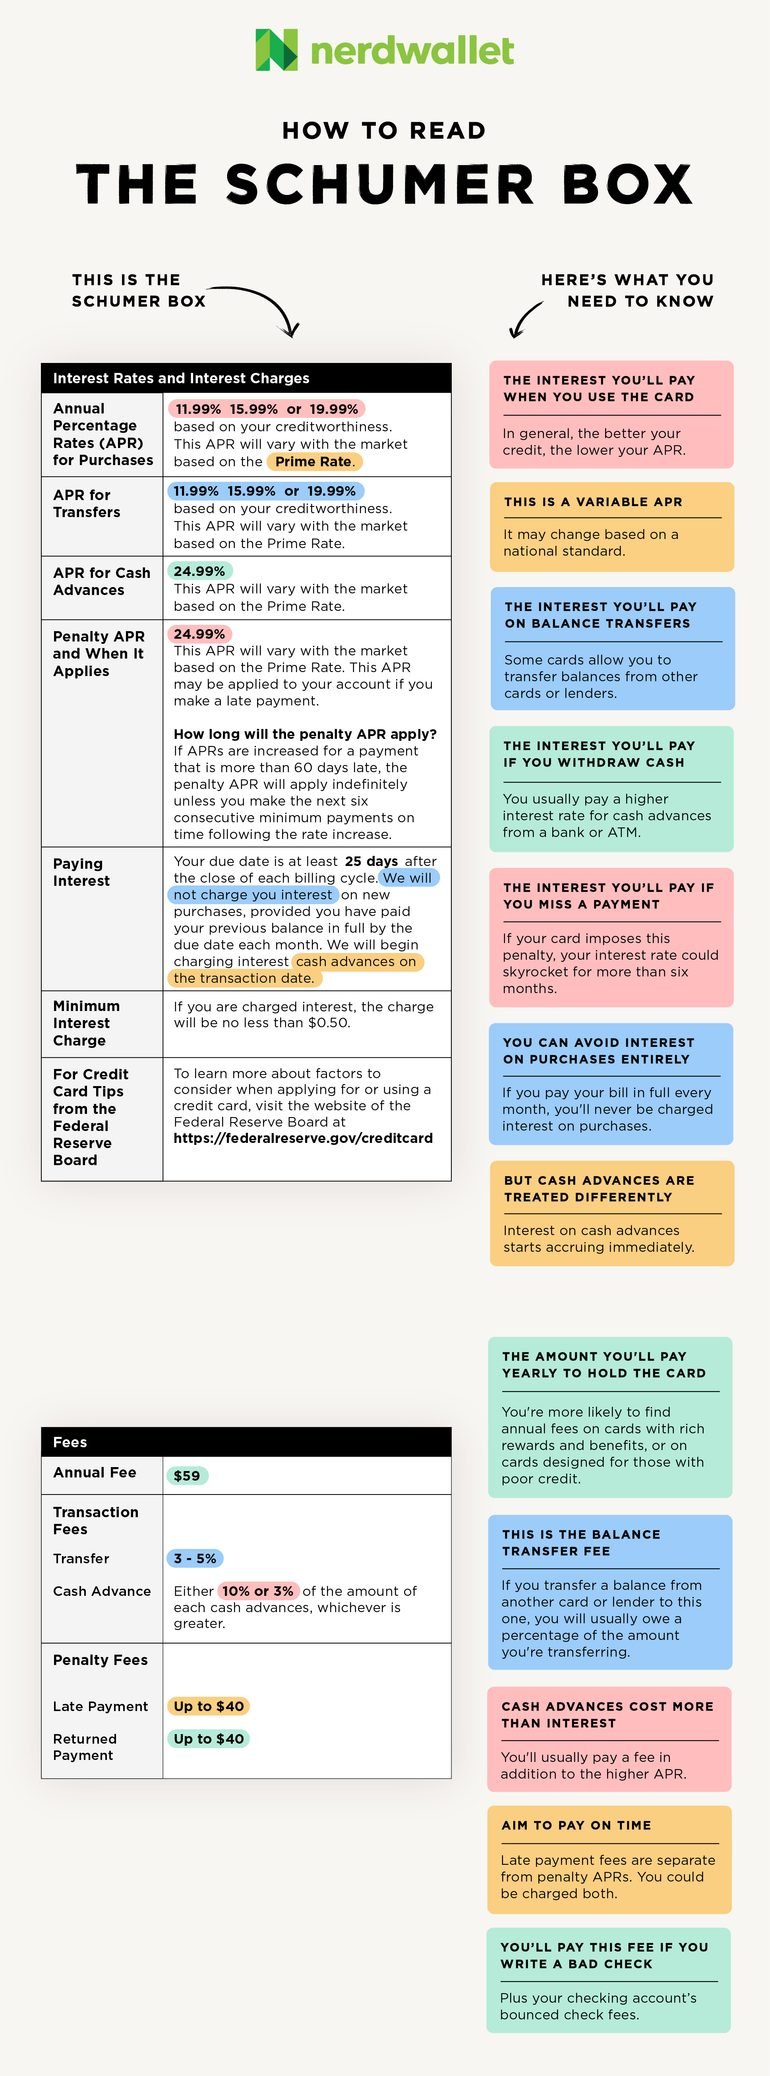
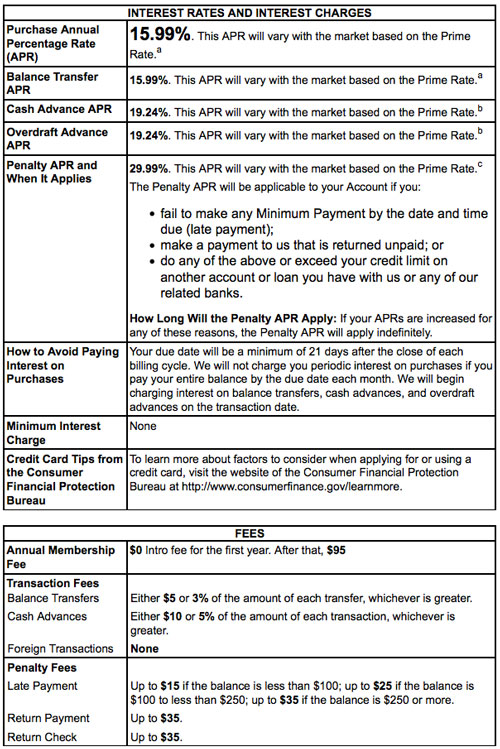
The Schumer box is a regulated disclosure table you see on credit card and deposit account agreements. It lays out APRs, fees, grace periods, and other cost factors in a grid format so consumers can compare products side by side. The "answer key" concept comes up when you're either studying for a compliance exam, training new underwriters, or trying to reverse-engineer what a particular box entry actually means for your monthly statement. People looking for a Schumer Box Answer Key usually want to verify calculations, understand how an effective rate is derived, or confirm whether a bank has rounded something incorrectly. Let me walk through how these boxes actually function in practice rather than starting with a dry definition. I spent years reviewing disclosure documents for regional banks, and the thing nobody tells you is that most errors are subtle rounding differences, not outright lies. A bank might show a 19.99% regular APR in the box but the actual daily periodic rate used to compute your finance charge is 19.9873%. The box rounds to two decimals, the calculation engine doesn't. That gap matters when you're auditing statements across hundreds of accounts. To read a Schumer box efficiently, start with the APR field and work downward. The APR is annual percentage rate, not the same as the nominal rate because it includes certain fees in the calculation for certain products. For credit cards, the APR shown must reflect the cost of mandatory insurance or membership fees if those are rolled into the rate. For savings accounts, the APY — annual percentage yield — accounts for compounding frequency, which is why it's always slightly higher than the nominal interest rate. This distinction trips people up constantly.
Here's a practical example I deal with regularly. You get a credit card disclosure showing a purchase APR of 24.99%, a balance transfer APR of 29.99%, and a penalty APR of 29.99%. The grace period column says zero days. On the surface this looks standard, but when I pull the actual daily periodic rate from the billing statement, it's 0.06569% per day. Multiply that by 365 and you get 23.98%, not 24.99%. The difference is because the APR in the Schumer box includes the annual account maintenance fee amortized across the year. If you ignored that fee, your effective cost of borrowing would be lower. Most people don't notice this. When you're building an answer key or checking someone else's work, here's the workflow I use. Pull the periodic rate from the box, multiply by the number of periods in a year, and verify it matches the stated APR within acceptable rounding tolerance. For APY, take the formula (1 + r/n)^n - 1 where r is the nominal rate and n is compounding periods per year. If a bank advertises 4.50% APY with daily compounding, the nominal rate should be approximately 4.40%. If their stated nominal rate is 4.50% and they claim 4.50% APY too, they're either compounding annually or they've made a mistake in the box. I've seen both. One counter-intuitive thing about Schumer boxes: the order of entries doesn't follow any universal logic. Some issuers put the balance transfer APR before the purchase APR. Some list cash advance fees first, some last. The regulatory requirement only specifies what fields must be present, not their arrangement. When I'm creating an answer key for a training program, I alphabetize the fee categories rather than following the issuer's layout. It saves hours of cross-referencing.
Another nuance that beginners consistently miss is the difference between the introductory APR and the ongoing APR. The box must display both, and both have start and end dates. I once caught a community bank that had an introductory 0% APR box listing an end date that had already passed but hadn't updated the disclosure. The customer was being charged the penalty rate on a balance that had been qualifying for the intro rate for eighteen months. The fix was straightforward — file a corrected disclosure and recalculate the interest, but catching it required manually checking every date field against the current calendar. Doing this for fifty different account types across three banking products took me about four hours. Doing it mentally without a checklist would have taken considerably longer and I'd have missed something. Now for the limitations. Schumer boxes are only as useful as the data entered into them. A bank can present every field correctly and still make the product expensive through fees that don't appear in the box at all. Out-of-network ATM fees, returned payment charges, foreign transaction fees — some of these are disclosed elsewhere in the agreement, not in the grid. The box itself doesn't tell you the overlimit fee structure unless the issuer chooses to include it, and the regulations have shifted on whether that's mandatory. As of my last review of the current rulebook, overlimit fees require affirmative consent, but the disclosure requirements around that consent process aren't always reflected in the box format. If you're studying for a certification like the CRCM or CCCA, the Schumer Box Answer Key you find online tends to focus on the standard textbook cases. Real disclosures are messier. You'll encounter boxes that reference multiple rate tiers based on credit score ranges, variable-rate products where the index and margin are disclosed separately from the current rate, and hybrid products that combine features of checking and savings accounts with their own unique disclosure requirements. The answer key approach works for exams but falls apart in production environments.
Get the Full Details
For a quicker practical workaround when you're drowning in disclosure documents, I keep a spreadsheet with columns for product type, APR range, fee schedule, and compounding frequency. When a new Schumer box lands on my desk, I populate the row and flag any field that deviates from the bank's historical pattern. This catches changes faster than reading each box from scratch. A rate that jumps from 18.99% to 24.99% without a corresponding index change gets my attention immediately. A balance transfer fee that drops from 5% to 3% while the APR goes up is another red flag worth investigating. These pattern mismatches are where the real compliance risk lives, not in the individually correct fields. The bottom line is that a Schumer box is a starting point, not the complete picture. The answer key helps you verify what's there, but the actual cost to a consumer depends on usage patterns, fee triggers, and how the institution applies daily periodic rates to outstanding balances. If you want to understand a product's true cost, read the box, then read the full agreement, then run a hypothetical transaction through both and compare the results. That's the method that actually works.