What Actually Happens When You Run the Numbers
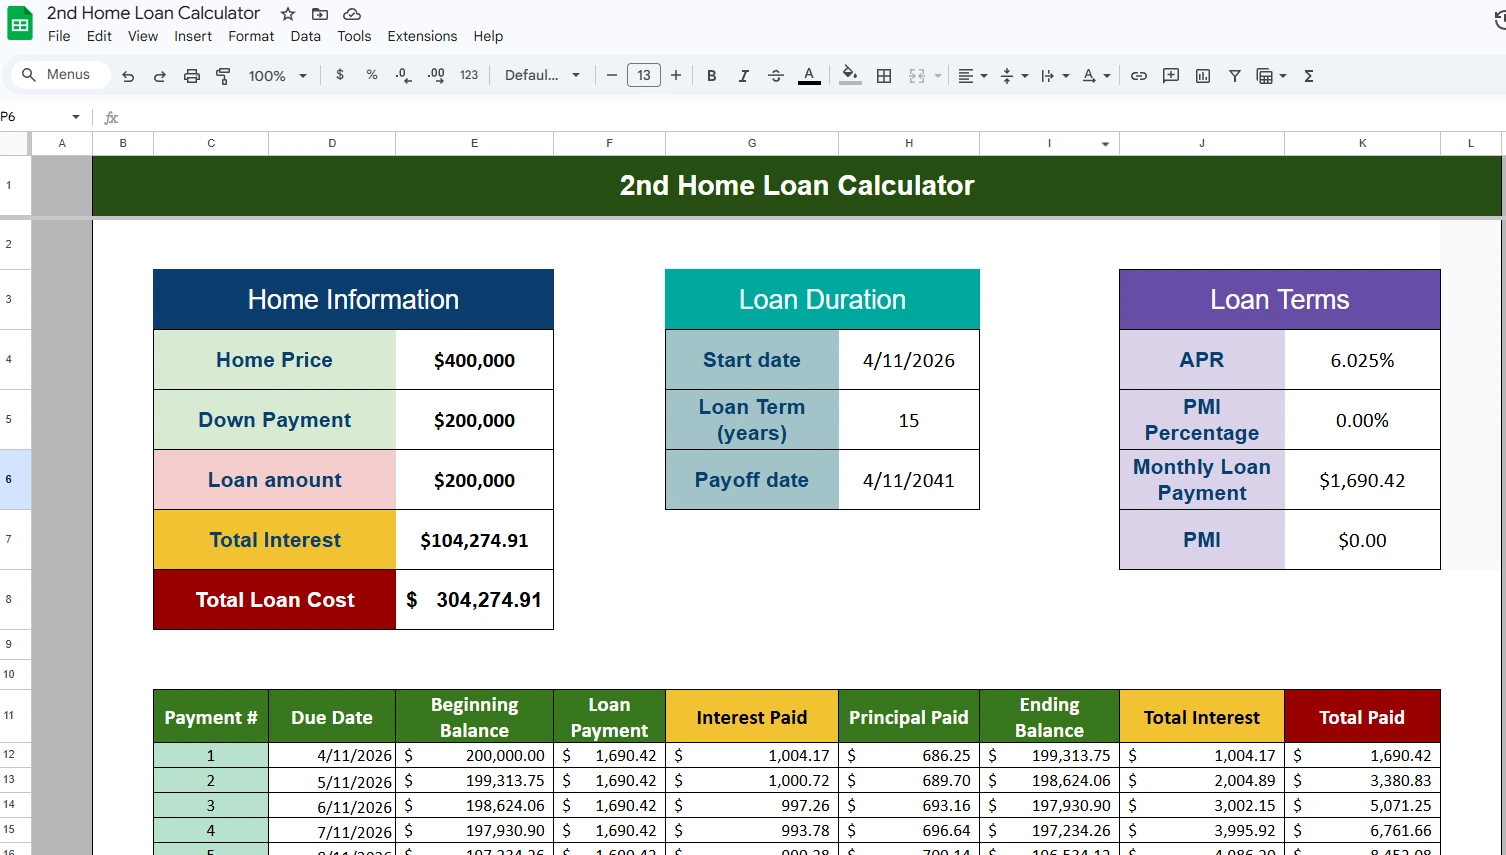
A second mortgage calculator free is just a tool that takes your home equity, existing first mortgage balance, and interest rate assumptions to spit out estimated monthly payments for a home equity loan or HELOC. That's it. The results are only as good as the inputs you feed into them, and most people don't realize how much a half-percent difference in rate assumptions can swing their payment by hundreds of dollars. I spent years working residential lending and one thing I noticed constantly: people would run these calculators, see a payment number, and treat it like gospel. Then they'd show up to a lender appointment surprised when their actual quote was different. The gap usually comes from the calculator ignoring things like property taxes, homeowners insurance, and PMI, which a real monthly payment includes.
How to Actually Use a Second Mortgage Calculator Free
Grab any free calculator on the web and you'll see a handful of fields. Here's what you need to have ready before you start typing numbers, because switching tabs mid-calculation ruins your focus and you'll forget what you entered. Your current first mortgage balance. Not your original loan amount. Look at your most recent statement or log into your servicer's online portal and grab the actual payoff figure. A lot of homeowners think they owe less than they do because they forget about the negative amortization or the fees that rolled into the balance during refinancing. Your home's current market value. This is trickier than it sounds. Zillow estimates are wrong about fifteen percent of the time depending on your market. If you're in a volatile area, check what comparable homes actually sold for in the last sixty days, not what they're listed at. Listed prices are aspirational. Sold prices are reality.
Your target loan amount and preferred term. Second mortgages typically run seven to fifteen years for home equity loans and then there's the HELOC draw period, usually ten years, followed by a repayment period. The calculator should let you toggle between these. Pick one and stick with it while you compare scenarios. Once you have those numbers, plug them in. Run the calculation at two or three different interest rates around the current market rate, not just the one posted on the homepage. Rates move daily and the first result you see is rarely the one you'll actually qualify for.
Get the Full Details

The Gap Between Calculator Output and Real Life
Here's where it gets complicated in a way nobody tells you about. The monthly payment the calculator shows you for a second mortgage is only the principal and interest portion. Lenders require escrow for property taxes and homeowners insurance on top of that, and if your total loan-to-value ratio crosses eighty percent, you'll likely get slapped with private mortgage insurance whether you realize it or not. I had a client once who used a Second Mortgage Calculator Free and saw a payment of nine hundred and forty dollars a month on a seventy-five thousand dollar second lien. She budgeted accordingly, got approved, and then her actual monthly statement came in at fourteen hundred and twenty dollars. The calculator hadn't included the tax escrow, the insurance escrow, or the PMI, which added roughly four hundred and eighty dollars to her payment. She was underwater on her cash flow before she even moved furniture into the new place. Another thing the calculator won't tell you: the order of the liens matters. A first-position second mortgage, which is rare but possible in some creative financing situations, carries different risk pricing than a standard second lien position. Lenders price second mortgages based on their position in the repayment hierarchy, and a free calculator doesn't account for that nuance at all.
Edge Cases That Break Most Free Calculators
Free calculators assume simple interest amortization. They do not handle balloon payments, which are surprisingly common with second mortgages from community banks and credit unions. If your loan has a five-year amortization schedule with a three-year balloon, the calculator will show you a monthly payment that looks affordable and then hit you with a lump sum you never planned for. Always confirm the amortization term versus the actual loan term before you rely on the output. HELOCs compound a different problem entirely. The initial draw period often has an interest-only payment option, and the calculator might show you that lower number first. Then the payment recalculates when the draw period ends and your principal starts amortizing over the remaining term. That payment can double or triple overnight. I've seen borrowers caught off guard by this more than once. When you're modeling a HELOC scenario, run the calculation for both the interest-only phase and the full amortizing phase so you know the worst case. There's also the issue of close costs. Free calculators don't factor in closing costs, which for a second mortgage can range from fifteen hundred to five thousand dollars depending on the lender and whether you negotiate them away. If you're comparing a second mortgage against a cash-out refi of your first mortgage, you need to include those costs in your comparison or the analysis is meaningless.
What to Do When the Calculator Isn't Enough
When your situation involves unusual features like prepayment penalties on your existing first mortgage, assumable loans, or a property with mixed-use zoning, the calculator is going to give you a rough sketch at best. In those cases, the workaround I always recommend is getting a manual quote from a lender who will walk you through the actual terms before you commit. The calculation takes ten minutes and it saves you from making a decision based on incomplete data. If you're just trying to gauge whether a second mortgage makes sense for your budget, running the numbers through a Second Mortgage Calculator Free is a reasonable first step. Just remember to add the escrow and insurance costs yourself and compare the result against what multiple lenders are actually offering you. The market rate on second mortgages varies significantly between institutions, and the cheapest rate isn't always the cheapest loan when you account for fees and terms. The single most useful thing you can do after running the calculator is call two or three local lenders and ask for a loan estimate. It's free, it takes about twenty minutes of your phone time, and it will immediately show you whether the calculator's numbers are in the ballpark or completely off. That comparison usually reveals more in an hour than any tool can tell you on its own.