How Second Mortgage Interest Rates Actually Work in Practice
Most people think second mortgage interest rates are just a fixed number you look up and pay. They're not. The rate you get depends on a messy stack of factors that lenders weigh differently, and understanding how that stack actually works saves you money faster than shopping around alone. I've sat through enough closings and broker calls to know the difference between what the sheet says and what you actually pay. Here's how the calculation really plays out.
Understanding Second Mortgage Interest Rates
Second mortgage interest rates are typically 1 to 3 percentage points higher than your first mortgage rate. That gap exists because the second lien sits behind the first in priority if you default. The lender taking the second position is taking more risk, so they charge more for it. Simple enough on paper. The complications start when you look at how each lender prices that risk. The most important number you need to track is the combined loan-to-value ratio, or CLTV. This is the total of both mortgages divided by the appraised value of the home. Most conventional second mortgages cap out around 85% CLTV. Some jumbo lenders will go to 90%, but you'll pay a premium for that extra room. If you're at 91% CLTV or above, you're looking at subprime pricing or outright denial from most conventional programs. Here's something most people miss: the interest rate on your first mortgage matters almost as much as your credit score when it comes to the second mortgage price. A lender seeing a first mortgage at 7.5% will often price the second mortgage tighter than if your first is sitting at 4.2%. The reasoning is straightforward. A higher first mortgage rate usually means the borrower has carried that loan longer and has more equity built up, which signals stability. A low first mortgage rate often means a recent refinance, which means the borrower might be cashing out equity they don't really have. Lenders penalize that behavior.
The Pricing Factors That Actually Move the Needle
Credit score is the first factor everyone checks, and it matters, but not in the way you probably think. The jump from 740 to 760 might save you two-tenths of a point. The jump from 680 to 700 could save you half a point or more. The curve is steeper at the lower end. If your score is in the high 600s, boosting it to 700 before applying is worth the effort. I had a client last year who sat at 672 and was getting quoted 10.75% on a HELOC. We spent six weeks cleaning up two late payments on utility bills and correcting a credit report error that showed a medical collection already paid off. Score went to 708. The rate dropped to 8.25%. That's a difference of over four thousand dollars per year on a hundred thousand dollar line. Debt-to-income ratio is the second factor, and it's where a lot of people get tripped up. Lenders look at your front-end ratio (housing costs only) and your back-end ratio (everything). For a second mortgage, the back-end ratio is what matters. If you're already at 43% and applying for a second mortgage, you're in conventional territory. Above 50%, you're dealing with non-QM lenders, and those rates can jump to 11% or higher depending on the program. Occupancy status changes the pricing tier entirely. Owner-occupied gets the best rates. Second home gets worse. Investment property gets the worst. The spread between owner-occupied and investment property can be a full percentage point or more. I once worked with a borrower who owned two rental properties and wanted a second mortgage on his primary home. He told the broker he was moving into one of the rentals as a second home. The rate quoted was 9.125%. We corrected the occupancy declaration before appraisal, and it came back to owner-occupied at 7.375%. Same credit score, same LTV, same income. The rate dropped almost two points because of a factual correction, not because of any financial change.
Get the Full Details
How to Shop This Without Wasting Your Time
Don't apply to five lenders in a thirty-day window. Hard inquiries pile up and temporarily ding your score. One credit pull for the first mortgage and one for the second is the limit. If you need a third, try to structure it as a rate lock extension rather than a new application. Get rate quotes from at least three sources: a regional credit union, a national mortgage broker, and the bank where your first mortgage already sits. The existing lender often matches or beats third-party rates on second mortgages because they already have your full financial file. It cuts the documentation time significantly. The credit union will usually have the lowest rate if you're a member, but their closing timeline can be slower. The broker gives you access to wholesale pricing you can't get on your own, but you're paying them a yield spread premium that's baked into the rate. When you're comparing quotes, make sure they're apples to apples. Look at the note rate, the APR, and the total closing costs. Two loans can have the same note rate but dramatically different APRs because of how fees are structured. A lender charging zero points upfront might bury three percent in origination fees. Another might charge one point but keep origination under half a percent. The APR number already accounts for all of this, so that's your real comparison metric.
Where Second Mortgage Interest Rates Fall Apart
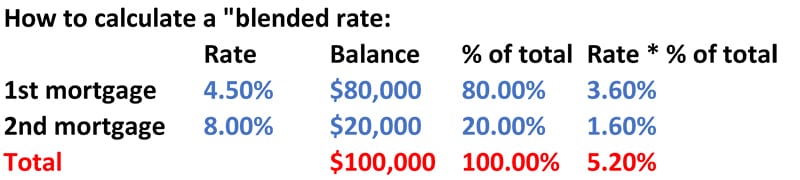
There are scenarios where a second mortgage simply doesn't make sense, and lenders will sometimes push it anyway. If your first mortgage is in negative amortization, adding a second mortgage on top of it can create a payment shock that catches most borrowers off guard. The total monthly payment becomes the first mortgage minimum plus the second mortgage P&I or minimum draw payment. On a $200,000 first at 7% and a $50,000 second at 9%, that's roughly $1,330 plus $450 a month before you even draw a dollar from the HELOC. People forget the HELOC monthly obligation exists even when they're not using it. Cash-out refinancing your first mortgage to consolidate both loans into one is often cheaper than taking a second mortgage. I ran the numbers for a client recently. First mortgage balance was $280,000 at 5.75%. She needed $60,000 in equity for a kitchen renovation. The second mortgage quote came in at 9.25% with $4,200 in closing costs. Refinancing the first mortgage to $340,000 at 7% cost $5,800 in closing costs but combined everything into a single payment at a blended rate closer to 7.1%. The monthly payment was $320 lower, and she eliminated the separate second mortgage obligation entirely. The break-even was fourteen months. After that, she was ahead every month. The biggest limitation with second mortgages is prepayment penalty stacking. Some first mortgages carry a five-year prepayment penalty. Adding a second mortgage during that window means you're locked into both. If you sell or refinance within that period, you could trigger penalties on both loans. Always check the prepayment terms on your first mortgage before layering a second on top.
A Quick Reference for Current Rate Expectations
As of mid-2026, here's what the market actually looks like for qualified borrowers with good credit and reasonable LTVs: HELOCs range from 8.5% to 10.5% variable, tied to the prime rate. A prime move of 0.25% translates directly to your rate. Fixed-rate second mortgages run 8.75% to 11%, depending on credit and LTV. Cash-out refis on the first mortgage position, when you refinance both balances together, typically sit 0.5 to 1.5 points below a standalone second mortgage rate because the first-lien pricing is more favorable. Those numbers shift monthly with the bond market. The 10-year Treasury yield is the benchmark most secondary market lenders watch. When that yield moves up a quarter point, second mortgage rates usually follow within a week. Keep an eye on that if you're planning to apply and have some flexibility on timing.

The One Thing Nobody Tells You About Rate Locks
Second mortgage rate locks often come with stricter windows than first mortgages. Most lenders lock at 30 or 45 days. Extensions cost 0.125% to 0.250% per extension. If your first mortgage is already in escrow and you're waiting on the payoff to clear before the second can close, you might run out of lock window. I've seen this happen maybe four or five times in my career. The fix is straightforward: ask for a 60-day lock upfront if you suspect the closing timeline might stretch. The extension cost is usually less than the rate increase you'd face if the lock expired. Document everything. Get the rate lock agreement in writing before you sign anything. Verbal commitments from loan officers don't hold up when the lock expires. I learned that one the hard way with a commercial client who was building a second unit on his property. The rate was locked verbally at 8.875%. The lock expired during appraisal because the county was backed up. By the time we reopened, the rate was 10.125%. He ate the difference because there was nothing on paper. Now I require written lock confirmation before any application goes out.