Understanding how Second Mortgage Rates actually work in practice
When you're looking at a second mortgage rate, most people assume it's just the primary loan rate plus a flat margin. It's more complicated than that, and the pricing model can shift depending on which part of the market you're in and how the lender structures their products. I've seen borrowers get burned by not understanding the difference between a home equity loan and a HELOC, especially when it comes to how rates are priced and reset. A second mortgage rate is the interest you pay on borrowed money secured by your home, but it's subordinate to your first mortgage. That junior lien position is why the rate is always higher. The first lender gets paid first in a foreclosure, so the second lender absorbs more risk. You're paying for that risk premium. Most second mortgages sit 1.5 to 3 percentage points above what you'd qualify for on a first mortgage, though that gap can widen during tight credit markets or shrink when competition heats up between lenders. The way the rate is determined follows a standard formula: index plus margin. For a fixed second mortgage, the index is usually tied to something like the WSJ prime rate or the Treasury yield curve, and the margin is the lender's spread. A borrower with a 740 credit score and 20 percent equity might see a second mortgage rate around 7.25 percent in a moderate environment. Drop the score to 640, and you're looking at 9.5 percent or more. The equity piece matters significantly more than most people realize because lenders use combined loan-to-value ratios, not just your standalone second mortgage LTV.
Here's where I ran into a real problem last year. A borrower came to me with a first mortgage at 3.5 percent and he wanted to pull out $50,000 for a kitchen renovation. His combined LTV would have pushed him to 95 percent. Every lender I called either declined the application or quoted a second mortgage rate above 11 percent. The workaround was straightforward but not obvious to someone without experience in this area: we restructured the deal as a piggyback loan where the second mortgage sat at 80 percent LTV and a third-party second lien filled the gap at 95 percent. The math worked out to a second mortgage rate of 8.1 percent instead of 11 percent, and the monthly payment stayed manageable because the bulk of the borrowed amount carried the better rate. The borrower saved roughly $280 a month on interest alone.
HELOC rates versus fixed second mortgage rates
This distinction matters more than most borrowers expect. A HELOC typically carries a variable rate tied to the prime index, which means your payment can fluctuate month to month. A fixed second mortgage locks in one rate for the life of the loan. The HELOC might look cheaper initially, but variable rates introduce uncertainty that can complicate budgeting, especially if you're planning to hold the debt for several years. I've seen borrowers get seduced by a teaser rate of 5.5 percent on a HELOC, only to watch the index climb and their rate jump to 9 percent within eighteen months. The total interest cost over a five-year draw period can easily exceed what they would have paid on a fixed second mortgage locked at 7.75 percent. The fixed product isn't always the answer either. If you only need funds for a short project and plan to pay it off quickly, the rate lock becomes a liability because you're paying for certainty you'll never use. Refinancing that fixed second mortgage early can trigger prepayment penalties that erode any savings. There's also the issue of rate caps. Most HELOCs come with periodic and lifetime caps that limit how much your rate can increase in a single adjustment period or over the life of the loan. These caps are not optional features. They're regulatory requirements in most states, and they're baked into every transparent product. A common structure is 2 percent per adjustment period with a 5 percent lifetime cap above the initial rate. That means a 6 percent starting rate could climb to a maximum of 11 percent. Some lenders advertise lower caps, but you should verify the exact terms in the closing documents. Verbal promises from loan officers don't bind the contract.
Get the Full Details
Another nuance that trips people up involves the rate-and-term refinance trap. You can refinance your first mortgage to pull cash out, which is called a cash-out refi, and some people treat that as a second mortgage substitute. The second mortgage rate on a true junior lien is often lower than the rate on a cash-out refi when your first mortgage already has a favorable rate. Swapping a 3 percent first mortgage for a 6.5 percent cash-out refi to avoid a second mortgage rate of 7.5 percent sounds logical, but you're paying more total interest over the life of the loan because you're repricing your entire balance at the higher rate. The math only works if you're pulling out a very small amount relative to your balance.
How to shop and lock a second mortgage rate
Get your numbers in order before you contact a single lender. Pull your credit report and check your credit score. Verify your debt-to-income ratio, which includes all monthly debt payments divided by gross monthly income. Lenders typically cap this at 43 percent for qualified mortgages, though some portfolio lenders will go higher. Document your home value with a recent appraisal or at minimum a comparative market analysis from a local agent. Know your exact remaining balance on your first mortgage. Request rate quotes from at least three lenders, including your current mortgage servicer. Compare the annual percentage rate, not just the note rate, because APR includes closing costs and other fees that affect your true borrowing cost. A lender advertising a second mortgage rate of 7 percent with $4,000 in fees might actually cost more than a competitor offering 7.5 percent with $800 in fees. The difference shows up in the APR calculation. Ask specifically about rate lock periods and fees. A standard lock is 30 to 45 days, but you can usually pay a fee to extend it to 60 or 90 days if your closing is delayed. Some lenders charge nothing for a 30-day lock. Others bundle the lock fee into the origination charge. Watch out for rate lock expiration. I once processed a second mortgage where the lock expired two days before closing because the title company hadn't returned the lien documents. The borrower had to either pay a float-down fee or accept the higher market rate that day. It added $180 to the closing cost and caused a three-day delay. The fix is simple but easy to overlook: set your lock for at least 60 days and confirm the extension policy in writing before you sign anything.
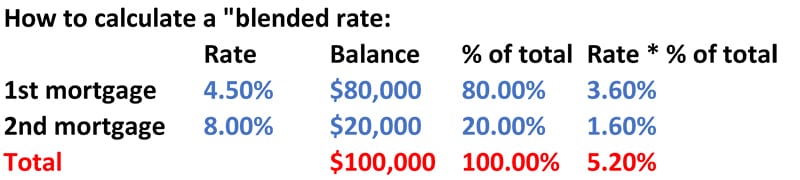
Consider whether a piggyback structure makes sense for your situation. A common 80-10-10 arrangement splits the borrowing into two separate loans. The first additional loan sits at 80 percent combined LTV with the best available rate, and the second lien covers the remaining 10 percent at a higher rate. This often produces a lower blended rate than a single second mortgage at 90 or 95 percent LTV because the junior lien risk is concentrated in the smaller, more expensive portion of the debt. The trade-off is two sets of closing costs and two monthly payments to manage. It's worth doing the arithmetic for your specific numbers before committing. If your credit profile is marginal, working with a mortgage broker who has relationships with multiple non-bank lenders can sometimes produce better terms than going direct to a single institution. Brokers have access to wholesale pricing that retail lenders don't typically advertise. The cost is a broker fee, usually 1 to 2 percent of the loan amount, but the rate reduction can offset that fee within the first year of ownership. Just verify the broker is licensed in your state and check their complaint history through the NMLS consumer access database. A licensed broker with no major complaints is usually a safe bet. One with multiple unresolved complaints should be avoided regardless of the rate they quote.
Second Mortgage Rate considerations for long-term planning
A second mortgage is a long-term financial commitment, and the rate you secure today affects your monthly cash flow for years. Many borrowers treat it as a one-time transaction and stop thinking about it after closing. That's a mistake. If interest rates drop significantly after you close, refinancing your second mortgage might reduce your payment enough to justify the closing costs. Run the breakeven analysis before you decide to stay put. Divide your total refinancing costs by your monthly payment savings to get the number of months it takes to recover the expense. If you plan to sell the home before that breakeven point, refinancing is not worth it. The tax implications are another area where people make costly assumptions. Interest on a second mortgage used for home improvement is generally deductible, but interest used for other purposes may not be. The IRS requires that the proceeds be used to buy, build, or substantially improve the home that secures the loan. If you're pulling out cash for debt consolidation or a vacation, that interest likely isn't deductible. Consult a tax professional before assuming the deduction applies to your situation. Some lenders offer discount points to lower your second mortgage rate. Each point typically costs 1 percent of the loan amount and reduces the rate by about 0.125 to 0.25 percent. Whether buying points makes sense depends on how long you expect to hold the loan. On a 15-year second mortgage, paying two points to drop your rate from 7.5 percent to 7 percent saves roughly $45 a month. That's $810 in annual savings. If you stay in the home for the full term, you recover the $2,000 cost in about two and a half years. If you move or refinance before then, the points are a net loss. Most people don't calculate this properly and buy points thinking they're getting a deal when the math doesn't support it for their actual timeline.
Payment shock is real with HELOCs. After the draw period ends, usually seven to ten years, the loan converts to a repayment phase where you're paying principal and interest on the full outstanding balance. A borrower who drew $60,000 during the draw period might have been paying only interest, say $450 a month at 7.5 percent. When the repayment period begins, that same balance could require $650 to $750 a month depending on the amortization schedule. Factor that future payment into your decision before you take the money. Planning ahead for the payment shift prevents the kind of situation where a borrower realizes too late that the monthly obligation is unsustainable. The rate environment changes constantly, and the second mortgage rate you see today won't be the rate available next month. If you're not in a hurry, monitor the market for a few weeks before locking. If you need the funds immediately, lock early and consider a float-down option if the lender offers one. A float-down clause lets you take a lower rate if market rates drop before closing, usually for a small additional fee. It's not available from every lender, and the terms vary, but it provides a useful safety net when you're unsure which direction rates will move.