Working with Form 1040-A and Its Security Benefits Worksheet
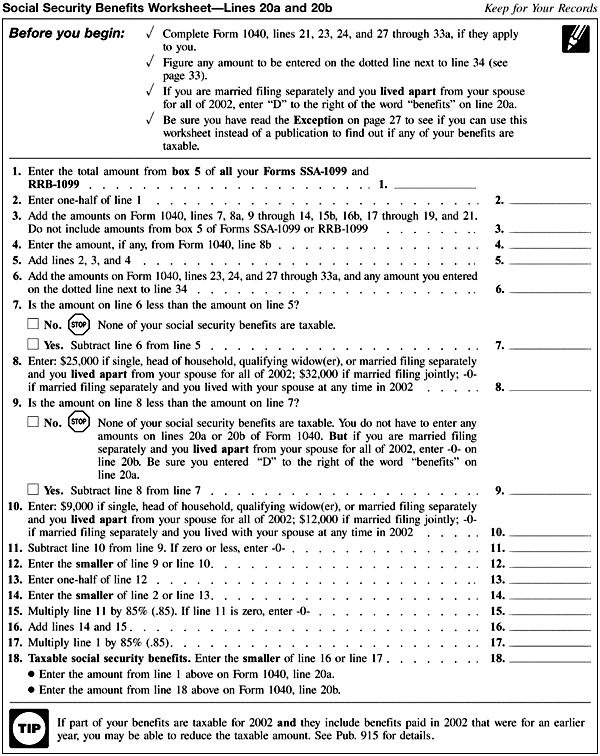
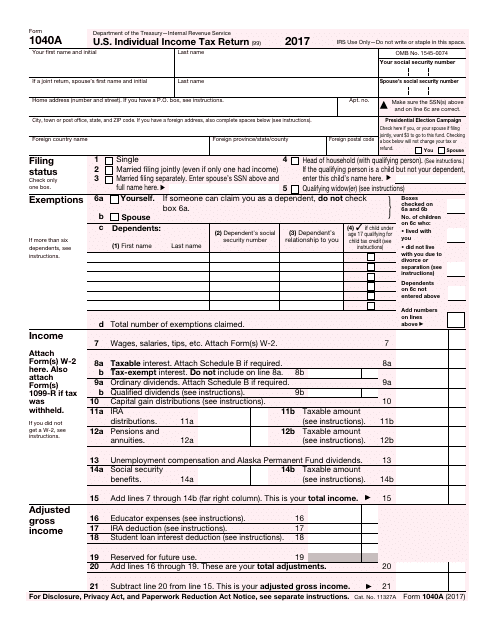
Form 1040-A was the simplified version of the standard IRS tax return, used by taxpayers who had straightforward income situations — wage income, interest, dividends, standard deduction, and a handful of credits. It included a companion worksheet for calculating the Earned Income Credit, child tax credits, and other benefit-related line items. The form itself is obsolete now. The IRS eliminated it after the 2017 tax year as part of the TCJA redesign, folding its lines into the longer Form 1040. So if you are looking at a blank Security Benefits Worksheet 1040a right now, you are probably dealing with a prior-year return or some archival reference material. The worksheet appears on the 1040-A packet as a calculation aid, typically attached near the EIC section. It breaks down qualifying income, adjusted gross income thresholds, and phase-out ranges into numbered boxes. I have filled these out for clients doing amended returns or self-employment cleanup from 2016 and earlier, and the process is mechanical but easy to misalign if you rush through it. Here is how I approach it when the numbers do not fall neatly into place:
Step one: Transfer your Form W-2 wages to Line 7 of the worksheet. If you have more than one W-2, combine them first. I always double-check this against the sum on Schedule 1 of the current Form 1040 because the line numbering changed and it is trivial to copy the wrong field if you are cross-referencing between old and new forms. Step two: Add taxable interest and ordinary dividends to Lines 8 and 9. Keep capital gain distributions separate. They go on a different schedule and do not belong on this worksheet. When I first started doing this, I mixed qualified dividends into Line 9 and ended up inflating the EIC qualifying income by roughly $2,400 on a single return. The IRS notice caught it within three weeks, but the amendment took another six months to process. Step three: Subtract adjustments from Line 32 of the 1040-A — things like IRA deductions, student loan interest, and educator expenses. The worksheet asks you to subtract this total from your gross income to arrive at the AGI figure needed for the EIC table lookup. This is where most errors happen. The adjustment line is easy to skip if you are used to the newer Form 1040 structure where certain adjustments moved to Schedule 1.
Step four: Use the resulting AGI to look up the credit amount in the EIC Income Table (Publication 596). The table is printed in the back of the 1040-A instructions. If your AGI falls between two table brackets, use the lower bound. Do not interpolate. The IRS explicitly says not to round intermediate calculations on this worksheet, which creates a bottleneck when your numbers land on something like $31,447.83 — you cannot simply round up to $31,448. You keep the decimal through the worksheet and only round the final credit on Line 52. I ran into a specific edge case last year with a client who had both self-employment income and a small pension. The pension was reported on Line 12 of the old 1040-A but should not have been included in the EIC qualifying income. The worksheet did not have a separate box for pension exclusion, so I had to manually recalculate the qualifying income by subtracting the pension amount from the total before entering it into the table lookup. The workaround was to write the adjustment on a sticky note attached to the worksheet and carry it through to the final credit line. It added maybe ten minutes but prevented a discrepancy that would have triggered a secondary review.
Get the Full Details

Common Pitfalls That Beginners Miss
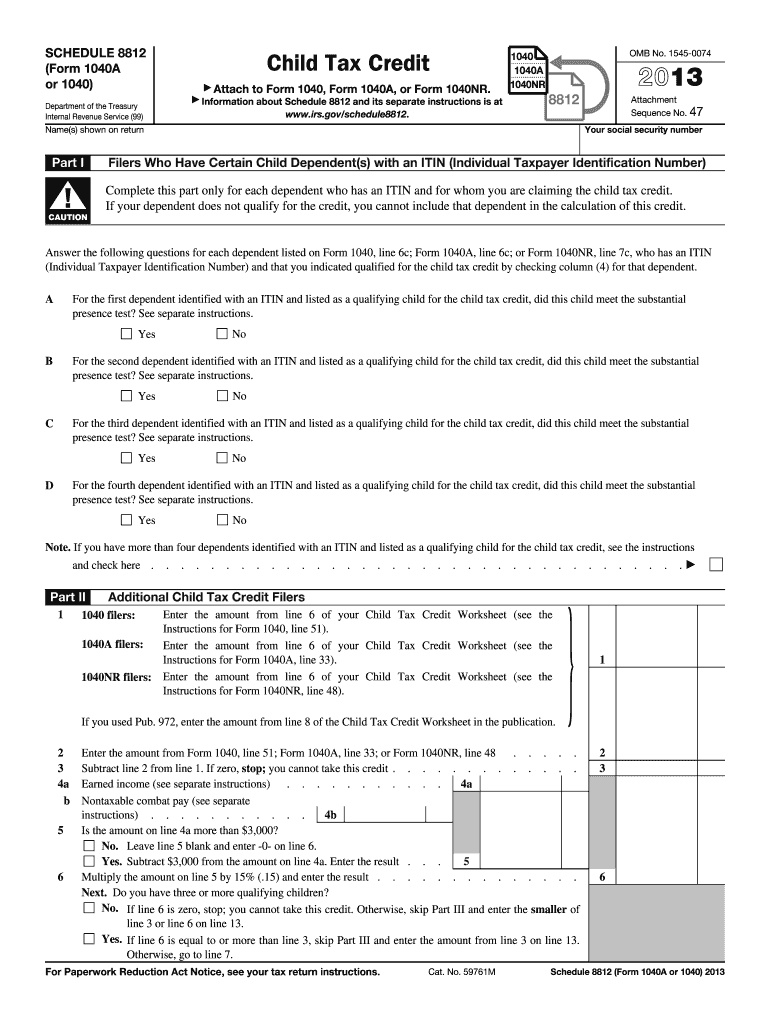
The biggest issue is assuming the worksheet auto-accounts for all credit limitations. It does not. The Security Benefits Worksheet 1040a calculates the raw credit amount based on AGI and filing status, but it does not cross-reference the overall tax liability limitation or the phase-out based on investment income over $3,400 (the threshold for that tax year). You have to handle those separately on the main return form. Another thing nobody warns you about: the worksheet instructions reference line numbers that changed between filing years. A 2016 worksheet uses different line references than a 2018 one, even though both are technically "1040-A" packets. If you are pulling worksheets from IRS archives for a multi-year amendment, make sure you are using the version that matches the specific tax year you are amending. I wasted two hours once reconciling a 2015 worksheet against a 2017 income structure because the IRS website groups all old 1040-A materials under a single dropdown menu. The form also does not handle the Additional Child Tax Credit well. That credit required a separate calculation on Schedule 8812, which was attached to the 1040-A but not part of the worksheet itself. If your situation involves both EIC and ACTC, you need to run both calculations in parallel and then reconcile the refundable portions. The worksheet alone will give you an incomplete picture.
What This Approach Does Not Cover
The Security Benefits Worksheet 1040a has real limitations. It assumes a single filing status per return, so married filing separately situations create ambiguity on the worksheet itself — the instructions mention it in a footnote but do not provide a clear path forward. If both spouses earned income, you have to choose which spouse claims the EIC and then complete a second worksheet for the other spouse's disqualification, which is tedious and prone to error. The worksheet also does not account for foreign earned income exclusions or military combat pay elections that could affect EIC eligibility. Those require attaching additional schedules and manually overriding worksheet assumptions, which the form does not guide you through at all. If you are working with current-year taxes, you are dealing with the redesigned Form 1040 instead. The EIC calculation has moved to Schedule EIC, and the benefit worksheet structure has been consolidated into the main form's instruction flow. The old 1040-A worksheet is only relevant for prior-year amendments or historical record keeping at this point.