How Texas Seller Closing Costs Actually Break Down
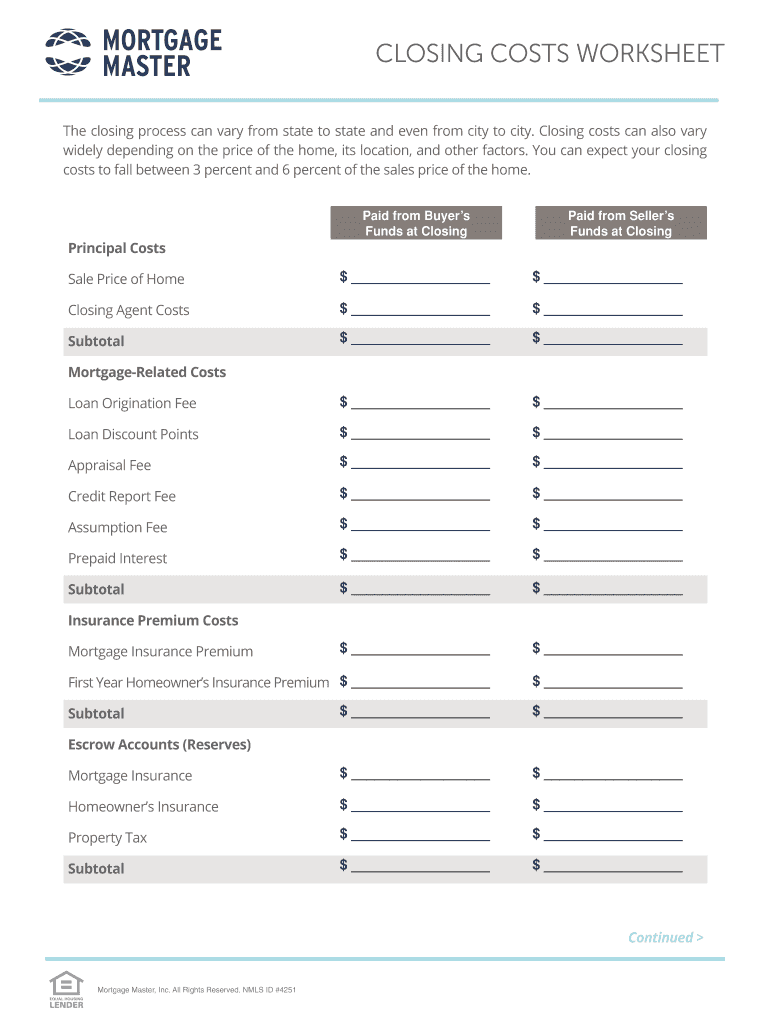
When you sell a house in Texas, you are looking at roughly 1% to 3% of the sale price going out the door in seller-paid closing costs. That number sounds small until you are sitting at a $400,000 property and realize you are handing over anywhere from $4,000 to $12,000 before the check clears. The bulk of that comes from three buckets: the prorated property taxes, the title insurance policy you are required to pay for in most transactions, and the agent commissions if you have one involved. Everything else is line-item noise on the HUD-1 or Closing Disclosure. Property taxes in Texas are brutal compared to most states. The average effective rate sits around 1.8%, and your closing statement will prorate what you owe from January first through the closing date. If you close on June 15th and your annual tax bill is $8,000, you owe roughly half that amount right then. Some counties charge higher rates. Houston area properties with the hospital district surcharge can push the effective rate past 2.3%, and that gap absolutely matters when you are running numbers.
Using a Seller Closing Cost Calculator Texas
A Seller Closing Cost Calculator Texas takes the raw sale price and runs it through the standard fee schedule so you do not have to chase down each line item yourself. You enter the purchase price, the county, the estimated closing date, and any negotiated credits. The calculator spits back an estimated breakdown showing transfer fees, title charges, agent commission if applicable, prorated taxes, and whatever local municipality fees your county adds on. It is fast. Most people get a rough picture in under three minutes. The problem is that calculators are only as good as the data you feed them and the assumptions baked into their programming. A lot of free online tools assume standard transactions. They do not account for special assessments, school district bond fees, or the occasional county-specific surcharge that shows up without warning. You will need to verify the output against an actual title company quote before you put a listing price on the market. Treat the calculator as a starting point, not the final word. I ran into this exact issue last year working with a seller in Fort Bend County. The online calculator I use routinely showed estimated closing costs at about 2.1% of the sale price. When the title company sent over the actual preliminary closing disclosure, the real number came in closer to 3.4%. The gap was almost entirely due to a drainage district special assessment that the calculator did not know about because it is local to a handful of subdivisions and rarely appears in national databases. The workaround was straightforward. I pulled the appraisal district records for the specific parcel, found the outstanding assessment balance, and added it as a separate line item. That adjustment alone cost the seller an extra $2,800 at closing. Without catching it early, he would have been short at the table and the deal could have stalled.
Where the Real Costs Live
Title insurance is where most sellers lose sleep. In Texas, the seller typically pays for the owner's title policy. The cost is one-time and depends on the sale price. A $350,000 home runs roughly $1,200 to $1,500 for the policy. It covers the buyer's protection for as long as they own the property, but you are the one writing the check. Some sellers negotiate to have the buyer cover this, and it happens regularly in buyer's markets, but in competitive areas like Austin and Dallas, sellers often absorb it because the deal falls apart otherwise. Transfer taxes in Texas are essentially nonexistent at the state level. That is unusual and many sellers find it confusing. Unlike California or New York, where you pay a meaningful documentary stamp tax, Texas does not levy a state-level transfer tax. You might see a small recording fee charged by the county clerk, usually between $25 and $75, but that is about it. This is one of those things that trips people up when they compare Texas to other states online. Agent commissions remain the biggest single line item if you are using a listing agent. The standard rate in Texas runs 5% to 6% of the sale price, split between the seller's agent and the buyer's agent. On a $300,000 home, that is $15,000 to $18,000 disappearing. Some brokers offer reduced-rate programs now, and flat-fee MLS listings exist, but you need to evaluate whether you are actually saving money or just shifting work onto yourself. Commission negotiations are also heavily influenced by local market conditions. In a hot market where multiple offers are common, sellers rarely budge on this. In a slow market, it is one of the few bargaining chips left.
Get the Full Details
Edge Cases That Break the Calculator
New construction purchases introduce a whole different set of closing costs, and the standard calculator struggles here. Builder incentives, warranty fees, and rate buydowns complicate the seller side of things even when you are the original owner selling the newly built home. The title company may run additional searches for builder liens, and you could see an attorney review fee pop up that does not appear in residential resale transactions. Short sales and foreclosures operate on completely different rules. Most online calculators do not handle those scenarios at all. If you are working with a bank or a lender approval process, the closing cost structure shifts dramatically because the bank imposes its own requirements and fees on top of the standard charges. You need a title company and a real estate attorney familiar with distressed transactions rather than relying on a generic online tool. Landlocked properties or rural sales with septic systems add environmental inspection fees that most calculators ignore. A well and septic inspection in East Texas can cost $600 to $1,200, and if you are the seller, that often comes out of your share at closing. The calculator will not tell you this unless you manually enter it, and most people forget to do that until the inspection report arrives.
What You Can Actually Control
Shop the title company. This is the single highest-impact decision you can make. Title insurance rates are regulated by the Texas Department of Insurance, so the base premium is fixed, but the overhead charges, processing fees, and administrative costs vary significantly between companies. I have seen the same $400,000 transaction differ by over $600 in total title costs between two providers in the same county. Get at least two quotes before you accept the buyer's preferred title company. Time your closing strategically. Property tax proration changes depending on when you close in the fiscal year. If you close in December, you are responsible for nearly a full year of taxes. If you close in January, your proration obligation drops dramatically. This does not matter for small amounts, but on high-tax-county properties it can swing the difference by a thousand dollars or more. It is worth coordinating with your agent and the buyer's side to land on a date that minimizes your proration hit without delaying the deal unnecessarily. Know your homestead exemption status. If your property still has a valid homestead exemption at the time of sale, the buyer may need to reapply, and there can be subtle implications for the proration calculation. Some sellers get caught off guard because they assumed the exemption would transfer automatically. It does not. The buyer files a new one. This does not directly affect your closing costs, but it comes up frequently enough during negotiations that it is worth addressing early.
The bottom line is that a Seller Closing Cost Calculator Texas gives you a reasonable ballpark, but the devil is always in the county-specific details. Special assessments, title company fees, and local municipal charges can push your real costs well above what the calculator shows. Run the numbers through the tool, then call a local title company for a preliminary estimate based on your exact address and closing date. The difference between the two numbers tells you exactly how much extra you need to budget. If you want something more concrete, the Texas Association of Realtors publishes annual closing cost guides that break down typical fees by region. These are free PDFs and they include county-specific notes that most generic calculators skip entirely. Pair that with a title company quote and you have a number you can actually rely on when listing your home.