How to Actually Calculate What You Will Pay at Seller Closing
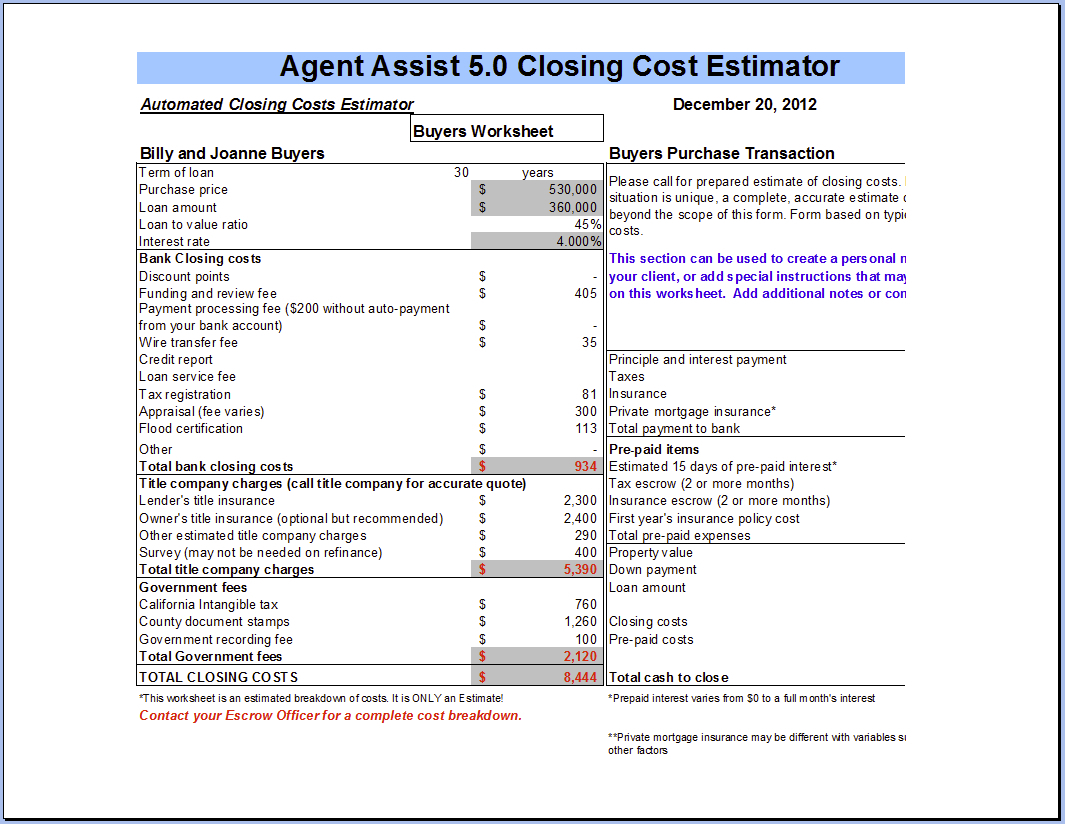
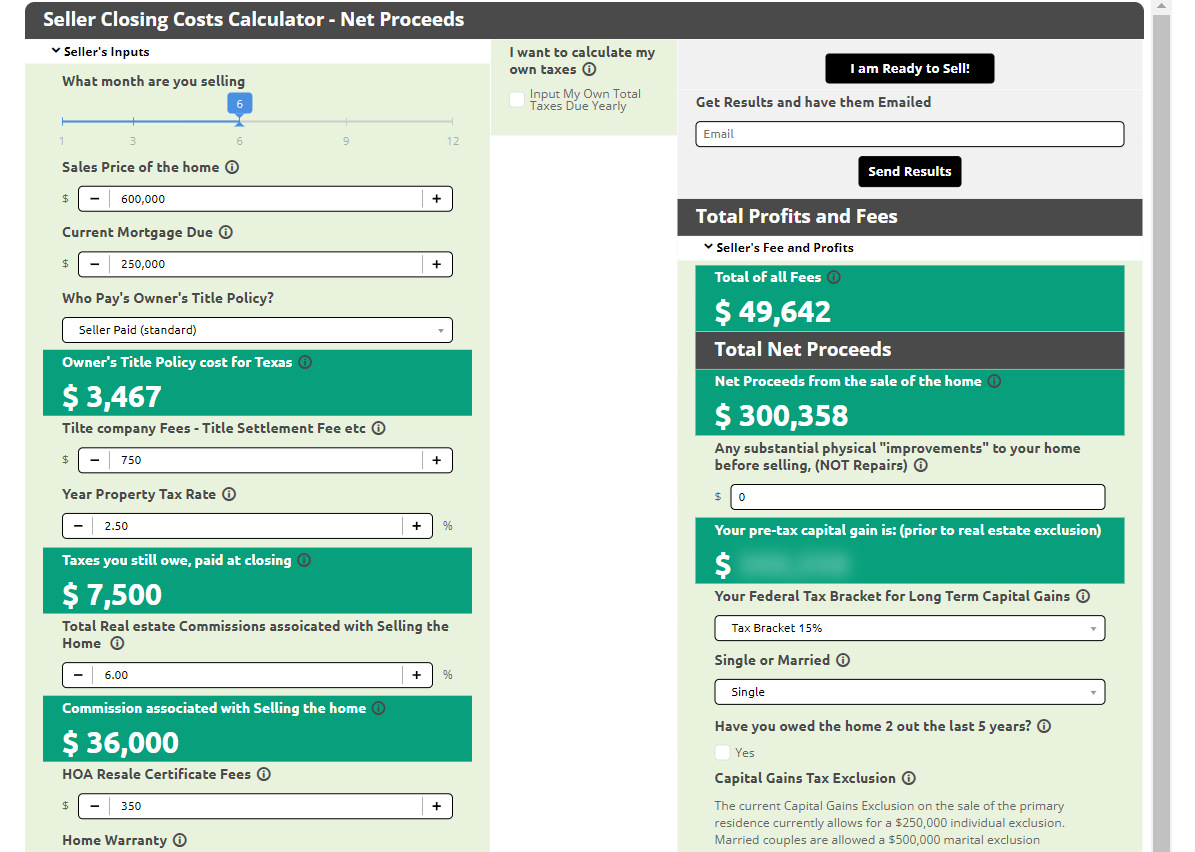
You just listed your home. The buyer signed. Now you are staring at a HUD-1 or Closing Disclosure and most of the line items make no sense. You want to know what number is coming out of your pocket before the actual documents arrive. A Seller Closing Costs Calculator is supposed to help with exactly this, but the ones you find online vary wildly in accuracy. Here is how to use one properly and what to do when it does not cover your situation. I ran into a specific problem last year when a client asked me to review their estimated seller closing costs. The online calculator they used threw together a clean $18,500 figure, but when we opened the actual settlement statement, the number came in at $24,200. The calculator had assumed a standard arm's-length transaction. The house was being sold by an executor. Estate sales trigger additional recording fees, fiduciary affidavits, and in some counties a separate transfer tax band that most generic calculators do not account for. The $5,700 gap came entirely from those estate-specific line items. My workaround was to take the calculator's base output and then manually add the three estate surcharges: the fiduciary declaration fee ($275), the enhanced recording fee for the executor's deed ($140), and the county's supplemental transfer tax at 0.11% of the sale price. Once I layered those on, the estimate landed within 2% of the actual closing figure. Most free calculators follow the same basic math. They take your sale price and apply rough percentage rates to each cost category. It looks something like this.
Using a Seller Closing Costs Calculator Step by Step
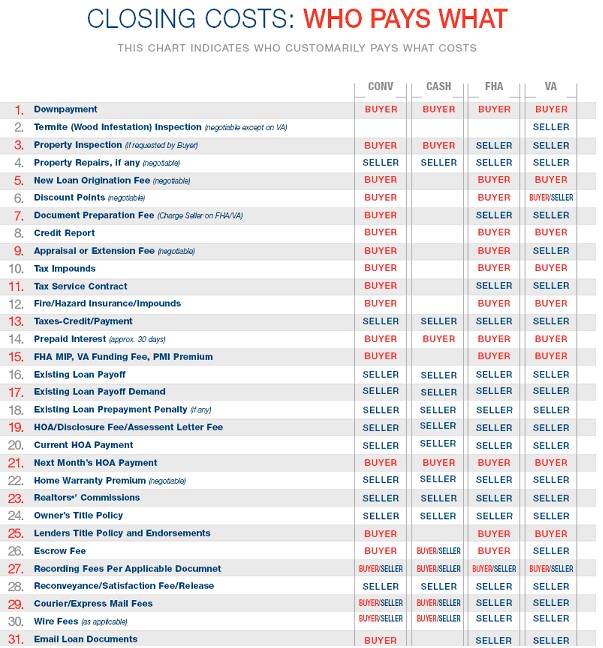
The inputs are straightforward. Sale price, location, and property type. Enter your expected sale price first. That number drives almost every other line item because transfer taxes, agent commissions, and title insurance are all calculated as a percentage or a tiered bracket of the sale price. Select your state and county. Transfer taxes are local. Some states have no documentary stamp tax at all. Others charge per $500 or per $100 of the consideration. The county matters because recording fees and certain municipal transfer taxes vary by jurisdiction, not just by state. The calculator will then estimate agent commissions. This is where most people get tripped up. The default assumption is a 5 to 6 percent total commission split between the listing and buyer's agents. That is a common range but it is not a rule. Commission rates are negotiable. If you have a flat-fee listing arrangement or you negotiated a 4 percent total commission, the calculator will overestimate unless you change that input. I always tell people to enter the actual agreed rate, not the industry average, because the difference on a $400,000 home can be $4,000 or more. Title insurance for the seller is another line that varies by calculator. Some include the owner's title policy. Most do not. In many states the seller pays for the owner's policy as part of the customary closing cost structure. In others the buyer pays for it. The calculator you use should let you toggle this. If it does not, you need to know your local custom and add the cost yourself. Owner's title insurance for a $400,000 property typically runs between $1,000 and $1,800 depending on the state and the insurer.
Transfer taxes are non-negotiable but highly variable. State-level transfer taxes range from zero to roughly 1 percent in a handful of high-tax states. County and municipal transfer taxes sit on top of that and can add another 0.1 to 0.5 percent in some metro areas. The calculator should break these out separately. If it lumps them into one "transfer tax" line with no detail, treat that number as a rough floor, not a precise prediction. Other standard seller costs include HOA transfer fees, which are typically $200 to $500, proration of property taxes if you are closing mid-cycle, and a settlement or administrative fee that most title companies charge between $150 and $350. Some calculators include these. Many do not. When you hit calculate, the output will usually fall in the 1 to 3 percent range of the sale price for a typical residential transaction. On a $350,000 home that means roughly $3,500 to $10,500 in seller closing costs. The wide range exists because location and commission structure dominate the math more than anything else.
Get the Full Details

Here is a practical example. Sale price $425,000. Two-agent commission at 5 percent total. State transfer tax at 0.11 percent. County transfer tax at 0.22 percent. Owner's title policy at $1,450. Settlement fee at $275. HOA transfer at $350. Prorated property taxes due to the seller at $1,800. That totals approximately $8,600. A calculator that skips the HOA fee and underestimates transfer taxes might show $7,400 instead. The discrepancy is small but it changes your net proceeds calculation. The biggest limitation of any online Seller Closing Costs Calculator is that it cannot read your settlement statement. It does not know about your specific contract contingencies, your local escrow company's fee schedule, or whether your county imposes a special assessment overlay. It also cannot account for negotiation outcomes like seller concessions that appear as credits rather than costs. Concessions reduce your net proceeds but they are not always reflected in the calculator's cost output. If the buyer asked for a $5,000 closing cost credit, the calculator will not automatically subtract that from your estimate. Another blind spot is seller-paid mortgage payoff. If you still owe money on the property, the payoff statement from your lender will include prepayment penalties, late fees, or administrative charges that no generic calculator can predict. You have to pull that number directly from your lender. I had a situation where a client's calculator showed a clean payoff at $187,000, but the actual payoff quote came back at $194,300 because of an unsubsidized prepayment penalty and a $450 wire fraud prevention fee the calculator had no way of knowing about. That $7,300 difference came entirely from lender-side costs, not from closing costs in the traditional sense, which is why it is easy to miss when you rely on a tool alone.
If you need higher accuracy than a free calculator provides, the practical approach is to use the calculator for a quick ballpark, then request a binding estimate from the title company or settlement agent handling your transaction. A professional closing estimate will include every local fee, every proration, and every concession line item. It will not be free, but it will be close to final. The time investment is usually 20 to 30 minutes on the phone or a quick email exchange, and it eliminates the guesswork that costs people thousands when they plan their net proceeds around an online tool. For most transactions, a well-configured online calculator gets you within 10 to 15 percent of the actual number. That is enough to know whether you are going to walk away with a reasonable profit or whether you need to adjust your listing strategy. It is not enough to sign anything or to assume the check you write at closing will match the number on the screen. Treat it as a planning tool, not a guarantee.