How Seller Financing Actually Works Under the Hood
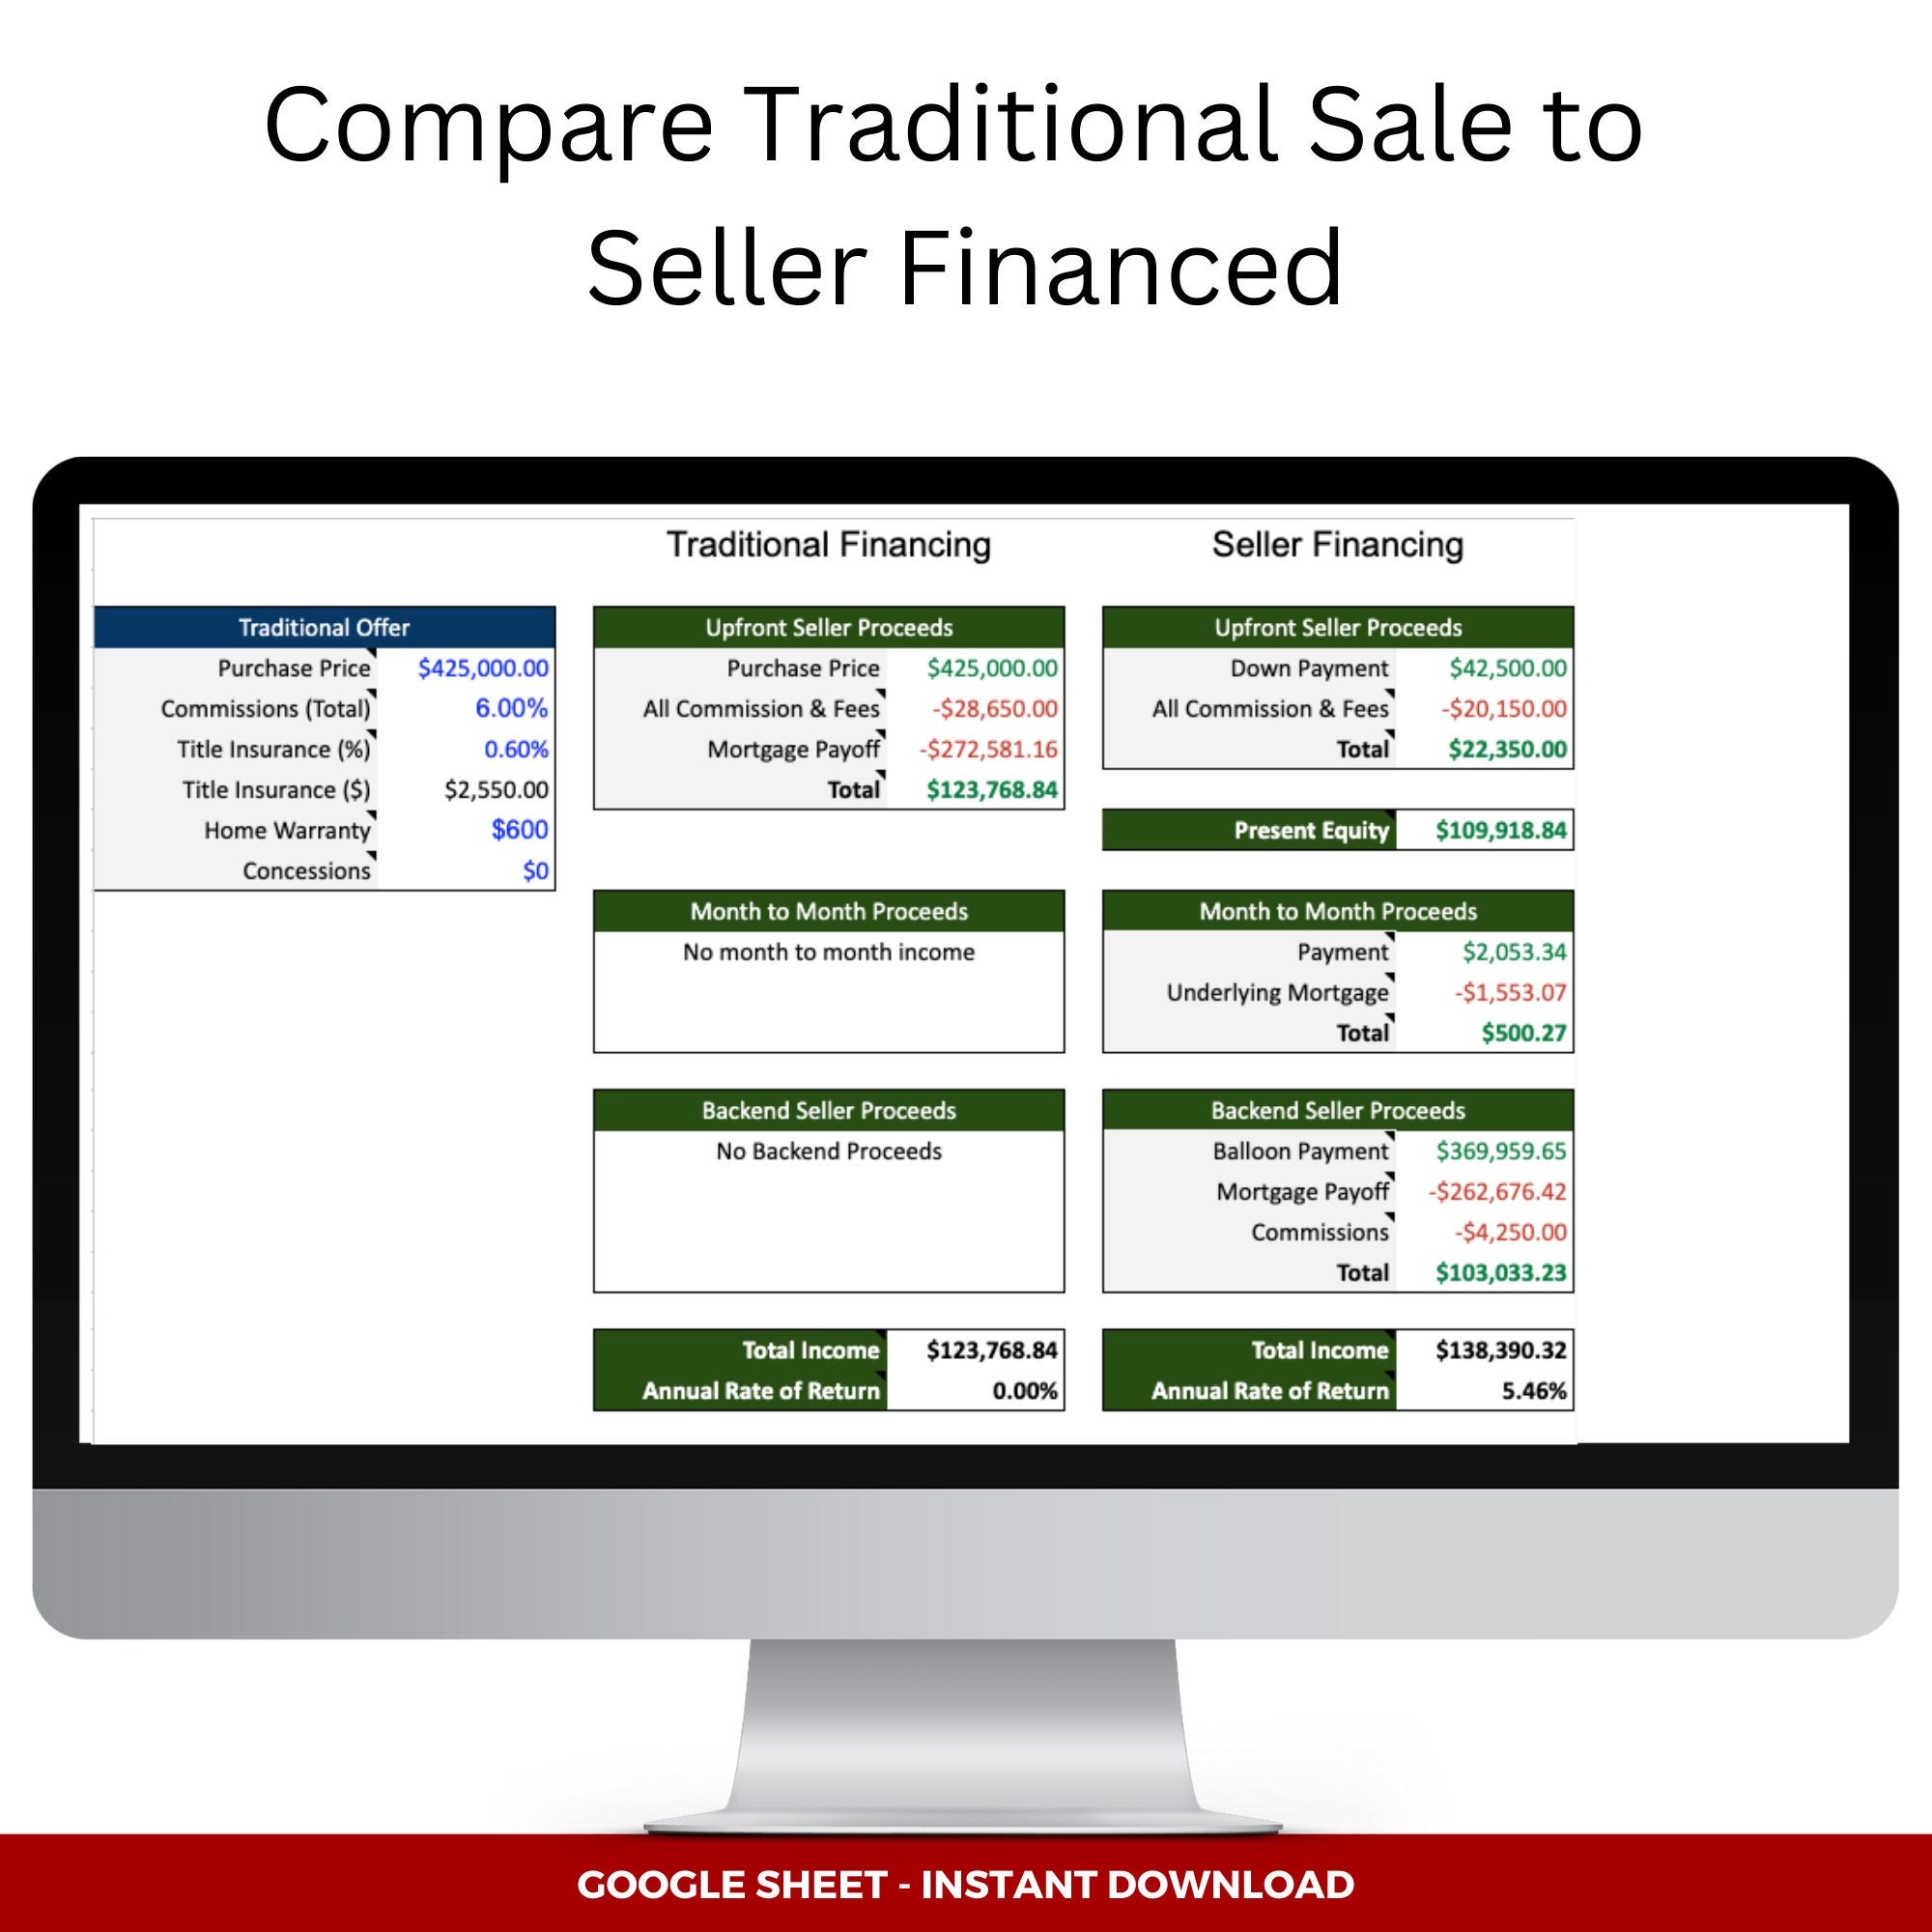
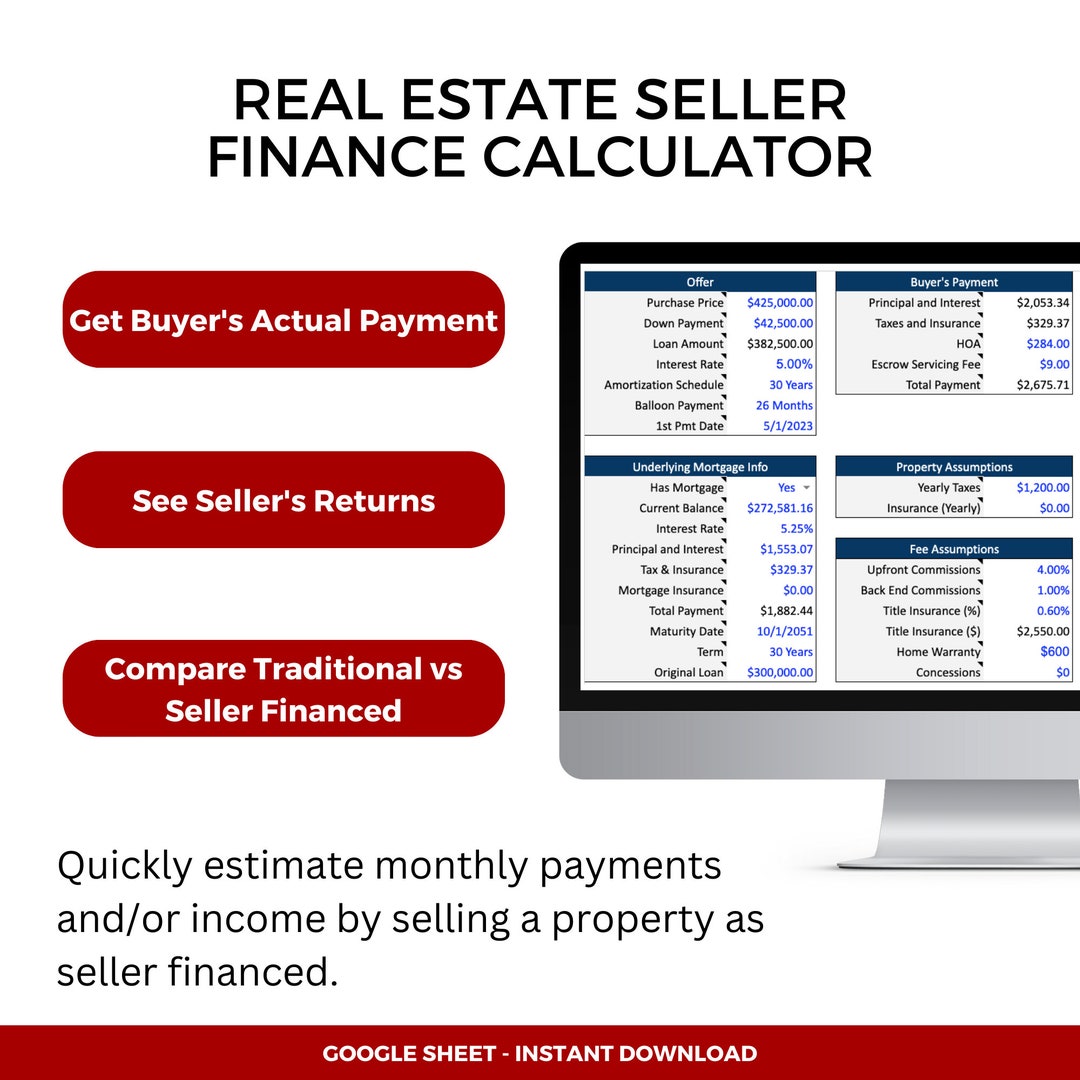
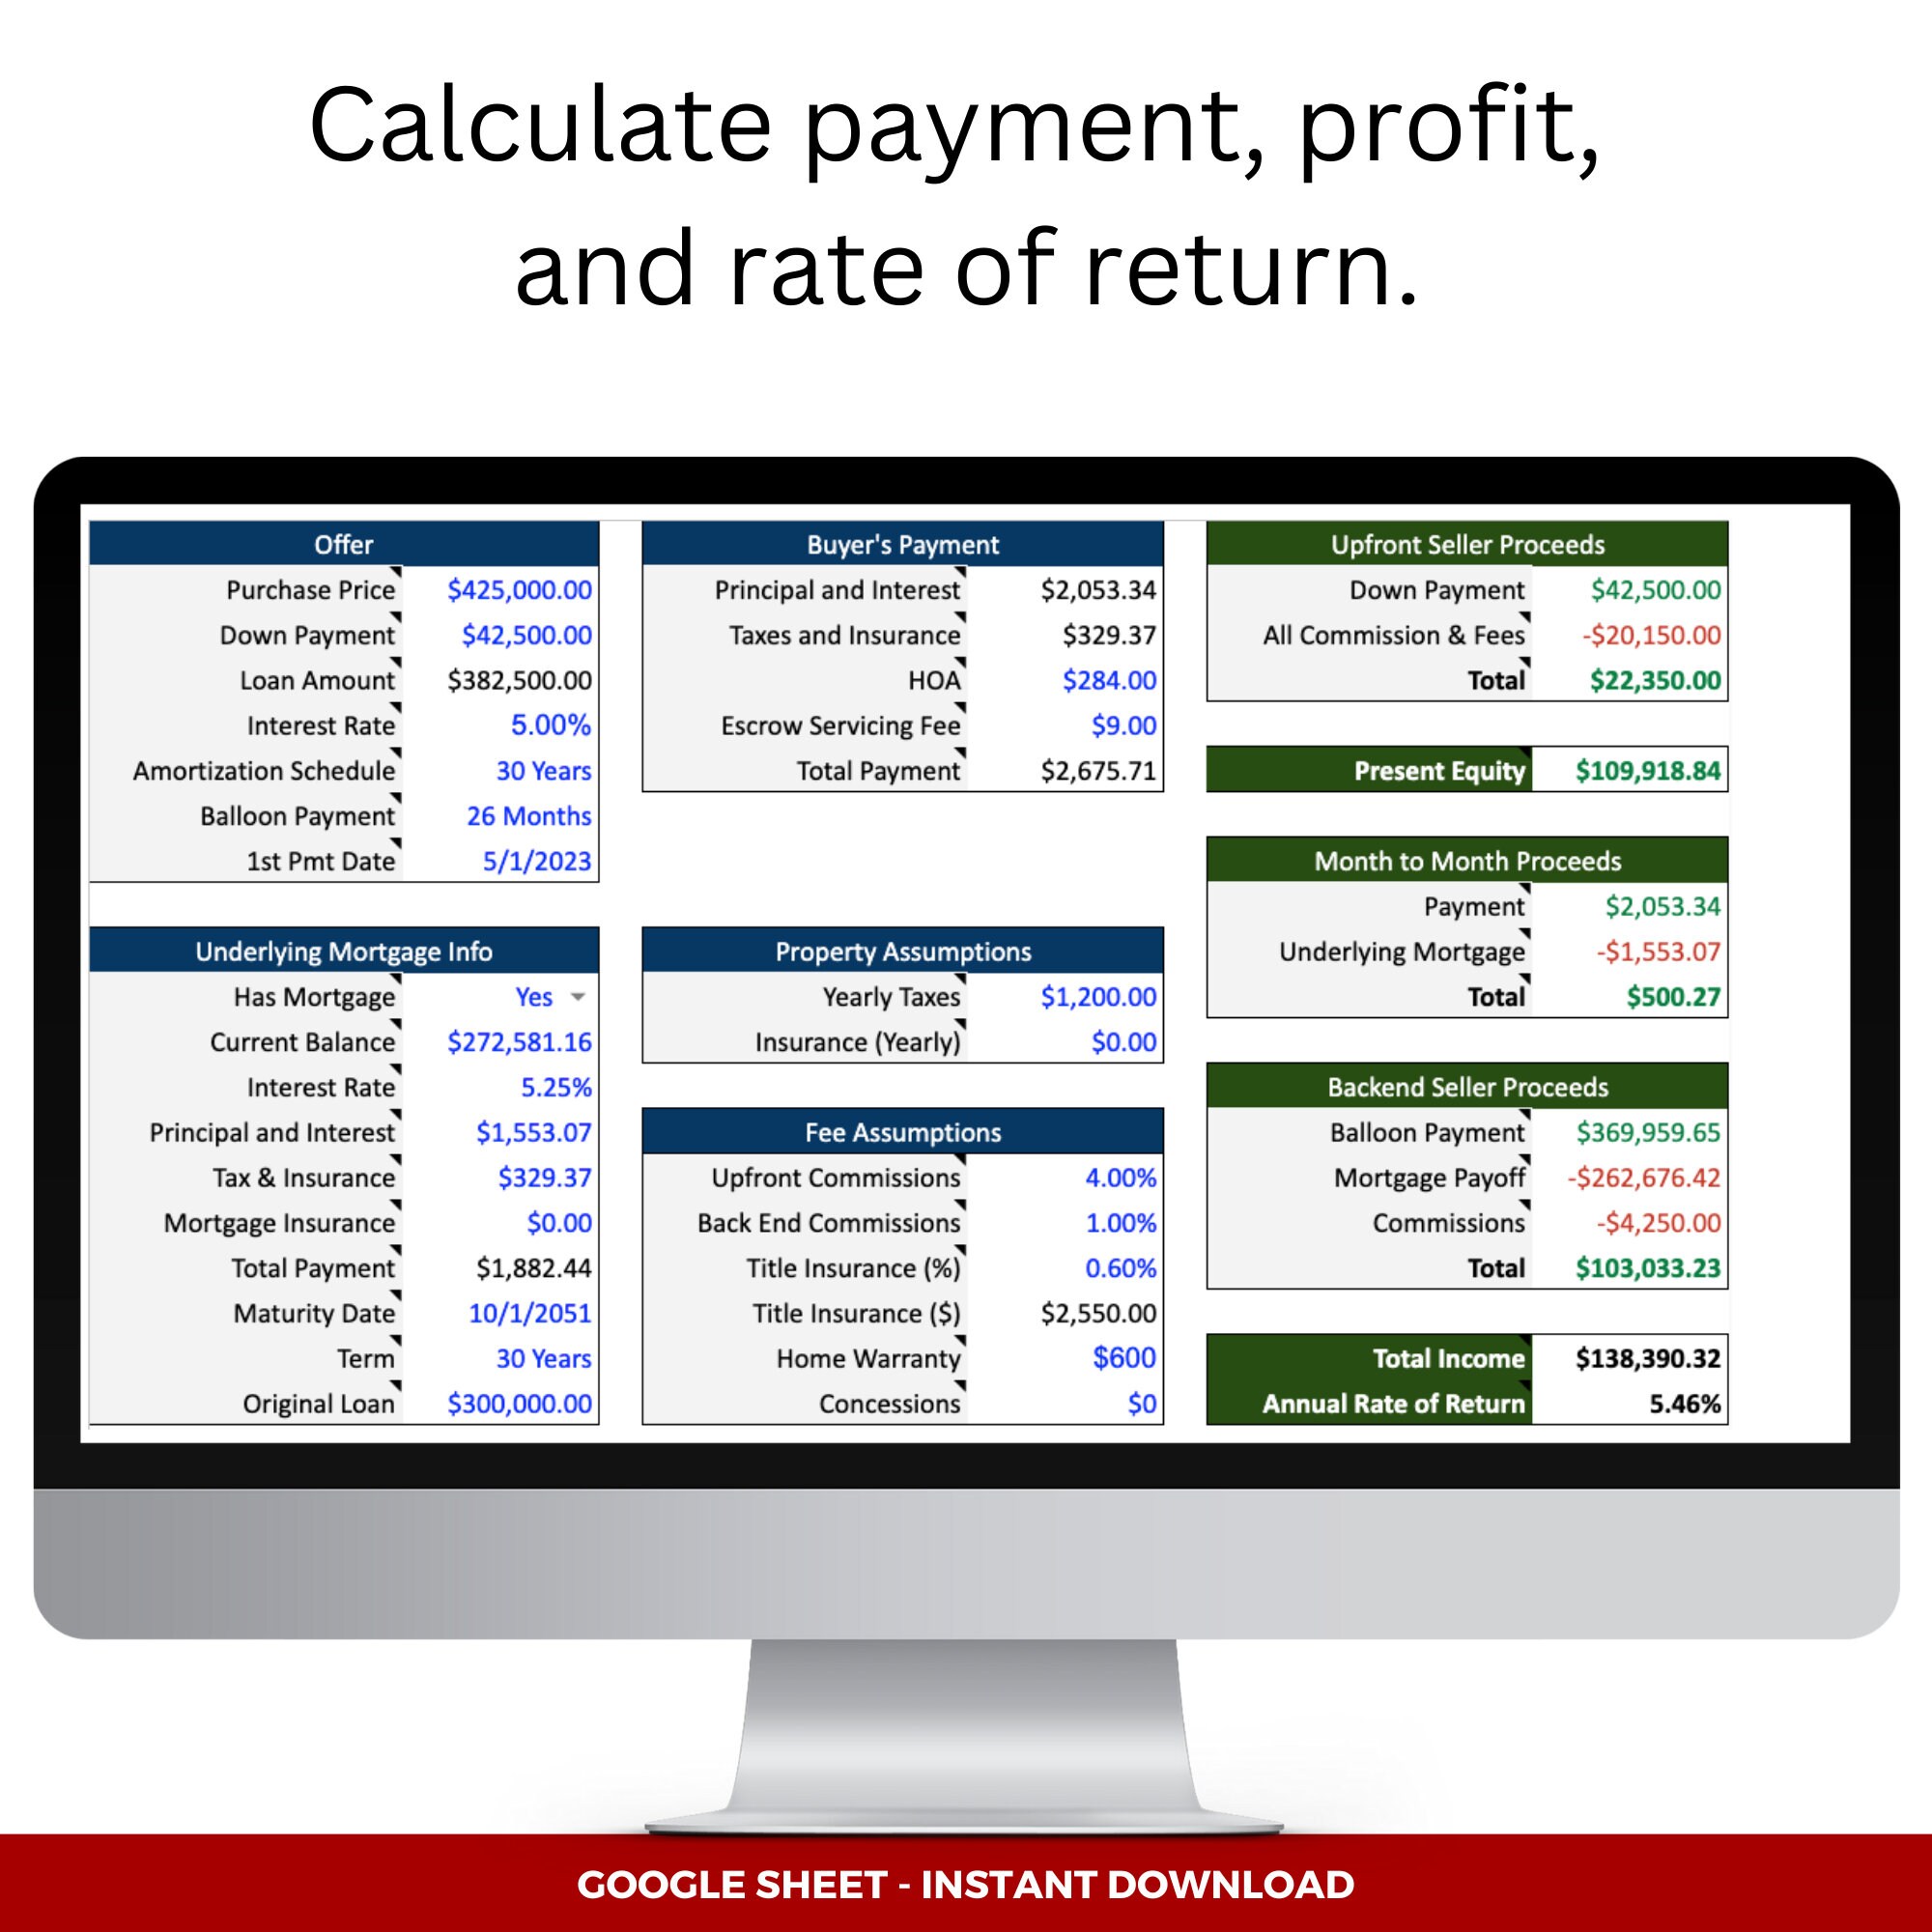
A seller financing calculator is just a tool that takes a few inputs and returns payment schedules, but getting it right requires understanding what each variable actually does to the numbers. Most free calculators online spit out a monthly payment based on a simple amortization formula, which sounds fine until you realize the buyer and seller often need more than just a payment figure. You need to see the full schedule, understand balloon payments, and know where the numbers break. The core inputs are straightforward enough. You put in the purchase price, the down payment amount or percentage, the interest rate, and the loan term. From there the calculator applies the standard amortization formula to derive the periodic payment. But here is where people get tripped up. The formula assumes equal payments at equal intervals with a fixed rate, and seller financing deals frequently deviate from that assumption. That mismatch is the first thing I learned the hard way.
Using a Seller Financing Calculator Properly
When I built my own version for internal use, I started with the standard amortization formula: payment equals the principal times the monthly rate, divided by one minus the monthly rate raised to the negative of the total number of payments. It is the same formula you find in any finance textbook, but applying it correctly means accounting for compounding frequency, payment timing, and what happens when the deal is not a standard fully amortizing loan. Most people skip step two and just run the calculator with default settings. The defaults assume monthly compounding and a conventional amortization schedule. In practice, seller financings often use annual payments, quarterly interest adjustments, or interest-only periods followed by a balloon. If your calculator does not let you adjust those parameters, it is generating garbage results that look clean on the surface. I have seen buyers and sellers sign documents based on payment estimates that were off by hundreds of dollars per month because the tool ignored the actual compounding structure. One specific problem I encountered involved a deal where the seller required a fifteen percent balloon payment at the end of year five, with the remaining balance amortized over a twenty-year schedule. The calculator I was using assumed a fully amortizing loan, so it reported a lower monthly payment than what was actually needed. The buyer signed based on that number, then could not make the balloon payment at year five. I had to rebuild the schedule to account for the balloon. The workaround was to treat the balloon as a separate future value calculation and back into the correct monthly payment by solving for the annuity portion that, when combined with the present value of the balloon payment, equaled the financed amount. This took about ten minutes in Excel using the PMT function adjusted for the residual balance.
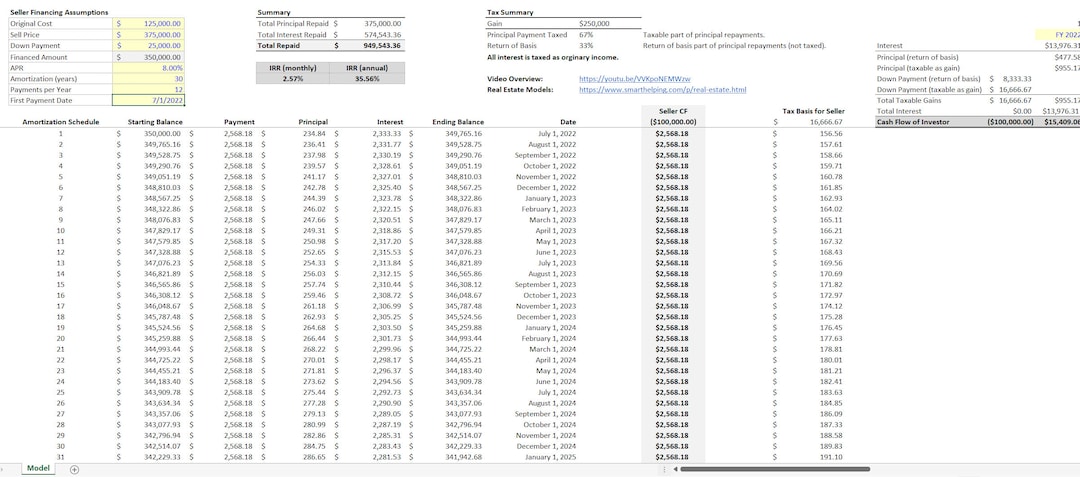
Another nuance people miss involves how the interest is calculated on the declining balance. Some seller financing arrangements use simple interest on the original principal rather than compound amortization. That changes the payment structure entirely and can result in significantly different total interest costs over the life of the loan. A good calculator should let you toggle between amortizing and simple interest modes, but most free versions online do not. I stopped trusting any calculator that did not explicitly state its interest method. When you input the numbers, always verify the output against a manual calculation at least once. Take a test case with round numbers, like a hundred thousand dollar loan at eight percent over ten years, and compute the payment yourself. If the calculator gives you something other than roughly eleven hundred and thirty-seven dollars per month, something is wrong with the math or the assumptions baked into the tool. This check takes thirty seconds and prevents downstream errors that can cost thousands. The schedule output is where most calculators fall short. They show the monthly payment but do not break down principal versus interest for each period, or they show it in a format that is hard to read. You want a full amortization table that shows every payment, the remaining balance after each one, and the cumulative interest paid. This matters because the tax implications for both parties depend on how the interest is structured and reported. Sellers need this for their own records, and buyers need it for depreciation and deduction calculations.
Get the Full Details
Pitfalls and What These Calculators Cannot Do
Seller financing calculators are narrow tools. They handle the math, but they do not address legal compliance, due diligence, or the structural risks inherent in this type of arrangement. I have seen deals where the math was perfect on paper and the transaction still failed because the promissory note did not properly secure the lien, or because the interest rate violated usury laws in the applicable state. No calculator can tell you whether your terms are enforceable. There is also the problem of variable rates masquerading as fixed rates. Some seller financing arrangements include an adjustable rate clause tied to an index. Basic calculators cannot model this. You would need a more sophisticated tool that allows rate adjustments at specified intervals and recalculates the payment schedule accordingly. If your deal has any rate variability, a standard amortization calculator is insufficient. Another limitation is prepayment modeling. Buyers often want to know how much they save if they pay extra or pay off the loan early. Most calculators do not include a prepayment scenario builder. When I need this, I use a spreadsheet with conditional logic that adjusts the payment schedule based on additional principal contributions at any given period. It is more work upfront, but it prevents awkward conversations later when the buyer realizes the calculator lied about their savings potential.
The biggest blind spot in most calculators is the treatment of closing costs and fees. Seller financing often includes points, origination fees, or administrative charges that are rolled into the loan amount or paid separately. If the calculator does not let you incorporate these into the financed principal, the effective interest rate is understated and the payment estimate is misleading. Always confirm whether the calculator accounts for fees or if you need to adjust the input manually.
What to Look for in a Reliable Tool
A usable Seller Financing Calculator should let you adjust compounding frequency, specify balloon payments, handle interest-only periods, generate a full amortization schedule, and model prepayment scenarios. It should also clearly state its assumptions so you can verify the math yourself. The best tools I have used allow custom payment dates, multiple rate periods, and fee adjustments. They are not always free, and they are not always easy to find, but the cost of a bad estimate far exceeds the cost of a decent tool. If you are evaluating a deal, do not rely on a single calculator output. Run the numbers through two different tools or a manual spreadsheet, compare the results, and investigate any discrepancies. Differences of a few dollars are normal due to rounding conventions. Differences of more than a percent suggest one of the tools is using incorrect assumptions. I treat any calculator that does not let me see and modify its underlying formula with suspicion. If the math is opaque, the results are not trustworthy. Seller financing is a legitimate and sometimes advantageous way to structure a real estate transaction, but it requires precision. The calculator is only as good as its inputs and its assumptions. Verify everything, understand the limitations, and never let a tool replace a careful review of the actual contract terms. The numbers on a screen are useful, but they do not replace the need to read the fine print and understand the legal and tax consequences of the arrangement.