How Semi-Annual Payments Actually Work
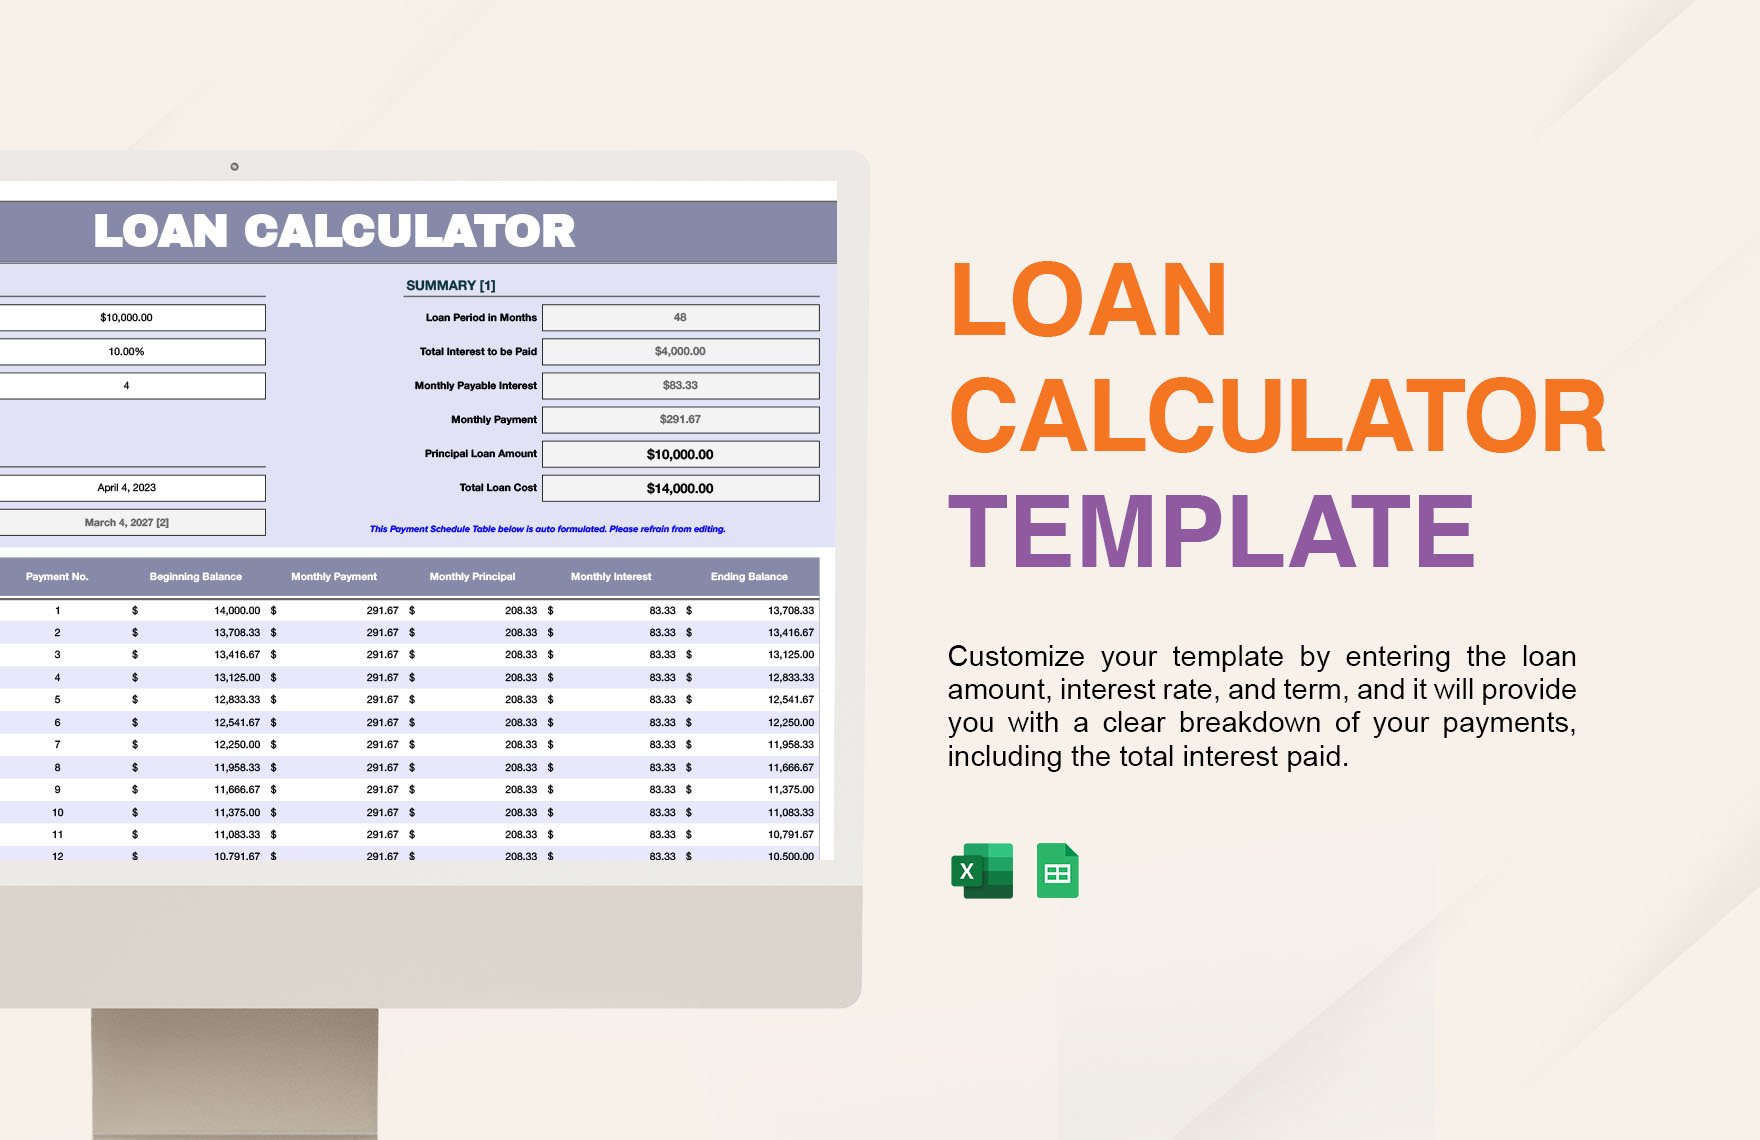
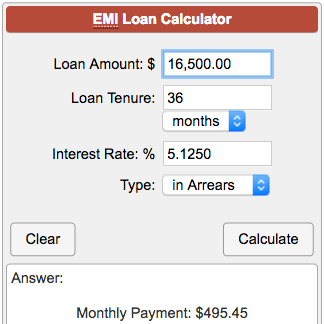
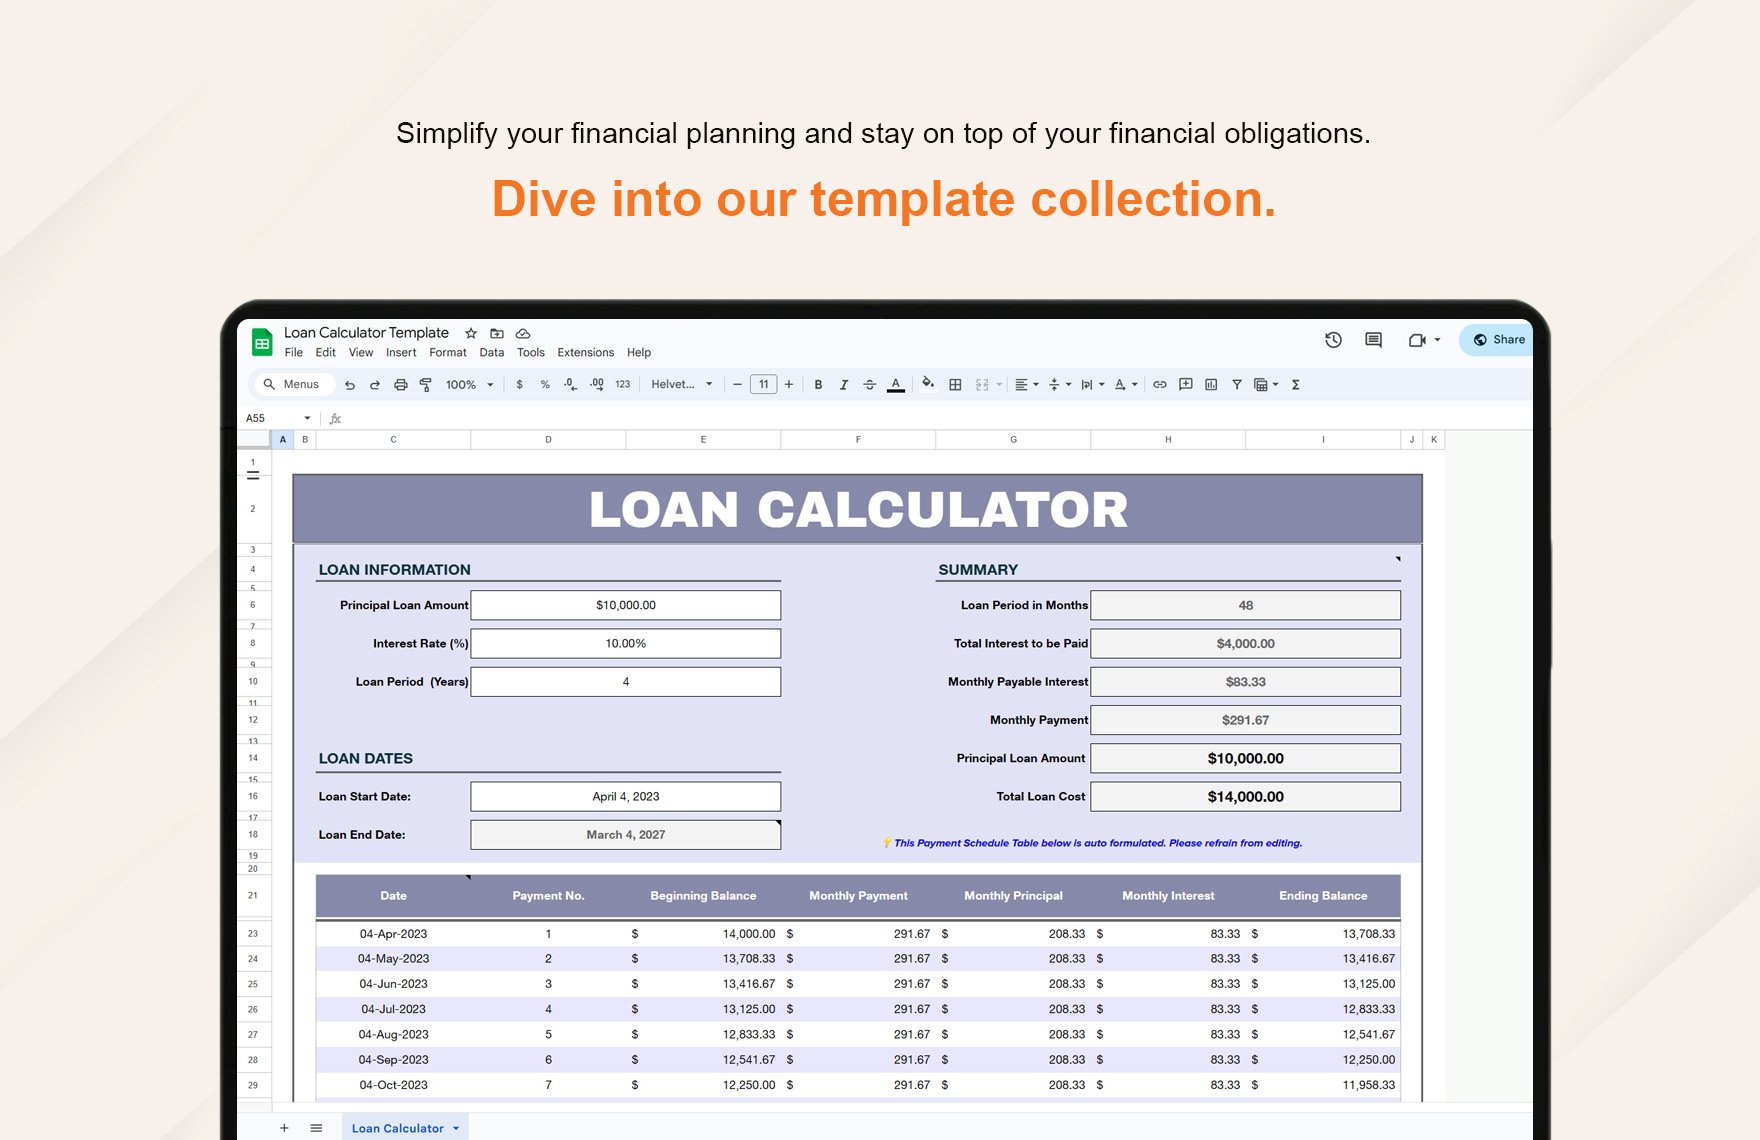
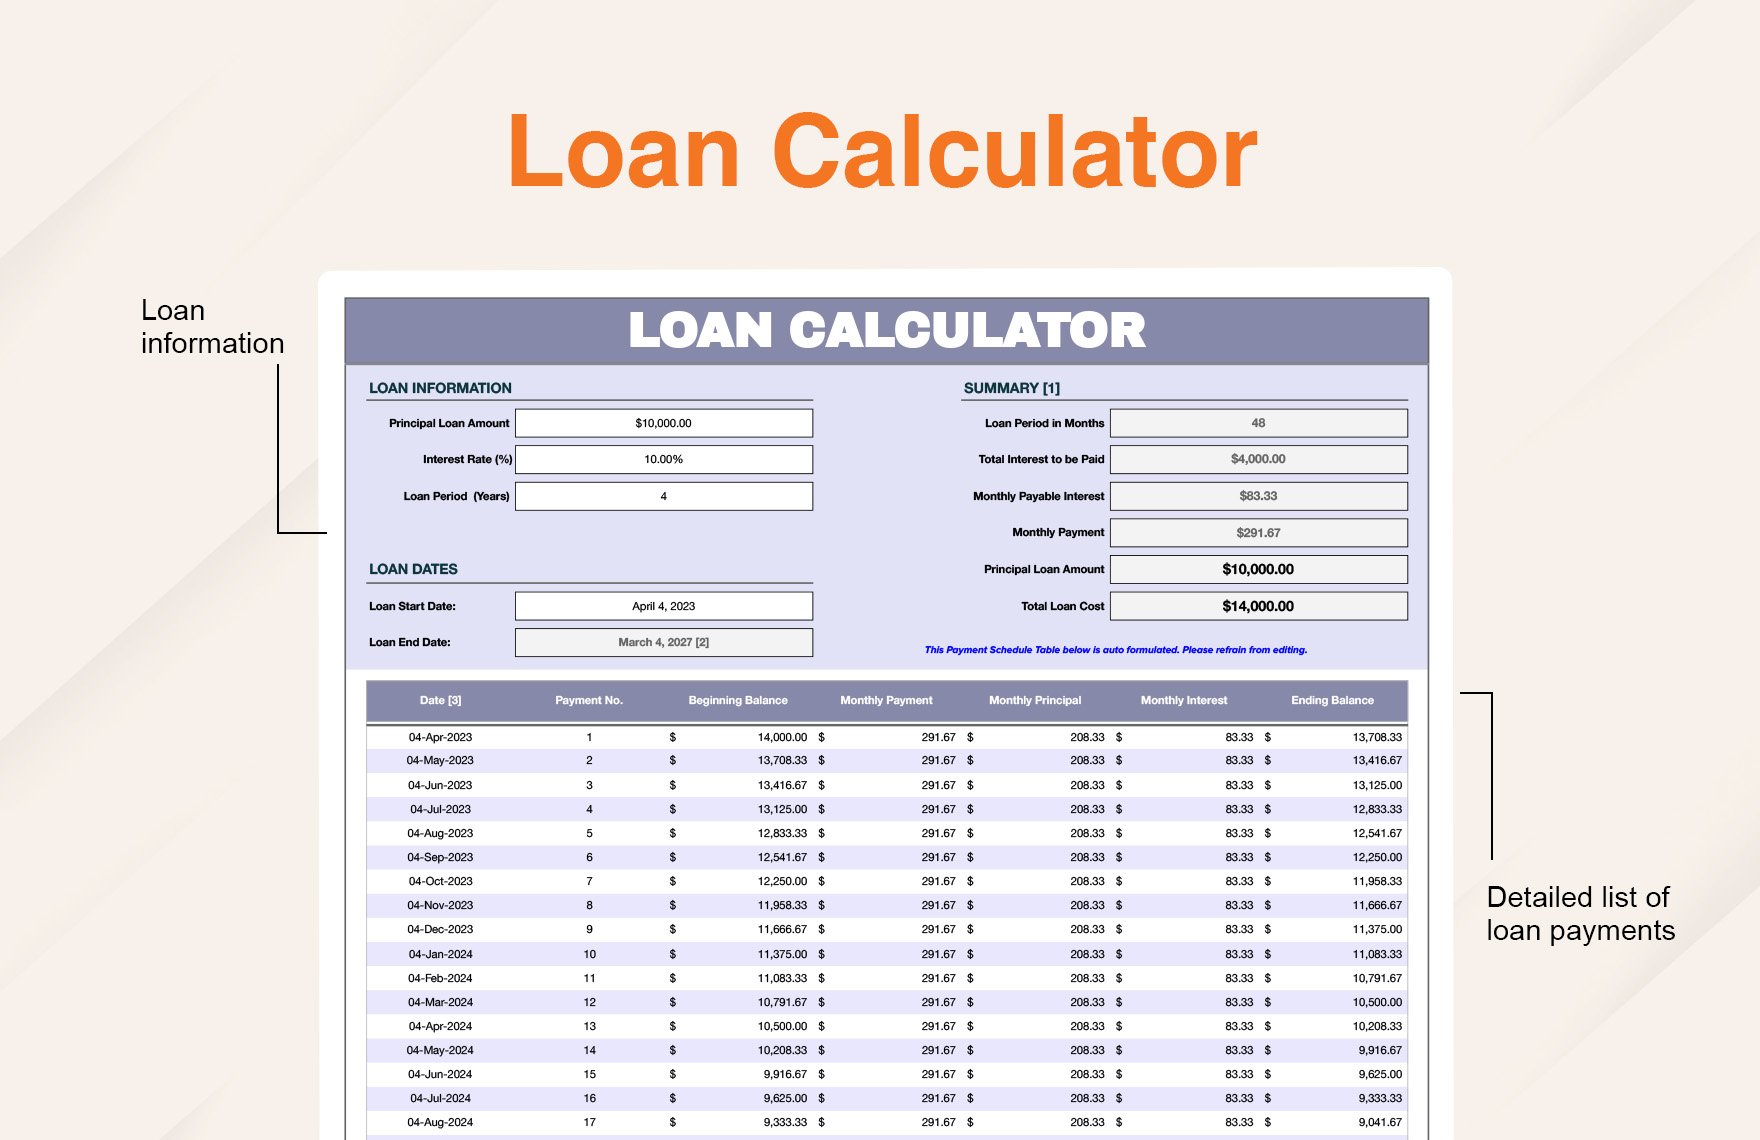
A Semi Loan Calculator figures out what your installments look like when you pay twice a year instead of every month. Most people assume this just means doubling the gap between payments, but the math works differently. Interest compounds, the amortization schedule shifts, and the total cost over the life of the loan changes in ways that aren't obvious without running the numbers. First, gather the loan amount, the annual interest rate, and the total term length. Then plug those three variables into the calculator along with the payment frequency set to semi-annually. The output gives you the per-payment amount, the total interest paid over the full term, and a breakdown of principal versus interest for each period. Some tools also show you the remaining balance after each payment, which matters if you plan to pay early or refinance later. The formula behind it uses the standard annuity equation but adjusts the rate and number of periods. You divide the annual rate by two since payments happen twice a year, and you multiply the number of years by two for total periods. A 30-year loan at 6% annual rate becomes 1.5% per period across 60 periods. Running that through the calculator gives you a payment around $786 per semi-annual period, which sounds low until you realize you're only making 60 payments instead of 360 monthly ones. The payment itself is heavier, but the overall interest calculation follows the same geometry as monthly compounding.
I built a custom spreadsheet version of this because the online calculators I found all assumed monthly payments and just divided by two. That approach was wrong because it ignored the compounding frequency mismatch. When I finally got the formula right and tested it against my bank's amortization table, the calculator matched to within cents. The difference between getting it right and rounding the rate naively can add up to several hundred dollars in total interest over a long-term loan.
What People Get Wrong About Semi-Annual Calculations
The biggest mistake I see is treating a semi-annual loan like a monthly loan with fewer payments. It isn't. The effective annual rate changes when compounding periods shift. A 6% nominal rate with semi-annual compounding is not the same as 6% with monthly compounding. The effective yield is slightly higher with semi-annual, which means your actual cost of borrowing is a bit more than the quoted rate suggests. A decent Semi Loan Calculator will show you the effective annual rate alongside the nominal one, but most free online tools skip that entirely. Another pitfall is the assumption that semi-annual payments are easier to manage financially. They're not. A single larger payment twice a year can strain cash flow more than smaller monthly amounts. I had a client who switched from monthly to semi-annual on a $400,000 mortgage thinking it would simplify things. It didn't. She missed a payment once because she hadn't set aside enough, and the late fee plus the compounded interest that followed cost her more than she saved by reducing the number of transactions. The payment was roughly $1,570 each time instead of $650 monthly. Managing that kind of lump sum is harder than most people expect. There's also the prepayment question. Some lenders allow extra payments on semi-annual loans, but the rules vary. In my experience, paying down principal mid-period doesn't always reduce your next scheduled payment. Instead, the lender may recalculate the amortization schedule or apply the extra toward future periods. I learned this the hard way when I tried to pay an extra $10,000 on a commercial loan with semi-annual payments. The lender applied it to the next period rather than reducing my current payment amount, which changed my cash flow planning for the rest of the term. Always confirm the prepayment policy before you structure anything this way.
Get the Full Details
When a Semi Loan Calculator Doesn't Help
These tools break down when the loan has variable rates, balloon payments, or non-standard compounding schedules. If your interest rate adjusts annually or quarterly, a standard semi-annual calculator won't capture the shifting payment amounts. You'd need a dynamic model that reruns the calculation at each adjustment point. I've used Excel models for that, which take longer to build but give you a far more accurate picture than any static calculator. Another limitation is jurisdiction-specific rules. In some regions, semi-annual mortgage payments are standard. In others, they're rare or treated differently by regulators. A calculator designed for Canadian semi-annual mortgages won't translate directly to a loan structured under US federal guidelines, even if the numbers look similar on the surface. Always check whether the calculator you're using matches the legal framework your loan falls under. If you need something more flexible than a basic Semi Loan Calculator, building a simple spreadsheet with the core annuity formula gives you control over compounding frequency, payment timing, and early payoff scenarios. It takes about 20 minutes to set up properly, and once it's done, you can run unlimited what-if scenarios without relying on someone else's tool. The initial effort pays off quickly if you're comparing multiple loan structures or modeling different interest rate environments.