How Semi Truck Payment Calculators Actually Work
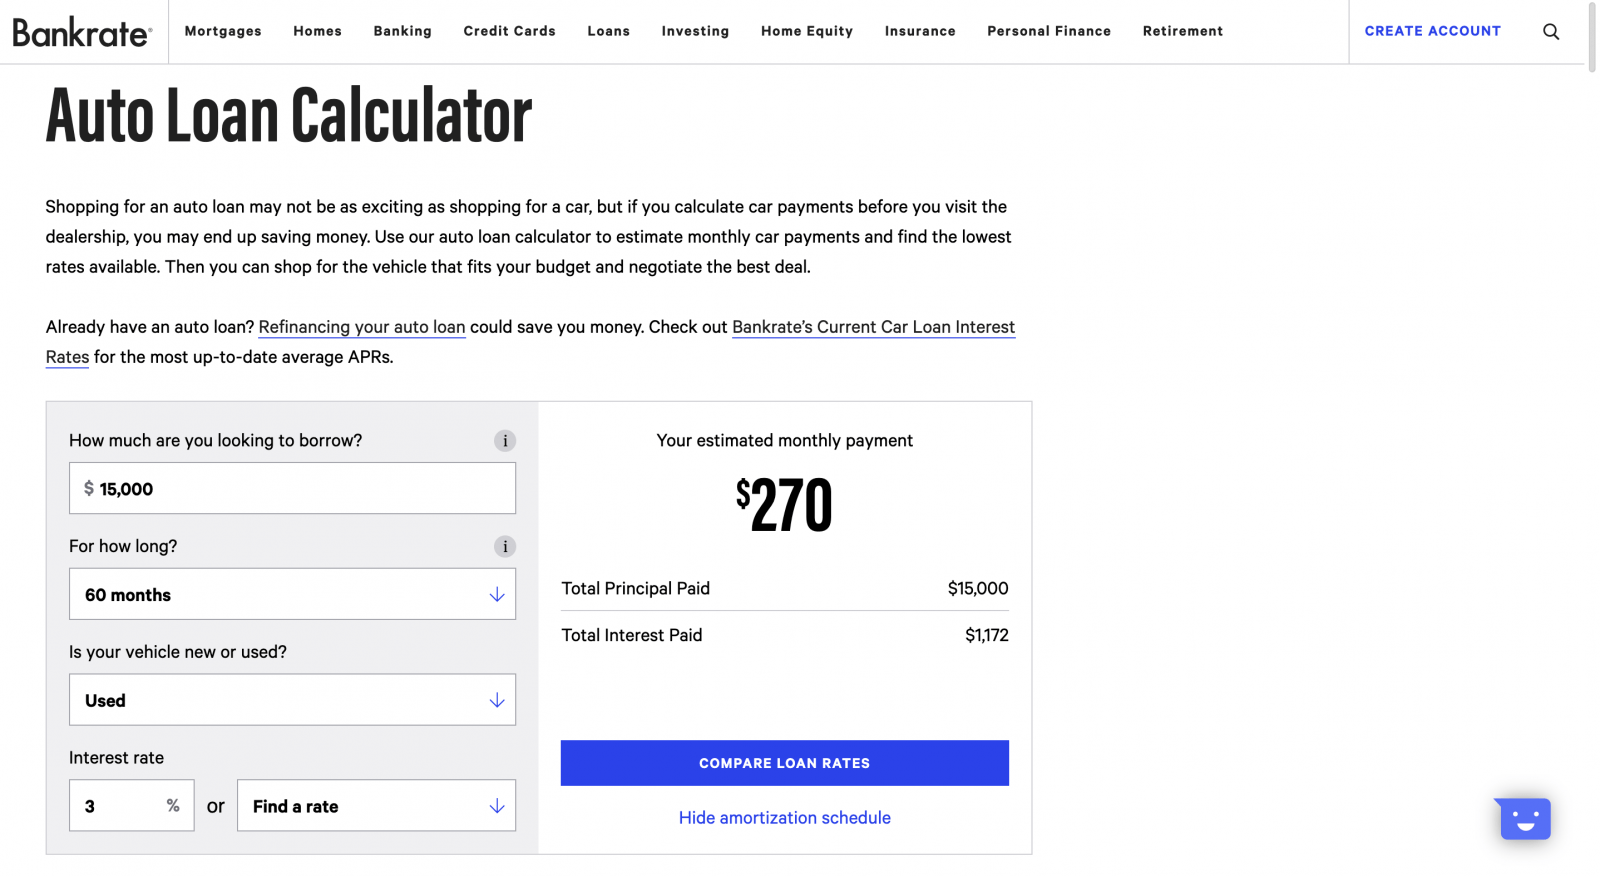
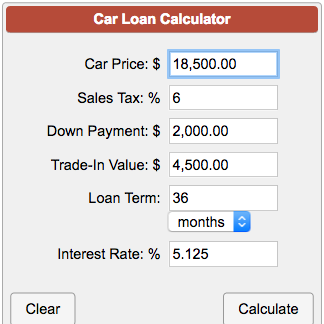
The standard formula behind a Semi Truck Payment Calculator is the amortization equation most lenders use. You take the principal amount minus any down payment, divide by the number of months in the loan term, then add interest calculated using the monthly rate derived from your APR. The result is your monthly payment. That is the theory. In practice, the numbers that come out of a calculator rarely match exactly what a lender quotes you. I have run into this dozens of times over the years. Last year I was helping a owner-operator friend review a quote for a 2023 Peterbilt 572. The calculator showed a payment around $1,347 per month at 7.8% APR over 60 months with $15,000 down on a $95,000 purchase price. The dealer's actual quote came back at $1,412. A sixty-five-dollar gap that sounded small until I realized it included a documentation fee, a tire adjustment, and prepay interest that the basic calculator does not factor in. I adjusted the principal by adding the $847 in dealer fees and recomputed, which brought the estimate within twenty dollars of the real payment. That thirty-dollar difference after adjustment is about as good as you are going to get without running the actual loan through the lender's own system.
Using a Semi Truck Payment Calculator Before You Sign Anything
The most useful way to use this tool is before you ever walk into a dealership or talk to a lender. You plug in the truck price, your expected down payment, the interest rate range you think you will get, and the loan term. Then you compare three or four scenarios. Shorter terms carry higher monthly payments but dramatically less total interest. Longer terms keep your monthly cash flow manageable but cost more over the life of the loan. Here is what most people miss when they look at the output. A 72-month loan at 8% will show a lower monthly payment than a 60-month loan at the same rate, but the total interest paid is not 20% more — it is roughly 40% more. That is because you are carrying principal longer, so each month a larger portion of your payment goes toward interest instead of reducing the balance. The upfront savings in your monthly budget are real, but the end cost is substantially higher than the headline number suggests. Another thing that catches people off guard is the down payment threshold. If your down payment is under 20% of the truck value, most commercial lenders will add a gap insurance charge or bump your rate by half to a full percentage point. Running a quick calculation with a 15% down payment versus a 20% down payment will show you exactly where that rate bump lands in your monthly number. Sometimes it is a five dollar difference. Sometimes it is thirty. The gap insurance alone can add another twenty to forty dollars a month.
Where the Calculator Fails You
These tools do not account for taxes, registration, fuel surcharge clauses, or the fact that your actual APR might be higher than the rate you see advertised. Lenders often quote best-case rates to fleet buyers with strong credit. Owner-operators with a single truck and limited revenue history frequently receive rates two to four points higher. If the calculator uses 6.5% but you qualify for 9%, your real payment could be $100 to $150 more per month than the estimate. The calculator also treats every dollar of principal the same. It does not know that part of your loan might be rolled into a line of credit for maintenance reserves or that your lender may require a minimum balance that changes how interest compounds. If you are financing a used truck with a balloon payment structure, the calculator will show you the monthly for the amortized portion but will not highlight the lump sum due at the end, which can be twenty to thirty percent of the original loan amount. If you need accuracy, take the numbers from the calculator and run them through the lender's own payment estimator. Most regional trucking lenders and credit unions have their own calculators that already include the fee structures and rate tiers they actually use. The difference between a generic online tool and a lender-specific one is usually between five and fifteen dollars per month, but that gap can widen if your loan has unusual terms like a seasonal payment option or a deferred interest period.
Get the Full Details

What to Track Beyond the Monthly Payment
Your monthly truck payment is only one piece of the operating cost picture. A typical class 8 truck runs between $0.55 and $0.85 per mile in operating expenses when you factor in fuel, insurance, tires, maintenance, and depreciation. Your payment sits on top of that. If your calculated payment is $1,400 a month and you drive 120,000 miles annually, that payment adds roughly $1.40 per mile to your cost basis. Combine that with fuel at $3.50 per gallon and a 6.5 MPG average, and your per-mile cost jumps quickly. The practical workaround is to calculate your break-even rate per mile before you commit. Take your total monthly fixed costs — payment, insurance, parking, licensing — divide by your expected monthly miles, and compare that number to what you expect to charge per mile as a carrier or owner-operator. If the math does not work at your target rate, the calculator has done its job by showing you the payment upfront so you can adjust the truck price, increase the down payment, or extend the term before you sign. It is faster to change numbers on paper than to renegotiate a loan after the paperwork is filed.