How the Sequoia Capital Pitch Deck Template Actually Works
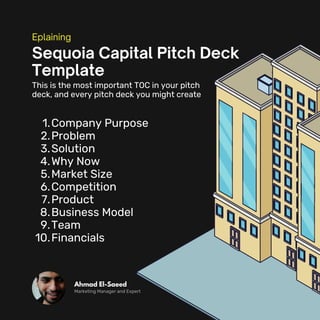
Sequoia doesn't publish an official downloadable template file. What exists is a well-known 10-12 slide framework they've outlined across blog posts, talks, and their Silicon Valley pitch deck guidelines over the past decade. People call it the "Sequoia Capital Pitch Deck Template" because the structure is consistent enough that every startup in the valley learns to follow it. The slides are: Problem, Solution, Why Now, Business Model, Underlying Magic, Market Size, Competition, Team, Traction, Financials, and Ask. That's it. The trick is that each slide has a specific job and very little room to breathe. Your deck should be clear enough that someone can flip through it in under three minutes and understand what you do, why it matters, and why you're the right person to do it.
Using the Sequoia Capital Pitch Deck Template in Practice
Here's how I actually use it when reviewing decks or helping founders prepare. I open the file and read it like a VC would: quickly, looking for reasons to pass. If a founder wants to get past that first screening round, the template matters because it matches how investors parse information. The Problem slide needs one clear sentence. Not a paragraph. Not a story. A single sentence that states what pain point exists and who feels it. I've seen decks where the problem section took up three slides. That's a problem in itself because the investor has already scrolled past you. The Solution slide should visually demonstrate the product. A screenshot or a simple diagram works better than words. The underlying magic slide is where most founders fumble. This is your technical moat or unfair advantage. If you don't have a defensible position, say so honestly on this slide rather than pretending you do. VCs can tell.
The Why Now slide is the one I see getting skipped the most, and it's usually a mistake. The window matters. If the reason your company exists right now instead of five years ago isn't clear, investors assume you're too early or too late. A single paragraph with two or three specific catalysts—regulatory changes, technology shifts, behavioral changes—is enough. I ran into a situation a couple years ago where a Series A founder had perfectly followed every slide in the template but still got rejected by four firms before closing. The issue wasn't the deck structure. It was that their Market Size slide used a top-down TAM calculation that came out to $4 billion. When I dug into their actual revenue and expansion path, the bottom-up number was more like $80 million. She had padded TAM to match what she thought investors wanted to see. I told her to replace it with the real number and add a note about expansion vectors. The next two firms that reviewed the deck offered term sheets. Investors reward honesty in market sizing more than they reward ambition. The Business Model slide needs three things: who pays, how much they pay, and how you acquire them. Unit economics belong here or in Financials. Don't bury your CAC or LTV in a spreadsheet slide unless you're presenting to a partner who specifically asked for them.
Get the Full Details

Where the Template Falls Apart
The biggest limitation of this framework is that it assumes you have traction to show. If you're pre-product or pre-revenue, some of these slides become exercises in speculation. I've seen early founders try to fill the Traction slide with beta interest, waitlists, and letters of intent. It rarely works because seasoned investors can distinguish between commitment and curiosity within a glance. If you're truly pre-traction, the Team and Problem slides become your most important real estate. The team slide isn't just a lineup of headshots and LinkedIn URLs. It's evidence that you've solved hard problems before, in adjacent spaces, with the resources you'll actually have. A founder who sold a company, then worked at Google, then launched two failures with a new cofounder carries different weight than a founder with two successful exits. Be specific about what track record matters for this particular problem. Another nuance people miss: the order of slides can be changed deliberately if your narrative supports it. Some of the best decks I've seen lead with Market Size or Traction instead of Problem. That's fine as long as you're not hiding a weak spot by rearranging. Moving the Ask slide to the beginning is almost always a bad move. Investors need context before they evaluate your funding request.
Financial projections on the Financials slide are usually wrong. I don't say this to be dismissive. Revenue forecasts at the early stage are guesses dressed up as models. What investors actually want to see is your assumptions laid out clearly so they can stress-test them. A simple table showing base case, upside, and downside scenarios with the key variables that drive each one is worth more than a twenty-row projection model you built in Excel and didn't explain. The Ask slide should state exactly how much you're raising, what currency, and roughly how long it will last. Then break down the use of proceeds into three categories: product, go-to-market, and operations. Don't list twelve line items. Three buckets is all anyone remembers. File format matters more than people admit. Send a PDF, not a Google Slides link, not a Keynote file. A PDF can't break, can't be accidentally edited, and opens consistently on every device. I've had decks fail to render because a founder sent a .key file to an investor on a Windows machine. Don't let a format issue be the reason your pitch gets filed without review.
If your company doesn't fit the standard startup profile—if you're building infrastructure, deep tech, or a company that will take seven years to reach meaningful revenue—the template will feel restrictive. In those cases, I'd suggest borrowing the Problem and Solution sections but replacing the rest with a technical deep-dive structure that explains the science, the validation milestones, and the path to commercialization. Sequoia's own portfolio includes companies where the deck looked nothing like their template. The template is a default, not a rule. The total time from a blank document to a investable deck using this framework is usually around four hours for someone who has their content ready. Most of that time goes into editing the Problem and Solution slides until they can't be misread. Once you have that clarity, the remaining slides fill in quickly because they're mostly factual.