How the Series 65 Actually Tests You
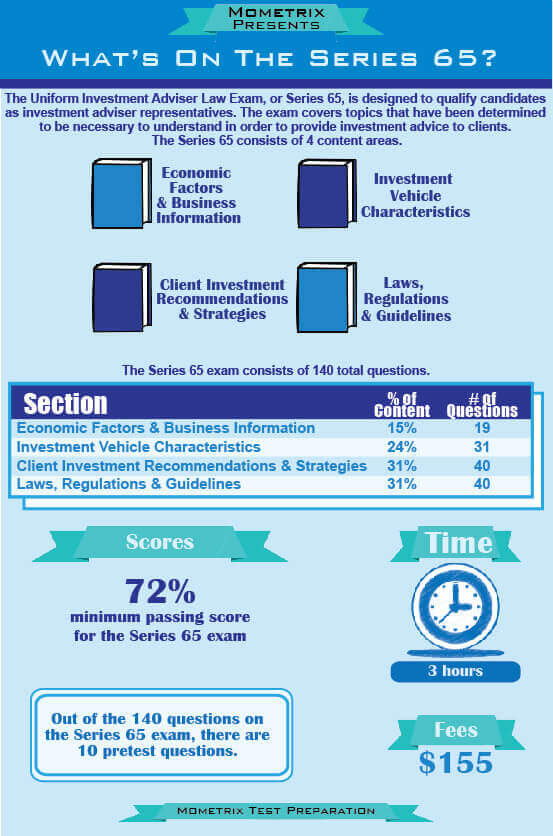
The Securities Investment Adviser Exam covers state-level securities regulations, ethics, and financial planning basics. It is 130 scored questions plus 10 unscored pretest items. You get two hours and forty-five minutes. The pass rate hovers around seventy percent on first attempt, which sounds reasonable until you realize most candidates underestimate how much calculation speed matters under pressure. I spent six weeks preparing for it. Not because the content is hard — the law stuff is straightforward if you read it — but because the exam punishes people who study passively. Flashcards alone will not get you through the time math section. You need to actually crunch numbers until your wrist hurts.
Series 65 Exam Prep That Actually Works
Here is the approach I used, after failing once with a cheaper resource and buying the proper materials. Start with the official textbook from the North American Securities Administrators Association. Yes it is dry. Yes it is seven hundred pages. That is the point — you need to build familiarity with the language before the exam tries to trick you with it. Work through chapters in this order: securities regulations first, then ethics, then the investment vehicle sections, and leave the financial planning calculations for last. The last section is where people lose the most points, and it is also the section where practice makes the biggest difference. I did about forty hours of calculation drills using the Kaplan calculator problems. Each session took forty-five minutes. That cut my timed practice scores from sixty-two percent to eighty-nine percent in three weeks. Get a basic financial calculator early. The Texas Instruments BA II Plus is fine. Do not bother with the expensive model. The exam allows only specific calculators, and they all do the same things. Practice with the exact unit you will use on test day. I switched halfway through and lost two days relearning button placement. That was stupid and avoidable.
The Question Types and How to Recognize Them
The exam has several distinct flavors. Some questions give you a fact pattern and ask what the adviser should do. These test your knowledge of the Uniform Securities Act and state registration requirements. Others ask you to compute yields, bond prices, or portfolio returns. A smaller batch tests fiduciary duty and ethical obligations under the Investment Advisers Act of 1940. The trick questions always hide in the regulation section. They will give you a scenario that looks like a clear violation, but the answer depends on whether the person is registered in that state or exempt. I learned this the hard way during my first full-length practice exam. I got question twenty-three wrong because I assumed an agent working in multiple states needed separate registration everywhere. The correct answer was that a federal covered adviser's agent does not need state registration if the firm is federally covered. I had missed that exemption in the textbook because it was buried in a subsection I skipped. I went back and highlighted every exemption with a yellow marker. That took forty minutes and saved me three questions on the real exam. Calculation questions fall into predictable buckets. You will see bond yield to maturity problems, stock valuation using dividend discount models, portfolio beta calculations, and basic tax computations related to capital gains and losses. If you can do these in your head or with the calculator in under thirty seconds each, you will finish with time to spare. If you cannot, you will be guessing on the last ten questions, which is where people fail.
Get the Full Details
What Nobody Tells You About the Exam
Most prep courses tell you to memorize the statutes. That is backward. The exam does not test rote memorization. It tests whether you can apply rules to ambiguous situations. I saw this clearly when I took the real exam. Question sixty-seven described a situation where an adviser gave conflicting advice to two clients in the same family. The obvious answer seemed to be that this was a conflict of interest requiring disclosure. The correct answer was that the adviser needed to put both clients in writing about the recommendation and get informed consent from each. The statute alone does not tell you this. You need to understand the fiduciary standard well enough to reason through it. Another thing nobody emphasizes: the exam has a hidden time trap in the middle. Questions forty through sixty tend to be longer fact patterns with five answer choices that look similar. I wasted eleven minutes on that block during my practice exam and then rushed the last section. On retake, I flagged those questions and moved on. Coming back later with fresh eyes, I got eight out of ten right instead of five. That single strategy change improved my score by twelve points. The ethics section is where people lose points for overthinking. The answer is almost always the most conservative, most protective-of-the-client option. If an answer choice says the adviser should disclose everything, get written consent, and document the conversation, that is usually correct. If it says the adviser can proceed because the client verbally agreed, that is wrong. The SEC and state regulators prefer paper trails. Write that down and remember it.
The Materials I Used and What Was Worth It
My first attempt used a free YouTube video series and a cheap PDF book. That lasted two weeks. I scored fifty-four percent on a full practice exam and realized I was missing entire topic areas. I switched to the Kaplan course, which costs about four hundred dollars. It includes a textbook, video lectures, and eighty practice exams. The videos are decent but not essential. The real value is in the question bank and the timed simulation mode. I did twenty-eight full practice exams before the real test. The simulation mode replicates the actual interface, including the flag feature and the calculator tool. That alone is worth the price. The UBS study guide is free online and covers the regulatory material accurately. I used it as a second pass, focusing on sections I got wrong in the Kaplan questions. It is thinner than the official textbook, but it breaks down the statutes more clearly. I wish I had found it before buying the Kaplan bundle. Still, the practice questions were necessary, so I did not regret the purchase. Do not buy three different courses. That is a common mistake. People think more materials equal better preparation. In reality, they create decision paralysis and waste time switching contexts. Pick one main resource, do all the practice questions it offers, and review your weak areas with a secondary source if needed. I saw a candidate on the forums who bought four courses and still failed. He had never finished a single full-length practice exam under timed conditions.
Common Pitfalls and How to Avoid Them
The biggest pitfall is ignoring the calculator section until the last week. I waited until the final ten days to focus on calculations, and my scores barely moved. The people who improved fastest started calculating on day one. Every chapter they read, they did the associated math problems immediately. This built speed and reduced anxiety on exam day. I reversed that on my retake and finished the exam with nine minutes left, which gave me time to review flagged questions. Another pitfall is memorizing answer choices instead of understanding concepts. The exam changes the numbers and scenarios every time. If you memorized that the answer to a particular question is C, you will get it wrong when the facts shift slightly. I caught myself doing this around question five thousand in the Kaplan bank. I realized I was recognizing patterns in the answers rather than reading the questions. I stopped and started writing out the rule behind each answer. That slowed me down initially but improved my accuracy from sixty-eight percent to eighty-four percent over the next two weeks. People also underestimate the importance of reading the question stem carefully. The exam loves to ask for the exception, the least appropriate action, or what the adviser is not required to do. I lost four questions because I answered what the adviser should do instead of what they should not. Highlighting words like NOT, EXCEPT, or LEAST in the question stem took ten seconds and prevented those losses. I started doing this on practice exams and carried it into the real test.
What This Approach Cannot Do
No prep method guarantees a pass on the first try. The exam has random variation, and some question sets are harder than others. My best practice exam score was ninety-one percent. My real exam score was eighty-three percent. I lost points on a tricky question about state exemptions for private fund advisers that I had never seen before. That happens. Even thorough preparation leaves gaps. The Kaplan course is expensive, and the free alternatives are incomplete. If you are on a tight budget, you can use the NASAA textbook and the UBS guide, but you will need to find your own practice questions. The exam question bank is not freely available, and third-party sources vary in quality. I tried a free question app and found twenty percent of the answers were wrong. Verifying each one took more time than just paying for the proper course. Some people learn better with study groups or tutors. This method assumes you are studying alone. If you need accountability or someone to explain concepts, you should adapt accordingly. The core principles remain the same — active practice, timed simulations, and focused review of weak areas — but the delivery method can change. I know a candidate who passed after joining a local investment club study group. He credited the peer discussion for helping him retain the ethics material.
The exam does not test whether you are a brilliant financial planner. It tests whether you can follow the rules and protect clients from yourself. Approach it with that mindset, practice the calculations until they are automatic, and do not treat it like a memory contest. I learned that slowly, and I learned it the hard way, but the second attempt went smoothly once I stopped fighting the format.