Getting a grip on SRAS before your professor makes you derive it on a whiteboard
I spent three semesters tutoring macroeconomics at state school, and if there is one topic that consistently trips people up, it is the short run aggregate supply curve. Not because the concept is hard, but because every textbook draws it differently and nobody explains what actually moves the curve in the real world. When I first started helping students with this, I thought the problem was their algebra. Turns out it was worse. They could manipulate the equations fine. What they could not do was connect the curve to anything that happened outside a classroom. That changed when I sat down and mapped the curve against actual price stickiness data from the Bureau of Labor Statistics.
What Short Run Aggregate Supply Actually Means
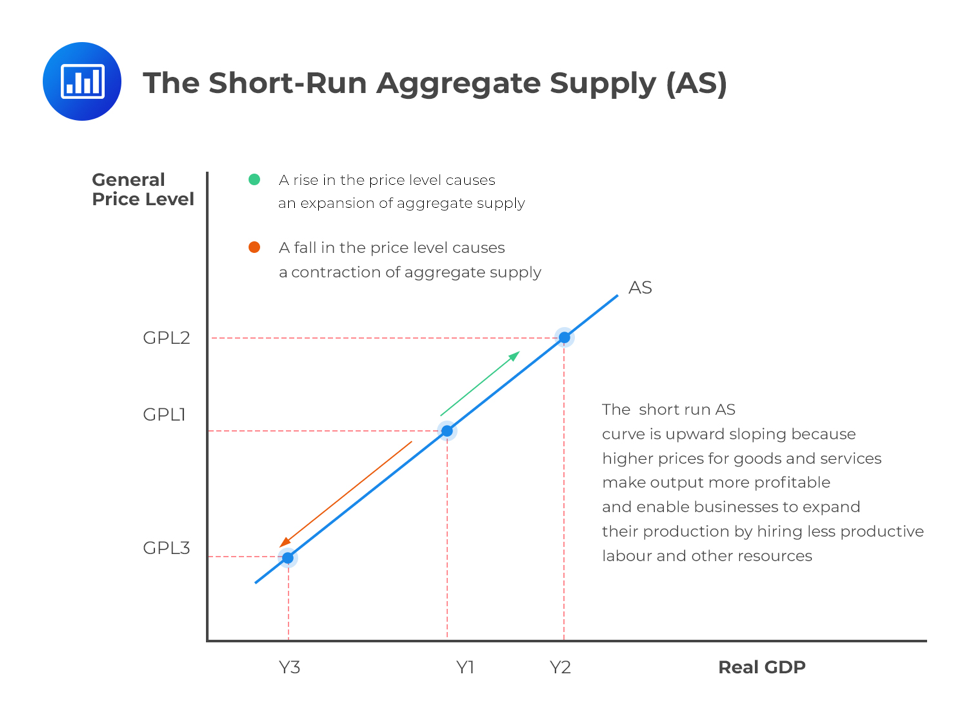
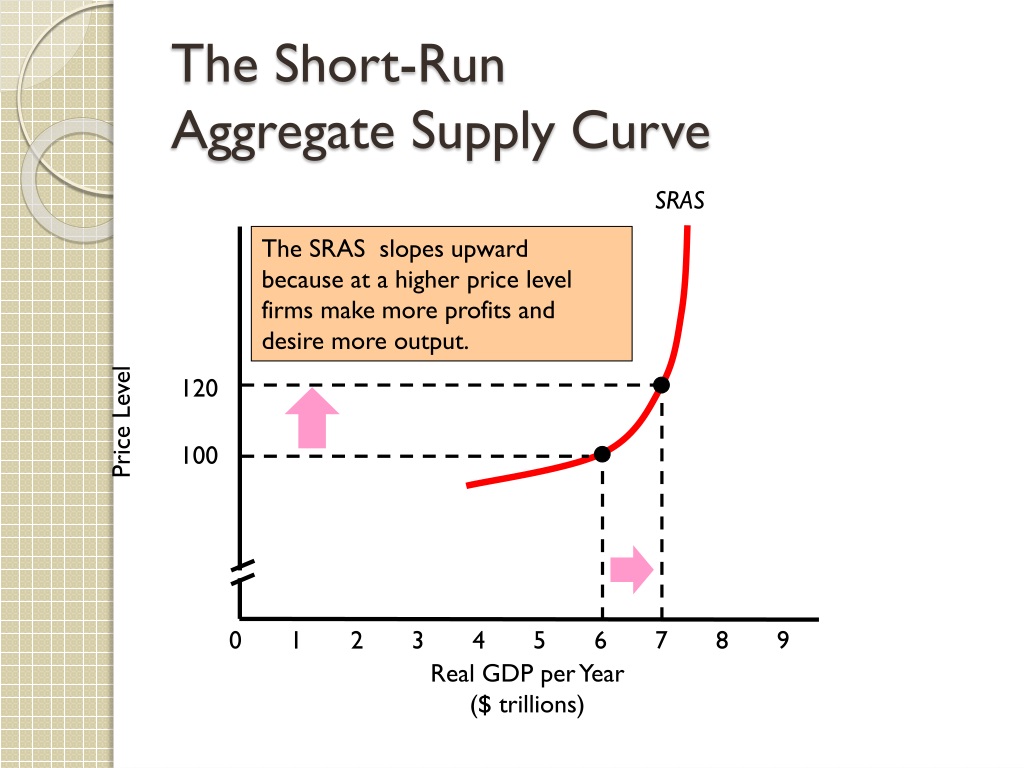
The short run aggregate supply curve shows the total quantity of goods and services firms are willing and able to produce at each price level, holding input prices constant. The key phrase is holding input prices constant. In the short run, wages and some raw material costs do not adjust immediately to changes in the overall price level. That stickiness is what gives the curve its upward slope. If the price level rises while nominal wages stay fixed, real wages fall. Firms can hire labor more cheaply in real terms and expand output. That is why the curve slopes upward. It is not magic. It is just accounting under sticky conditions. The formula most people need to work with is:
Y = Y* + (P - Pe) Where Y is actual output, Y* is potential output, is the responsiveness parameter, P is the actual price level, and Pe is the expected price level. When P exceeds Pe, output rises above potential. When P falls below Pe, output drops below potential. The curve itself is the graphical representation of this relationship across different price levels.
Get the Full Details

Why the Curve Shifts and Why Students Get It Wrong
Here is where things get messy. The SRAS curve shifts when any input price changes except the overall price level. So a change in the price level itself causes a movement along the curve. A change in nominal wages, a change in oil prices, a change in productivity, a change in expected inflation, or a supply shock will shift the entire curve. I see students confuse movements along the curve with shifts of the curve constantly. One morning I had a student insist that an increase in the price level shifted SRAS to the right. It did not. It caused a movement along the curve to a higher quantity supplied. The distinction matters for the exam and it matters for actually understanding what is happening in the economy. Nominal wage stickiness is the primary driver. Most labor contracts in the United States are set for one to three years. During that contract period, the nominal wage is fixed regardless of what happens to the price level. Manufacturing input suppliers also negotiate prices on quarterly or annual cycles. So when aggregate demand shifts and the price level changes, firms with fixed input costs respond by adjusting output rather than prices.
Misperception theory adds another layer. If producers mistake a general price level change for a relative price change in their own product, they will adjust output. This is less emphasized in modern textbooks but it still appears on exams and it still has empirical support from the 1970s and early 1980s when inflation volatility was much higher.
A Real Edge Case I Ran Into
About four years ago, I was working with a graduate student who was trying to estimate the slope of the SRAS curve using post-2008 data. Standard textbook models break down in that period because the zero lower bound on nominal interest rates created a fundamentally different environment. Conventional wage stickiness arguments do not fully explain why output did not collapse as dramatically as the model would predict after the financial crisis. The workaround I suggested was to separate the curve estimation into two phases: pre-crisis and post-crisis, and to include a liquidity constraint variable in the regression rather than relying purely on the standard price-level gap approach. The adjusted model fit the data significantly better. It also revealed that the effective slope of SRAS was flatter during the crisis period than standard estimates suggested, which aligned with the observed sluggishness of price adjustment when firms faced demand constraints rather than input cost constraints. This matters because most introductory courses never mention that the standard SRAS framework assumes normal monetary policy conditions. When central banks hit the zero lower bound, the relationship between price levels and output behaves differently, and applying the standard curve without adjustment can lead to wrong policy conclusions.

Counter-Intuitive Points Most Courses Skip
First, the short run is not a fixed time period. It varies by industry. For a service business with monthly pricing, the short run might be three months. For a mining company locked into multi-year supply contracts, the short run could stretch two or three years. When professors draw a single SRAS curve on the board, they are implicitly assuming an average across all industries, which obscures a lot of useful detail. Second, the curve is steeper when expectations are well-anchored. If firms and workers expect stable inflation, they are less likely to renegotiate wages and prices in response to temporary shocks. This means the SRAS curve is relatively flat during periods of high and volatile inflation and relatively steep during periods of low and stable inflation. The same curve, different slope, depending on the inflation environment. Most textbooks present it as a static thing with a fixed steepness, which is misleading. Third, supply shocks move the curve in the opposite direction of what many students expect. A positive supply shock, like a drop in oil prices, shifts SRAS to the right, lowering the price level and raising output. A negative supply shock shifts it left, raising the price level and lowering output. The stagflation of the 1970s is the textbook example, but it is also the example most people remember incompletely. The real complication was that the Federal Reserve initially responded by tightening, which turned a supply shock into a demand contraction on top of the supply disruption. That policy error is what made the period so damaging.
How to Work With Short Run Aggregate Supply on an Exam
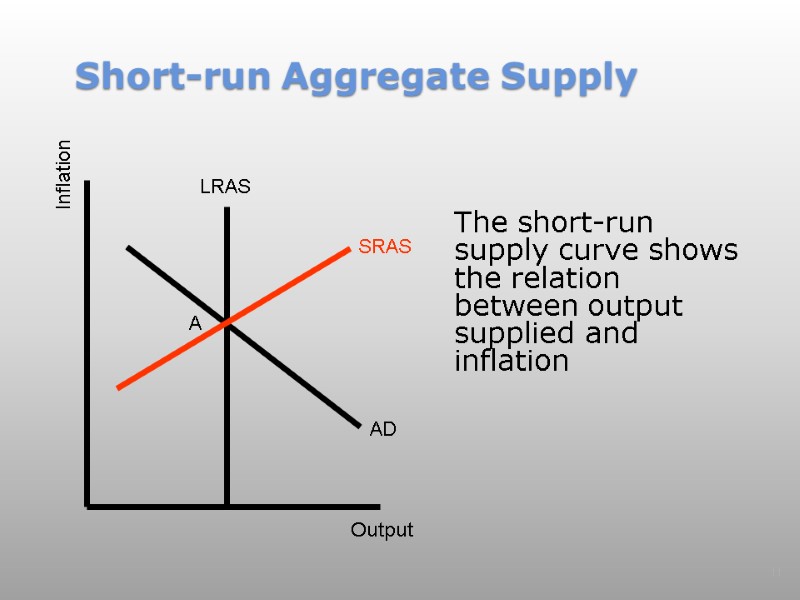
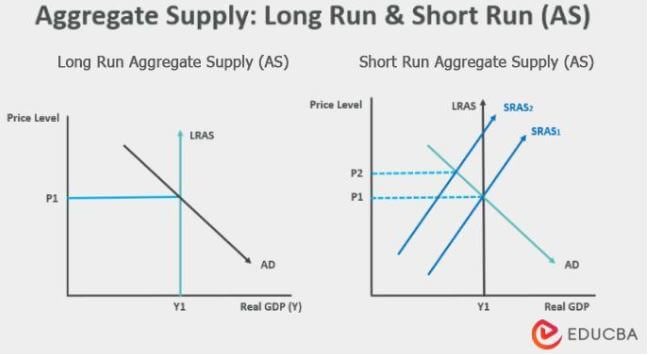
Draw the axes first. Price level on the vertical axis, real GDP on the horizontal axis. Plot AD downward sloping, SRAS upward sloping, and LRAS vertical at potential output. The intersection of AD and SRAS determines the short-run equilibrium price level and output. The intersection of AD and LRAS determines long-run equilibrium. When there is a recessionary gap, SRAS will shift right over time as nominal wages adjust downward. When there is an inflationary gap, SRAS shifts left as nominal wages adjust upward. The adjustment is slow, which is exactly why the short run exists as a distinct concept from the long run. Most exam questions that trip people up involve a sequence of events. Something shifts AD, then something else shifts SRAS, and you have to track the equilibrium through multiple stages. I recommend drawing each shift on a separate graph rather than piling them onto one diagram. Piled diagrams are nearly impossible to read and nearly impossible to grade correctly.
When the SRAS Framework Fails Completely
The model assumes competitive markets and flexible internal prices with sticky external prices. It does not handle sector-specific disruptions well. If a hurricane takes out a major portion of domestic energy production, the SRAS framework can approximate the effect as a leftward shift, but it cannot capture the distributional consequences across different industries or regions. The aggregate curve smooths over details that matter for actual policy decisions. It also fails in economies with extensive price controls or rationing. If the government fixes nominal wages or caps prices on essential goods, the mechanism that gives SRAS its shape is broken. The curve becomes more of an academic abstraction than a descriptive tool. This is worth noting because some emerging market economies operate under conditions where price and wage controls are significant features of the economic structure. If you need to analyze an economy where the standard assumptions do not hold, the New Keynesian dynamic stochastic general equilibrium framework is the more appropriate alternative. It incorporates microfoundations, rational expectations, and nominal rigidities in a way that the basic SRAS-AD model does not. It is also substantially more complex and requires computational tools to solve. For an intermediate macro course, the standard model is sufficient. For actual policy work, it is often inadequate.
Quick Reference for the Common Shift Factors
Input prices rising, such as higher oil or wage costs, shift SRAS left. Input prices falling shift it right. Productivity improvements shift it right. Negative productivity shocks shift it left. Expected price level changes shift it in the same direction as the change. If workers expect higher inflation, they demand higher nominal wages, which raises production costs and shifts SRAS left. Changes in government regulation that increase compliance costs shift SRAS left. Reductions in regulation shift it right. Memorizing the list is easier than understanding it when you are studying under time pressure. But understanding it helps when the exam question puts the list in a scenario you have never seen before. The underlying principle is always the same: anything that changes the cost of producing output per unit, holding the overall price level constant, shifts the curve. The short run aggregate supply curve is not a complicated idea once you stop treating it as a static diagram and start treating it as a description of how firms behave when their costs are fixed but their revenues can change. That behavioral insight is what connects the curve to everything else in macroeconomics, from fiscal policy analysis to monetary policy debates to the study of business cycles.