Why Short Selling Actually Works (And Why It Keeps Losing People Money)
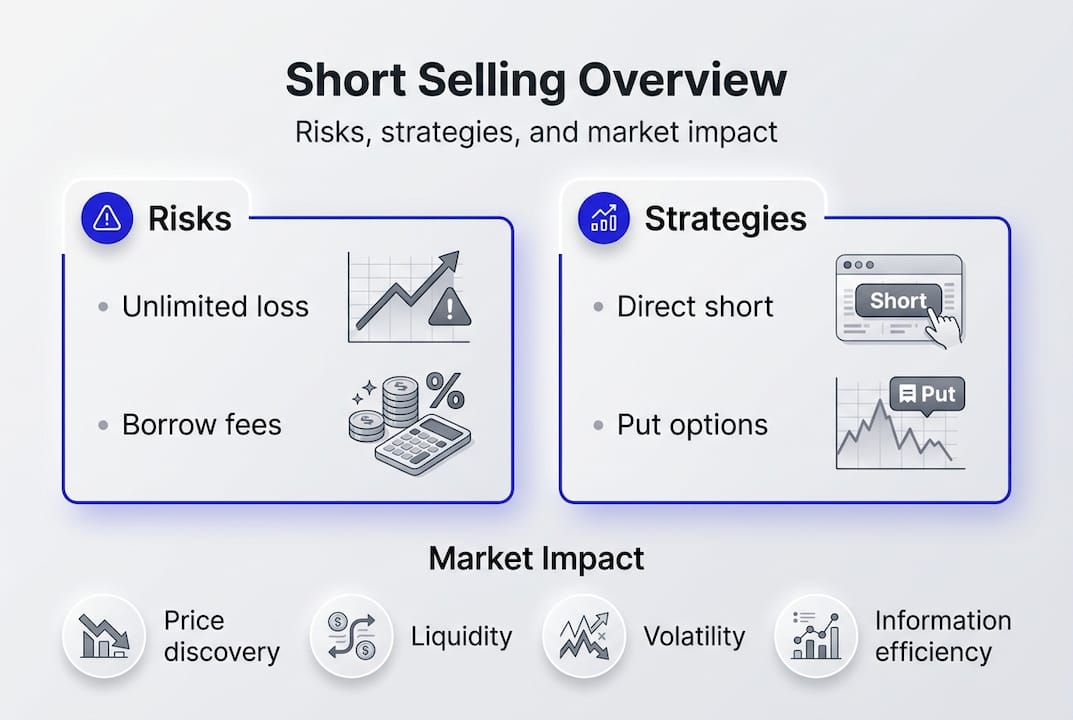
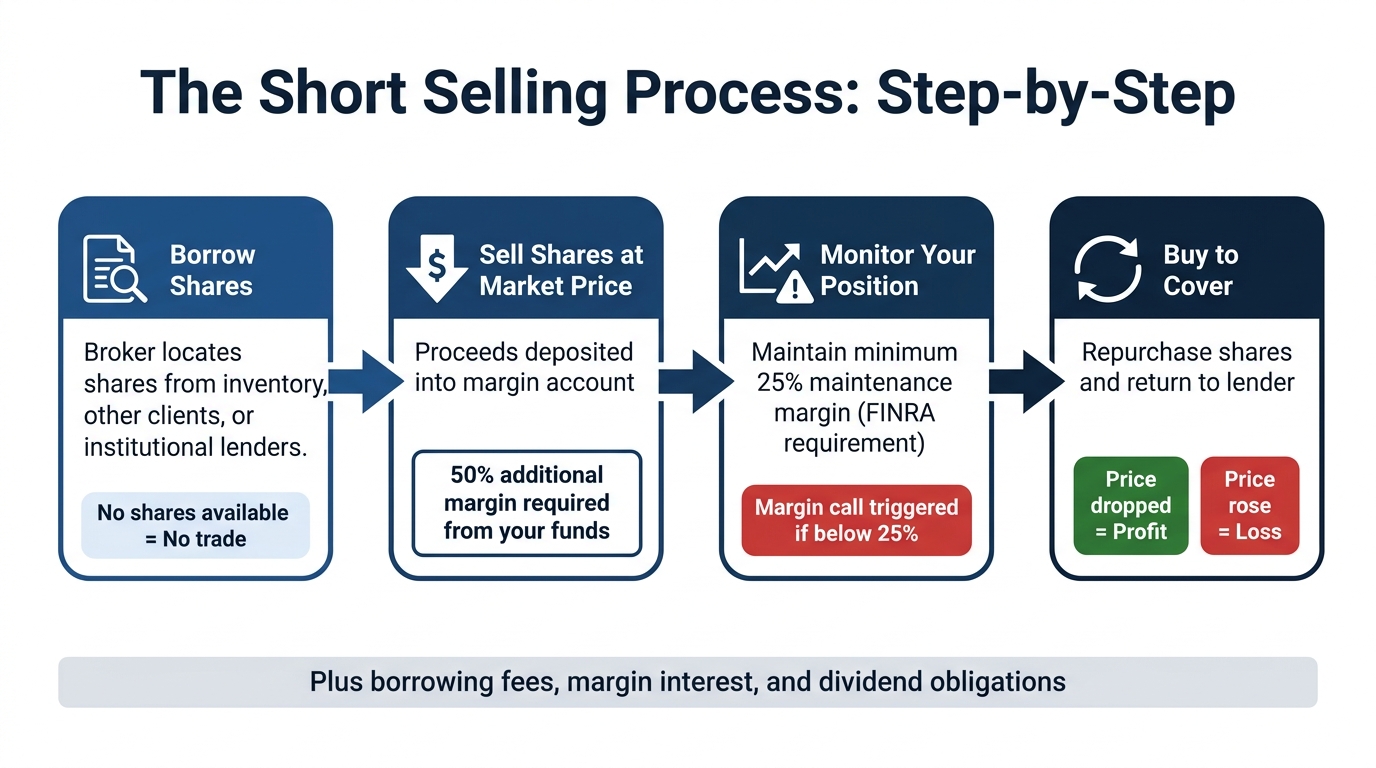
I've been doing this for long enough that I've watched three different short squeezes take down retail accounts that swore they were "safe." The basic mechanics are simple: you borrow a stock, sell it, wait for the price to drop, buy it back cheaper, and pocket the difference. Most people who read about short selling online treat it like a puzzle to solve. It's not. It's a war of attrition against market makers, hedge funds, and your own emotions. Let me start with the part nobody warns you about. When you short a stock, you don't just lose money if it goes up. You can lose more than your initial investment because there's no floor on how high a stock can climb. Your maximum gain is capped at 100% (if the stock goes to zero). Your maximum loss is theoretically infinite. The math alone should make anyone nervous. The most common approach beginners use is called "conventional shorting." You open a margin account, request to borrow shares through your broker, and place a sell order. That's it mechanically. The problem is that finding borrowable shares has become a nightmare since 2020. Many stocks that were easy to short three years ago now carry borrow fees of 15%, 20%, sometimes 50% annualized. If you're shorting a stock at a 30% borrow fee and the stock drops 5%, you've essentially made nothing after fees.
I learned this the hard way in early 2022. I had a position shorted in a mid-cap tech stock at a reasonable borrow rate. Two weeks in, the lender decided they wanted their shares back. My broker issued a mandatory buy-in notice. I had to cover at exactly the wrong time, right as the stock was rallying on earnings news. I lost about 18% on that trade, and the worst part was I couldn't exit gracefully because the mechanics of the squeeze were working against me, not my thesis.
Actual Strategies That Professional Short Sellers Use
Pair trading is one of the few strategies that actually reduces risk meaningfully. You short one stock while going long on a similar stock in the same sector. If the short thesis plays out, you profit from the short leg and your long leg either gains or loses less. This was popularized by hedge funds like Soros's Quantum Fund in the 1990s and it's still the most intellectually honest way to short. The problem is it requires two concurrent positions and twice the margin requirement. Convertible arbitrage is another professional approach. You short the underlying stock and buy the convertible bonds issued by the same company. The bonds provide a floor and some upside protection while your short position profits from downside. This is sophisticated, capital-intensive, and honestly something most retail traders should just avoid. But it's important to know it exists because when you see a stock get hammered, convertible arbitrageurs are often the ones doing the shorting. The short interest ratio strategy is what retail traders usually mean when they talk about "catching a short squeeze." The theory is straightforward: identify stocks with unusually high short interest relative to float, monitor for catalysts that could force short sellers to cover, and buy ahead of the squeeze. The counter-intuitive part that nobody mentions is that high short interest itself becomes a signal. By the time short interest hits 20% or 30%, smart money already knows about it. You're usually the last person in, not the first.
Get the Full Details
How to Actually Execute a Short Sale
You need a margin account. Regular cash accounts cannot short sell. Your broker will require at least 50% of the position value as collateral under Regulation T, though most brokers ask for 150% or more. Then there's thelocate rule - you have to confirm the shares are actually available to borrow before your sell order can execute. This used to be a formality. Now it's a daily struggle. Once your position is open, you'll pay daily borrowing fees that get extracted automatically from your account. These are usually expressed as an annual percentage rate but charged daily. On a $10,000 short position at 8% annual borrow cost, you're paying about $2.19 per day. That adds up to roughly $800 per year just to hold the position, whether you're winning or losing. This fee structure is one of the biggest hidden costs in short selling and completely changes the risk-reward calculus on longer-term shorts. Stop losses on short positions work differently than you'd expect. A standard stop-loss order doesn't work well because when you set a buy-stop, you're telling your broker to buy the stock back at a higher price. In a fast-moving short squeeze, your order might execute significantly above your stop price due to slippage. I once placed a stop at $45 on a stock that was shorting at $40. The squeeze pushed it to $52 before any fill. The gap between my stop and my actual fill cost me an extra $12 per share that I hadn't budgeted for.
The Risks Nobody Talks About
Dividend risk is real and painful. When you're short a stock, you owe the lender any dividends declared during your position. If a company declares a $2 dividend and you're short 100 shares, you just lost $200 whether the stock goes up or down. I've seen short sellers get caught off guard by special dividends that completely wiped out their thesis gains in a single day. Voting rights disappear while you're short. You can't influence shareholder meetings or proxy votes. For activist short sellers who build positions based on governance concerns, this is a genuine strategic limitation. Some institutional shorts work around this by lending their shares to proxies or using derivative structures, but that's beyond retail capability. Regulatory risk has increased dramatically since 2010. The SEC's short sale rule (Regulation SHO) requires you to locate shares before selling short and has introduced circuit breakers that can halt shorting in volatile securities. During the GameStop episode, the SEC temporarily banned short selling on over 500 financial stocks. If you're short and a ban hits, you can't exit. Period. I watched several colleagues lose money on positions they couldn't close for days because of this.
There's also the psychological toll. Short selling creates a fundamentally asymmetric emotional experience. When you're long, a stock dropping 10% feels like a opportunity to buy more. When you're short, that same 10% drop feels like panic because you're losing money on every tick. Studies show that short sellers experience significantly higher cortisol levels and decision fatigue than long-only traders. This isn't theoretical - I've seen seasoned traders make terrible covers during squeezes because they were emotionally compromised, not logically wrong.

When Short Selling Completely Fails
The clearest example is momentum-driven retail campaigns. Stocks like GameStop in January 2021, Bed Bath & Beyond in 2022-2023, and similar cases demonstrate that fundamental analysis becomes irrelevant when a large enough group of retail traders decides to coordinate buying. No amount of good short thesis matters when there are more buyers than shares available. The short interest ratio, borrow costs, and margin calls create a feedback loop that forces covering regardless of fundamentals. Another failure mode is central bank intervention periods. During aggressive monetary easing or QE programs, asset prices detach from fundamentals temporarily. Short sellers who bet against overvalued markets in 2009-2010 or 2020-2021 lost money for years before being vindicated. Timing is everything, and timing is the one thing short sellers can't control. If you're going to short sell, keep position sizes small - never more than 5% of your portfolio on any single short. Use stop losses liberally and accept that they'll slip. Monitor borrow costs daily and exit immediately if they spike. Consider pair trades over naked shorts whenever possible. And for god's sake, never short a stock just because it's "too expensive" - that's how you go broke slowly over many years.
The rewards of short selling are real but concentrated among people who treat it as a specialized skill requiring constant monitoring, not a strategy you set and forget. Most retail traders are better off avoiding it entirely or limiting themselves to small, well-hedged positions. The market pays you for patience and discipline when you're short, not for conviction or hope.