Working With Simple Interest
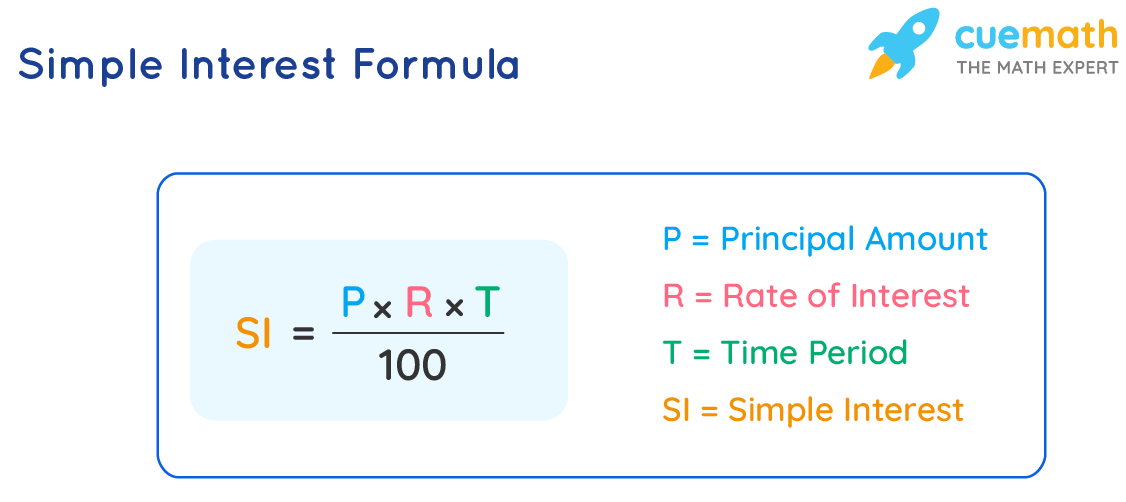
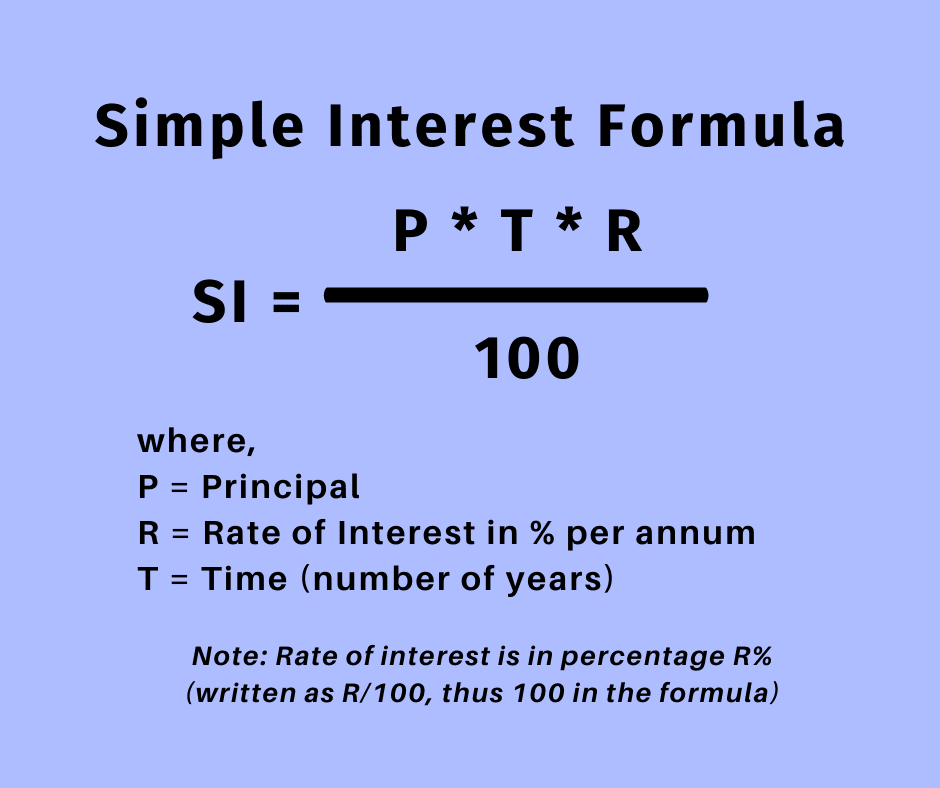
I ran into a problem last year that made me rethink how I approach this entirely. A client wanted interest calculated on a construction loan that had a partial payment made mid-term. They expected the standard formula to just work. It didn't, not without adjustment. The principal dropped after six months, and using the original amount for the full term gave a number that was off by over four hundred dollars. That's when I stopped treating this as a plug-and-chug exercise and started paying attention to the variables that actually move the needle. The Simple Interest Interest Formula is I = P × R × T. That's it. I is the interest amount. P is the principal, the starting balance. R is the annual rate expressed as a decimal. T is the time in years. People skip the part where every one of those four letters needs to be correct before you get a usable number. A rate entered as 5 instead of 0.05 will cost you more than just embarrassment.
Where the Simple Interest Interest Formula Actually Comes From
It's multiplication stacked on itself. If you lend someone money at a fixed annual rate, the interest each year is the same flat amount. There's no compounding. There's no accelerating growth. It's linear. That linearity is what makes it fast to calculate and what makes it dangerous to trust blindly for anything longer than a few years. I've seen loan officers use this formula for terms stretching into decades and never question why the returned numbers felt too clean. They were. That's the thing about simple interest. It produces clean numbers. Clean numbers aren't always right numbers.
How to Set Up the Calculation Properly
Start by converting the rate. Take whatever percentage you're working with and divide by one hundred. Five percent becomes zero point zero five. Six and a quarter percent becomes zero point zero six two five. Write it down. Don't trust your mental math with fractions. Next, convert the time. If you're looking at months, divide by twelve. Days are trickier because different lenders use different day-count conventions. Some use three sixty, meaning they assume every month has thirty days and the year has three hundred sixty. Others use three sixty-five, which is just the actual calendar. I've lost track of the number of disputes that came from this single assumption. When I'm unsure which convention applies, I ask the lender directly and write the answer in the file. It takes thirty seconds and saves a lot of follow-up calls. Then multiply. P times R times T gives you the total interest. Add that to the principal and you have the total amount due. Nothing complex here unless you're working with variable time periods or partial payments, and that's where the real work starts.
Get the Full Details
Edge Cases I've Dealt With
The construction loan I mentioned earlier had a principal reduction at month six. The formula itself doesn't know that happened unless you tell it. What I do now is split the calculation into two segments. I calculate interest on the full principal for the first six months. Then I recalculate using the reduced principal for the remaining term and add the two interest amounts together. That's not in the formula. You have to layer it on manually. Another issue shows up with short-term deposits. A ninety-day certificate of deposit at four percent on one thousand dollars looks like a straightforward calculation. Under the three sixty convention, it's one thousand times zero point zero four times ninety over three sixty, which gives you exactly ten dollars. Under actual days, it's one thousand times zero point zero four times ninety over three hundred sixty-five, which gives you about nine point eight six dollars. That fourteen cent difference sounds negligible until you're doing this across hundreds of accounts or when the deposit is twenty thousand dollars instead of one thousand. Then it's eighty dollars, and someone is going to notice.
What Beginners Miss About This Formula
The biggest blind spot is assuming the rate and the time period match. If you're using a monthly rate, T should be in months. If you're using an annual rate, T needs to be in years. Mixing them is the most common error I see, and it's not subtle. A quarterly rate applied to a yearly time frame without dividing the rate by four produces an answer that's four times too high. I check this by doing a quick sanity test before finalizing anything. I estimate roughly what the interest should be in my head, and if my calculator answer is wildly different, I go back and find where the units got misaligned. A second thing nobody tells you is that simple interest favors the borrower in many real-world lending scenarios, but it favors the lender when comparing it to amortized loans. A loan structured with simple interest over a long term will show less total interest paid than an amortizing loan, but only because the principal isn't being paid down during the term. At maturity, the borrower owes the full original principal plus all accumulated interest. That balloon payment catches people who don't read the fine print.
When This Formula Breaks Down Completely
Simple interest stops being useful the moment you need accuracy over multi-year horizons where the time value of money matters. If you're comparing two investment options and one pays simple interest while the other compounds annually, the simple interest option will look better than it actually is for anything beyond a single period. Over five years at five percent, one thousand dollars grows to one thousand two hundred fifty under simple interest. Under annual compounding, it's one thousand two hundred seventy-seven point six three. The gap widens every year. By year ten, you're looking at one thousand five hundred versus one thousand six hundred twenty-eight point eighty-nine. The formula still works. It just gives you a number that doesn't reflect reality for most financial products. If you're dealing with compounding, use the compound interest formula instead. A = P times one plus R over N to the power of N times T, where N is the number of compounding periods per year. It's not harder to use. It's just different, and it matches what banks and investment accounts actually use. For quick calculations without thinking about conventions or edge cases, I use a spreadsheet with the rate and time columns clearly labeled. It takes about two minutes to set up, and once it's done, I can run through a batch of calculations in about fifteen minutes instead of spending twenty minutes on each one. The formula itself is two seconds. The setup is where the time goes, but it pays off after the third calculation.