How Card Skimmers Actually Work in the Real World
I've seen enough of this over the years to know people have a fundamentally wrong idea about how common and effective these devices are. A lot of folks treat skimming like something from a movie. It isn't. It's boring, it's been around since the late 90s, and it works because humans are predictable and machines are too convenient. At its core, card skimming involves attaching a device to an existing card reader that captures the magnetic stripe data when someone swipes their card. The device reads the track data, stores it, and then passes through the legitimate transaction so the victim never notices anything happened. That captured data gets sold on underground markets, usually for $5 to $30 per card depending on the balance and card type. The more sophisticated setups also install a microscopic keypad overlay or a hidden camera to capture the PIN. Without the PIN, you can still run transactions on cards that don't require one, like many credit cards in the US, but with the PIN you can pull cash directly from ATMs in other countries where the fraud might not get flagged for weeks.
I remember running into this back around 2014 when I was doing fraud consulting work. We had a case where a regional gas station chain was losing money but couldn't figure out why. Turned out someone had installed skimmers on the in-store card terminals, not the pumps. The tellers were swiping cards at the counter like normal. What tipped us off was that the fraudulent charges all came from the same geographic cluster but were made at different businesses entirely, which meant the card data was being reused across multiple terminals, not just that one location. The fix was straightforward once we confirmed it. We pulled the terminal logs, cross-referenced the timestamps of the suspicious transactions against the transaction records from each terminal, and found the overlap. Then we physically inspected the hardware. One of the terminals had a thin plastic shell over the card slot that was nearly invisible from a standing angle. It cost about twelve dollars to make and took ten seconds to pop on.
Types of Skimming Devices You Should Know About
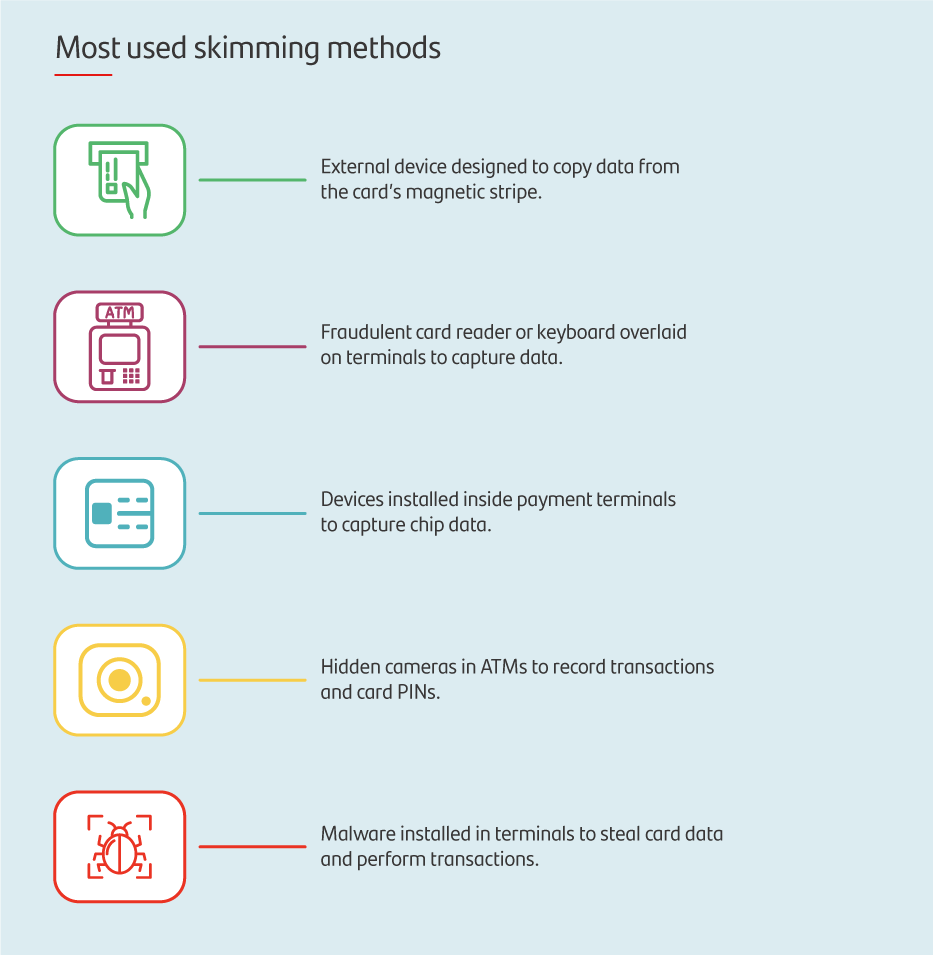
There are really three categories that matter in practice. The first is the overlay skimmer. This is the most common type. It snaps onto the card reader slot of an ATM or point-of-sale terminal and reads the magnetic stripe as the card passes through. These are cheap to buy online and even cheaper to manufacture. You'll find them at gas stations, retail stores, and ATM vestibules in apartment buildings where nobody checks the hardware. The second category is the internal skimmer. These are more invasive. Instead of attaching to the outside, someone has to open up the terminal and install a device inside that intercepts the card data before it reaches the encryption module. These are harder to detect because there's no visible modification to the exterior, but they're also harder to install and remove. You usually only see these in cases where the perpetrator had some level of physical access to the machine, either through insider knowledge or by working for the maintenance contractor.
Get the Full Details

The third type is the camera-based approach. This doesn't skim the card itself but captures the PIN entry. A tiny pinhole camera is mounted somewhere in the terminal housing pointing down at the keypad. The person installing it knows which keypad has a decorative plastic cover over part of it that hides the camera lens. These are often paired with an overlay skimmer for complete card data capture.
How Card Readers Got Better (And Why It Didn't Help Much)
EMV chip cards were supposed to solve this problem. They did, sort of. When you insert a chip card, the chip generates a unique transaction code that can't be reused. Even if someone skims the data from a chip card, that captured information is mostly useless for card-not-present fraud because the chip transaction data is encrypted and tied to that specific transaction. But here's what most people don't understand. EMV didn't kill skimming. It just moved it. Magstripe cards still exist everywhere, especially internationally, and many people still swipe their cards when the chip reader isn't working or when they're in a hurry. Gas pumps are the worst offender here. A lot of them still default to magstripe reading even when chip insertion is available. I've watched people swipe their chip cards at pumps multiple times because it was faster than waiting for the chip transaction to process. Those swipes are exactly what skimmers are waiting for. Also, contactless payment hasn't solved this either. Contactless uses tokenization similar to EMV, but it's not foolproof. There have been documented cases of malicious NFC readers placed near contactless payment terminals that can capture the token data during a tap transaction. The data is still encrypted, but if you're using the same token repeatedly, it becomes valuable in the right context.
What Actually Works to Prevent It
The most effective thing is terminal tamper switches. These are small sensors built into legitimate card readers that detect when the housing has been opened or when an external device has been attached. When triggered, the terminal locks up and displays a tamper alert. The problem is that not every terminal has these enabled, and some older models don't support them at all. If you're running a business and your card reader is more than five years old, check with your processor to see if tamper detection is active on your specific model. Regular physical inspection matters more than you'd think. I've seen business owners go months without looking at their own card terminals. A quick visual check once a week takes about thirty seconds and catches most overlay skimmers. Look for anything that doesn't sit flush, any slight misalignment of the card slot, or any additional plastic pieces that weren't there before. Also check the keypad area for anything that looks thicker than it should be. For ATMs specifically, the best practice is to cover the keypad with your hand when entering your PIN, regardless of whether you think there might be a camera. It's an annoying habit but it's the single most effective thing an individual can do. Most people skip this because they've never heard of a hidden camera, which is exactly the point.
Why Some Approaches Don't Help as Much as People Think
Signal jamming devices, which some people sell as ATM protection tools, are basically useless against modern skimmers. These devices emit radio frequency noise to interfere with the skimmer's data transmission. The problem is that most contemporary skimmers store the data locally and transmit it later via cellular or internet connection, not in real time. A jammer might delay the transmission by a few hours, which gives the cardholder time to report the fraud, but it doesn't prevent the data capture itself. The skimmer still has the card data even if it never sends it out. Another misconception is that chip-only terminals are immune. They aren't. While the chip transaction data is more secure, there are still attack vectors. I worked a case last year where a restaurant chain in the Midwest had skimmers installed on their portable card terminals. These are the handheld devices servers use to take payments tableside. The skimmers were internal, meaning they were inside the terminal housing alongside the legitimate reader. The cards being swiped were mostly magstripe because the servers were accustomed to the faster swipe motion. When the victims tried chip insertion, the terminal rejected it because the chip readers had been disabled by the internal skimmer installation. So the victims just swiped, which is exactly what the criminals wanted. The workaround in that case involved pulling the terminal software configuration and comparing transaction types across locations. The affected terminals showed a disproportionate number of swipe transactions compared to chip insertions, which is unusual because most customers prefer chip these days. Once we flagged those terminals, we physically removed them and replaced the hardware. The skimmer inside one of the terminals was about the size of a business card and sat directly behind the magstripe reader module.
The Undermarket Side of This
Understanding how skimming data moves after it's stolen helps explain why prevention is so important. The typical flow is: skimmer captures data, data is retrieved by the operator or a courier, the data is uploaded to a dashboard on a dark web marketplace, and then buyers purchase the card details. Fullz packages, which include the card number, expiration date, CVV, and sometimes the cardholder's name and address, sell for anywhere from $15 to $100. Card-only packages are cheaper, usually $5 to $15. The buyers then use that data for either card-not-present fraud, where they make online purchases, or they clone the card onto a blank magstripe card for in-person use. ATM cloning is where fullz packages with PINs get the most value because cash withdrawals are harder to trace back to a specific fraud ring. The entire transaction ecosystem moves fast. Data harvested on a Tuesday can show up in fraudulent charges by Wednesday. That's why rapid detection and response matter more than any single preventive measure. If you run a business and suspect skimming, contact your payment processor immediately and request a terminal audit. Don't wait for the monthly reconciliation to reveal discrepancies. Fraud losses that get caught in the regular cycle are usually already out the door and far more expensive to recover.
There's also a legal dimension most people ignore. In the United States, skimming falls under the Computer Fraud and Abuse Act and various state-level financial fraud statutes. Penalties range from misdemeanors to federal felonies depending on the scale and whether it crosses state lines. Most skimmers operate in small localized rings rather than large organized crime groups, which is why these cases often get solved through local surveillance footage and routine fraud investigation rather than federal task forces. The reality is that skimming persists because the barrier to entry is so low and the enforcement response is so inconsistent. A plastic overlay costs less than a cup of coffee. The penalty for getting caught, unless you're running a large-scale operation, is often mild. That economic reality isn't going to change, so the only effective countermeasure is making the physical act of installation and retrieval more difficult and more visible to anyone who actually looks.