What It Actually Feels Like When The Market Slaps You
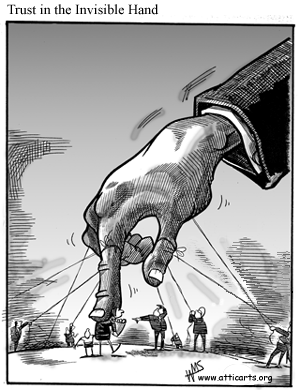
I spent seven years working in supply chain logistics before I ever heard the phrase used in a real meeting. Not in a textbook either. A procurement lead at a mid-size manufacturer said it across a whiteboard during a crisis where raw material prices had spiked overnight and his team had just committed to three months of fixed-price contracts. He looked at the spreadsheet, looked at us, and said exactly: we got slapped by the invisible hand. That was the first and last time I heard it used naturally in a professional setting. The invisible hand is Adam Smith's idea that individuals pursuing their own self-interest unintentionally benefit society through market forces. Getting slapped by it means those same forces hit you negatively despite your best planning. You priced a product correctly. You signed the right contracts. You hedged your bets. And then the market adjusts, and you are on the wrong side of the adjustment. This is not abstract philosophy. It happens when interest rates shift, when a competitor undercuts pricing without revealing why, when a regulation quietly changes enforcement overnight, when consumer sentiment swings because of a single viral moment. The market does not care about your five-year plan. It never has.
How To Recognize It Before It Hits You
Most people notice the invisible hand only after they have already been slapped. The useful skill is spotting the early signals. These are the ones that matter in practice. Margin compression without cause. Your costs have not increased. Your overhead is stable. Revenue is flat. But gross margins are shrinking month over month. Something in the pricing environment is shifting, and usually it is demand elasticity or a quiet race to the bottom among competitors who are also feeling pressure. Unexpected volume spikes that damage fulfillment. A small demand surge seems like a good problem. Then you realize your suppliers cannot scale, your carriers are prioritizing larger accounts, and your customer satisfaction drops faster than revenue climbs. The market rewarded you with volume and punished you with operational collapse simultaneously.
Regulatory or policy noise that precedes real impact. I tracked a municipal ordinance change in my city that looked cosmetic. It was not. It restricted commercial loading zones in a way that increased last-mile delivery costs by roughly eighteen percent for anyone operating in that district. Companies who had negotiated long-term leases in that area absorbed the cost. We did not, because we were using third-party logistics. The invisible hand adjusted, and we felt it three months later. The workaround was straightforward but expensive. I switched our district deliveries to off-peak hours using a combination of earlier depot cut-offs and a small satellite warehouse we rented for sixty days. It cost about fourteen thousand dollars total and saved us from losing the contract with a regional grocery chain. That is the thing about getting slapped. The remedy is almost always available. It just usually costs more than the original strategy.
Get the Full Details

Why Traditional Risk Models Miss This Completely
Beta values, VaR calculations, historical regression. These tools assume the future resembles the past. The invisible hand operates precisely where the past stops being useful. Markets adapt. Participants adapt faster. The equilibrium you modeled six months ago no longer exists. A counter-intuitive reality is that hedging can make you more vulnerable, not less. When you lock in prices to protect against volatility, you remove your flexibility. If the market moves in your favor you lose the gain. If it moves against you and your hedge was sized incorrectly you take a double hit. I watched a manufacturing client hedge copper at three dollar per pound and then see it drop to two forty. They were locked in. They also held excess inventory at the higher price. Total loss was approximately two hundred thousand dollars on a single material category. Their risk model had told them they were protected. The more useful approach is scenario flexibility rather than price locking. Build optionality into contracts. Negotiate volume bands instead of fixed quantities. Keep supplier relationships diversified enough that you can pivot within thirty days without penalty. This costs slightly more upfront but prevents the kind of slap that bankrupts mid-size operations.
When The Invisible Hand Is Not The Problem
Sometimes you get slapped and it feels like market forces. It is not. It is bad internal execution dressed up as external blame. Here is how to tell the difference. If competitors are facing the same pressure and your data shows your unit economics are structurally weaker than theirs, the issue is internal. If everyone in your segment is getting squeezed and you are the only one losing margin rapidly, the issue is likely internal. If you can identify a specific decision you made six months ago that directly caused the current pain, stop calling it the invisible hand and fix the decision. Most operators conflate the two because admitting internal failure is harder than blaming market forces. The market will take the blame for you. That convenience is exactly what causes repeated damage.
Practical Steps To Insulate Yourself
Keep a rolling twelve-month view of your primary input costs and map them against your pricing tiers. When any input moves more than five percent in a single quarter, trigger a contract review. Do not wait for the annual renegotiation. Build a list of alternative suppliers for every critical input. Not preferred vendors. Real alternatives with proven capacity. I maintain one for packaging materials, one for semiconductor components, and one for freight brokers. Having the list is useless if you have never validated it. Call each alternative quarterly. Confirm they can fulfill at stated terms. This takes about forty-five minutes per cycle but prevents emergency scrambling when something breaks. Monitor leading indicators in your specific industry rather than relying on lagging economic reports. Consumer sentiment indexes come out monthly. Your niche may shift weekly. Set up simple alerts for price movements in your top five inputs. When you see movement you can adjust before it moves you.

Accept that some slaps are unavoidable. No model, no hedge, no contingency plan prevents every negative market adjustment. The goal is reduction, not elimination. The operators who survive are the ones who treat market surprise as a normal operating condition rather than an anomaly that should not happen to them. I still think about that procurement lead and his whiteboard. He did not need a textbook explanation of market forces. He needed to know what to do next. The answer was always the same. Adjust fast, accept the cost of adjustment, and do not waste time assigning blame to a force that was never personal to begin with.