Working With the Solow Model in Practice
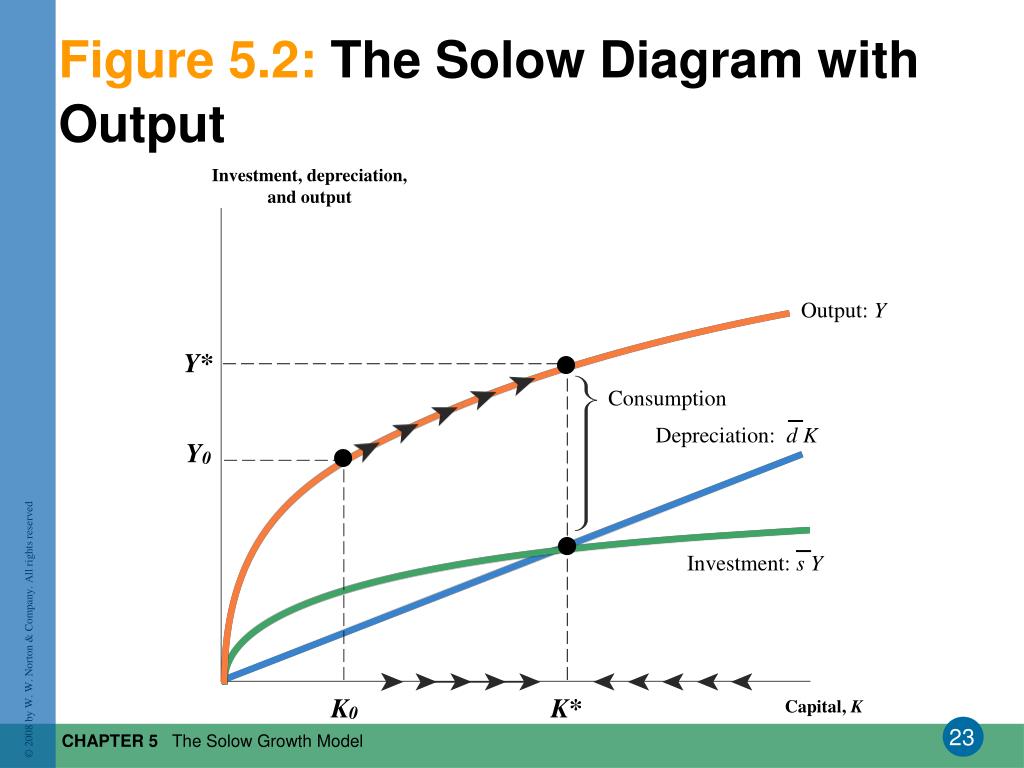
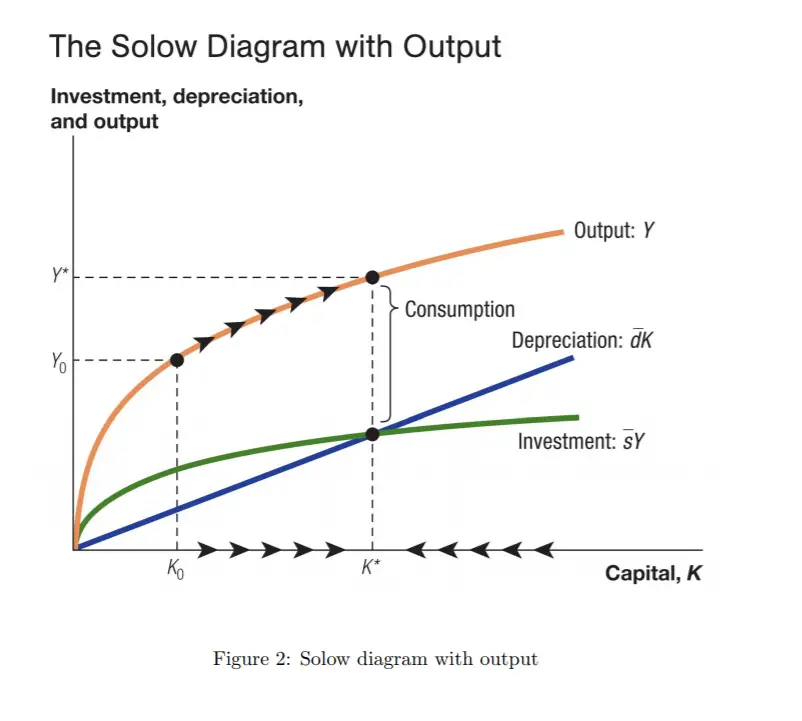
The Solow Economic Growth Model is probably the first growth framework most economics students encounter, and honestly, that's because it strips away every unnecessary complication and leaves you with something you can actually solve on paper. The core setup is simple enough: output depends on capital and labor, technology improves over time, and capital depreciates. That's it. But the things that trip people up aren't in the setup — they're in the assumptions and the transitions between steady states. Start by writing down the production function in per-worker terms. If your aggregate production function is Y = F(K, AL), where A is labor-augmenting technology, then you divide everything by effective labor to get y = f(k), where y is output per effective worker and k is capital per effective worker. The dynamics come from the equation dk/dt = s·f(k) ( + n + g)k. The first term on the right is investment per effective worker, and the second term is the break-even investment needed to keep capital per effective worker constant given depreciation, population growth, and technological progress. When these two are equal, you're at the steady state. I spent way too many hours in grad school trying to memorize the transitional dynamics without really internalizing what the equation was telling me. The key insight that finally clicked for me was that the steady state isn't some magical equilibrium the economy always reaches — it's just the point where the capital-labor ratio stops changing. If you're above it, capital per effective worker falls. If you're below it, capital rises. Period.
Calibrating the Model
Most applied work uses a Cobb-Douglas production function, so f(k) = k^, where is the output elasticity of capital. In developed economies that number is typically around 0.3 to 0.35. The depreciation rate is usually somewhere between 0.02 and 0.05 per year depending on whether you're looking at equipment or total capital stock. Population growth n for most advanced economies sits near zero or slightly negative. Technological progress g is harder to pin down but 0.015 to 0.02 annually is a reasonable benchmark for the US. Here's a realistic problem I ran into last year while building a cross-country growth simulation. I was calibrating the Solow model for a set of Sub-Saharan African countries using World Bank data, and the predicted steady-state income levels came out roughly three to four times higher than actual GDP per capita. The naive response is to say the model is wrong, but that misses the point. The issue was that I was using current investment rates without accounting for the fact that these countries haven't been converging from a low base — they've been stuck in a different regime entirely due to institutional constraints the model doesn't capture. The workaround was straightforward: I introduced a scaling factor for total factor productivity that varied by region and treated it as a residual after accounting for capital, labor, and the standard parameters. It's not elegant, but it's honest about what the model can and can't do.
Transitional Dynamics and Convergence
One thing beginners consistently miss is that convergence in the Solow model is conditional. Poor countries don't automatically grow faster than rich ones — they only converge if they share the same steady state. Two countries with different savings rates, different population growth, or different TFP levels will settle at different steady states, and the poorer one won't necessarily catch up. The conditional convergence regression is where you control for these determinants and then check whether countries that are further from their own steady state grow faster. The coefficient on the distance-from-steady-state term should be negative, and empirical estimates typically land around 0.02 to 0.03, implying a half-life of convergence of roughly 20 to 35 years. Another counter-intuitive point: an increase in the savings rate doesn't permanently raise the growth rate in the basic Solow model. It raises the level of output per effective worker in the new steady state, but the growth rate returns to g, the exogenous rate of technological progress. The transition itself generates temporarily higher growth for a while, but once the economy reaches the new steady state, growth is back to where it was. This is why endogenous growth models exist — they try to make the savings rate matter for long-run growth, but that comes with its own set of problems, including multiple equilibria and difficulty in estimation.
Get the Full Details

Common Pitfalls
The most frequent error I see is confusing growth in per-capita terms with growth in per-effective-worker terms. In the steady state, per-capita output grows at rate g, but output per effective worker is constant. Mixing these up leads to completely wrong predictions about long-run income levels. Another common mistake is treating the steady state as a stable equilibrium in a dynamical systems sense without checking the slope condition. For convergence to the steady state, you need f'(k*)
( + n + g)/s, which holds under standard concavity assumptions but can fail if you use a production function with increasing returns to capital. There's also the issue of measuring capital. Gross fixed capital formation data is messy across countries, and the perpetual inventory method used to construct capital stock series introduces substantial measurement error, especially for developing countries with unreliable investment data. This error is correlated with growth — countries with higher measured investment tend to have higher measured capital stocks, which can create a spurious correlation that makes the Solow model look more empirically successful than it actually is.
When the Model Breaks Down
The Solow model assumes constant returns to scale, perfect competition, and no friction in capital adjustment. Real economies don't satisfy any of these assumptions perfectly, but the biggest issue in practice is that the model treats technological progress as exogenous. You can't use it to analyze policies that affect innovation, education quality, or institutional reform because those factors are buried in the TFP residual. If you're trying to explain why some countries grow faster than others over long periods, the Solow model will tell you it's all about TFP differences, which is accurate but not particularly actionable. For policy analysis, you're usually better off moving to an augmented Solow model that includes human capital, or switching to an overlapping generations framework if you care about demographic transitions. The Romer model is another option when you want to make technological progress endogenous, though the estimation becomes considerably more difficult. There's no free lunch here — every improvement in the model's realism adds parameters that are harder to identify empirically.
A Practical Workaround I Use
When I need quick comparative statics without running a full calibration, I use the log-linearized version of the capital accumulation equation around the steady state. The approximation dk/dt (k k*) where captures the speed of convergence lets you estimate how many years it takes to close a given fraction of the gap to steady state. For typical parameter values, the convergence speed is slow enough that a country 50% below its steady state will still be significantly below it after 50 years. This is useful for sanity-checking whether a predicted growth miracle from a policy change is actually plausible within the Solow framework or whether you need a richer model to justify the magnitude of the effect.