Understanding What Actually Happens When Your HOA Hits You With a Special Assessment After a Storm
I spent about eighteen months working through the aftermath of Hurricane Ian with a mid-size condo association in Southwest Florida. The special assessment process is one of those things everyone assumes they understand until a letter shows up in your mailbox demanding $47,000 because the roof needs replacing and the reserve fund had a hole in it the size of a small swimming pool. A special assessment is a charge levied against unit owners beyond their regular monthly HOA dues. It's not a loan. It's not insurance. It's a bill for the portion of hurricane-related expenses that the association's reserves and insurance didn't cover. When Hurricane Ian made landfall in September 2022, it pushed a storm surge through parts of Florida that most people hadn't seen since 2005, and hundreds of associations discovered their reserve studies were either outdated or just plain wrong. The board has the authority to impose these assessments under most governing documents, but they're not allowed to just make it up as they go along. There are procedures. Notice requirements. Sometimes vote thresholds. These vary by state and by association, which is why the fine print in your declaration matters more than most people realize before it's too late.
Here's the thing nobody tells you: the amount you owe isn't always what you'd expect. Some associations pro-rate based on square footage. Some use equal shares per unit. A few bizarre ones still use percentage of ownership tied to units deeded back in the seventies when one person owned forty of the eighty units and nobody updated the documents. I've seen all three in my career, and the third one caused the most lawsuits.
The Real Process: How It Works From Filing to Payment
After Ian, here's roughly what happened at the associations I handled, in the order they actually occurred: Phase one — damage documentation and scope of work. The board hires an engineer or contractor to assess what the storm destroyed. This isn't cosmetic. Insurance adjusters handle the claims side. The engineering firm figures out what's structurally compromised, what needs to meet current building codes, and what the actual repair cost will be. For a typical medium-rise condo on the Gulf Coast, this phase alone runs $15,000 to $40,000 in professional fees before a single nail is driven. Phase two — insurance proceeds calculation. This is where most people get confused. The insurance payout doesn't automatically equal the repair cost. And even when it does, the association gets the check, not you directly. The board then subtracts deductibles, co-insurance penalties, and any coverage gaps from the total repair budget. Whatever's left becomes the shortfall, and that's what gets spread across owners.
Get the Full Details

Phase three — board resolution and notice. The board formally votes to levy the assessment. They must provide written notice to every owner, usually within a specific window defined in the governing documents. In Florida, the notice has to include the amount, the payment schedule, and information about any right to appeal or vote. If they screw this up, owners have grounds to challenge the assessment in court, and I've seen that strategy work more than once against boards that were cutting corners on procedure. Phase four — payment structures. This is where it gets personal. Most associations offer a few options: pay in full within sixty days, pay over twelve months with interest, or pay over twenty-four months with higher interest. The interest rates vary but typically run eight to twelve percent annually. I strongly recommend paying in full if you can. The math is straightforward — $30,000 over two years at ten percent interest costs you roughly $3,400 more. That's not theoretical. I ran the numbers for a client who chose the payment plan and then regretted it when she compared what she paid to what she would have paid upfront.
The Problem Nobody Warns About: Lien Sales and Tax Titles
If you don't pay, the association places a lien on your unit. That lien has priority over most other claims except property taxes. After a certain period — usually eighteen to twenty-four months depending on state law — the lien can be sold at a tax lien certificate sale or a tax deed sale. This is not a hypothetical risk. It happens constantly after major storms because everyone is hurting financially at the same time. In Florida, the process after Ian was particularly brutal. Thousands of owners couldn't pay because their homes were damaged, their jobs were disrupted, and their insurance claims were still disputed. The county tax collector's office started advertising lien certificates within months, and some owners lost their units without ever understanding what happened until they received a writ of possession. The workaround I used repeatedly was to negotiate a direct payment plan with the association before the lien even attached. Most boards would rather get a signed agreement than sit on a delinquent account. Get it in writing. Make sure the payment terms match what you can actually afford month to month. I've seen people sign plans for $800 a month only to default three payments later because they hadn't accounted for their own roof repairs or increased insurance premiums.
Where People Go Wrong
The biggest mistake I see is owners assuming their HOA fees cover everything. They don't. Regular assessments fund operations and routine reserves. Special assessments fund extraordinary expenses. The two are separate legal obligations, and confusing them won't help you when the billing department sends you to collections. The second mistake is not reading the governing documents before the assessment hits. If you'd looked at your declaration and bylaws three months earlier, you'd know whether the board needs a membership vote to levy an assessment above a certain threshold, whether there's a cap on special assessments, and what your appeal rights are. Most people don't read these documents. I get it. They're dense. But they're also the only thing standing between you and a surprise $60,000 bill. A third mistake is ignoring the assessment and hoping it goes away. It doesn't. The statute of limitations on HOA liens in Florida is seven years, and the lien accrues interest and penalties during that entire period. An assessment that starts at $25,000 can easily grow to over $40,000 before it's resolved, and the lien follows the property if you sell, meaning the closing title search will flag it and the buyer's lender will demand it be cleared before funding.
What You Should Do Right Now
If you're looking at a special assessment from Hurricane Ian damage and don't know where to start, here's the practical order of operations: Request a complete copy of the assessment resolution and supporting documents from the association's management company or board secretary. This should include the engineering report, the insurance claim summary, the reserve analysis, and the payment options. You're entitled to these records under Florida Statute 718.303 for condominiums and 720.303 for homeowners associations. Verify the insurance payout. Ask for the claim adjuster's report and the settlement statement. Cross-reference the approved repairs against what the engineering firm scoped. If there's a discrepancy — and there often is — document it. Disputes over reserve fund adequacy or unapproved repair line items have successfully reduced assessment amounts in court, though litigation costs are real and usually eat up most of any savings.
Check whether your state or county offered any storm recovery programs. Lee County and Collier County both had property tax relief options for Hurricane Ian survivors, and while those don't directly reduce HOA assessments, freeing up cash flow elsewhere makes paying the assessment easier. A property tax deferral program I helped someone access cut their annual obligation by roughly $1,200, which they redirected toward the assessment payment plan without touching their emergency fund. If the amount is substantial and you can't pay in full, negotiate before the payment deadline. Boards deal with delinquency every day and they'd rather have a realistic plan than a judgment they can't collect. Bring a proposed payment schedule that matches your actual income. If you're self-employed or your income is variable, be honest about it and propose a smaller base payment with a balloon at a known future date. Something is better than nothing, and the board knows it.
The Ugly Truth About Reserve Studies
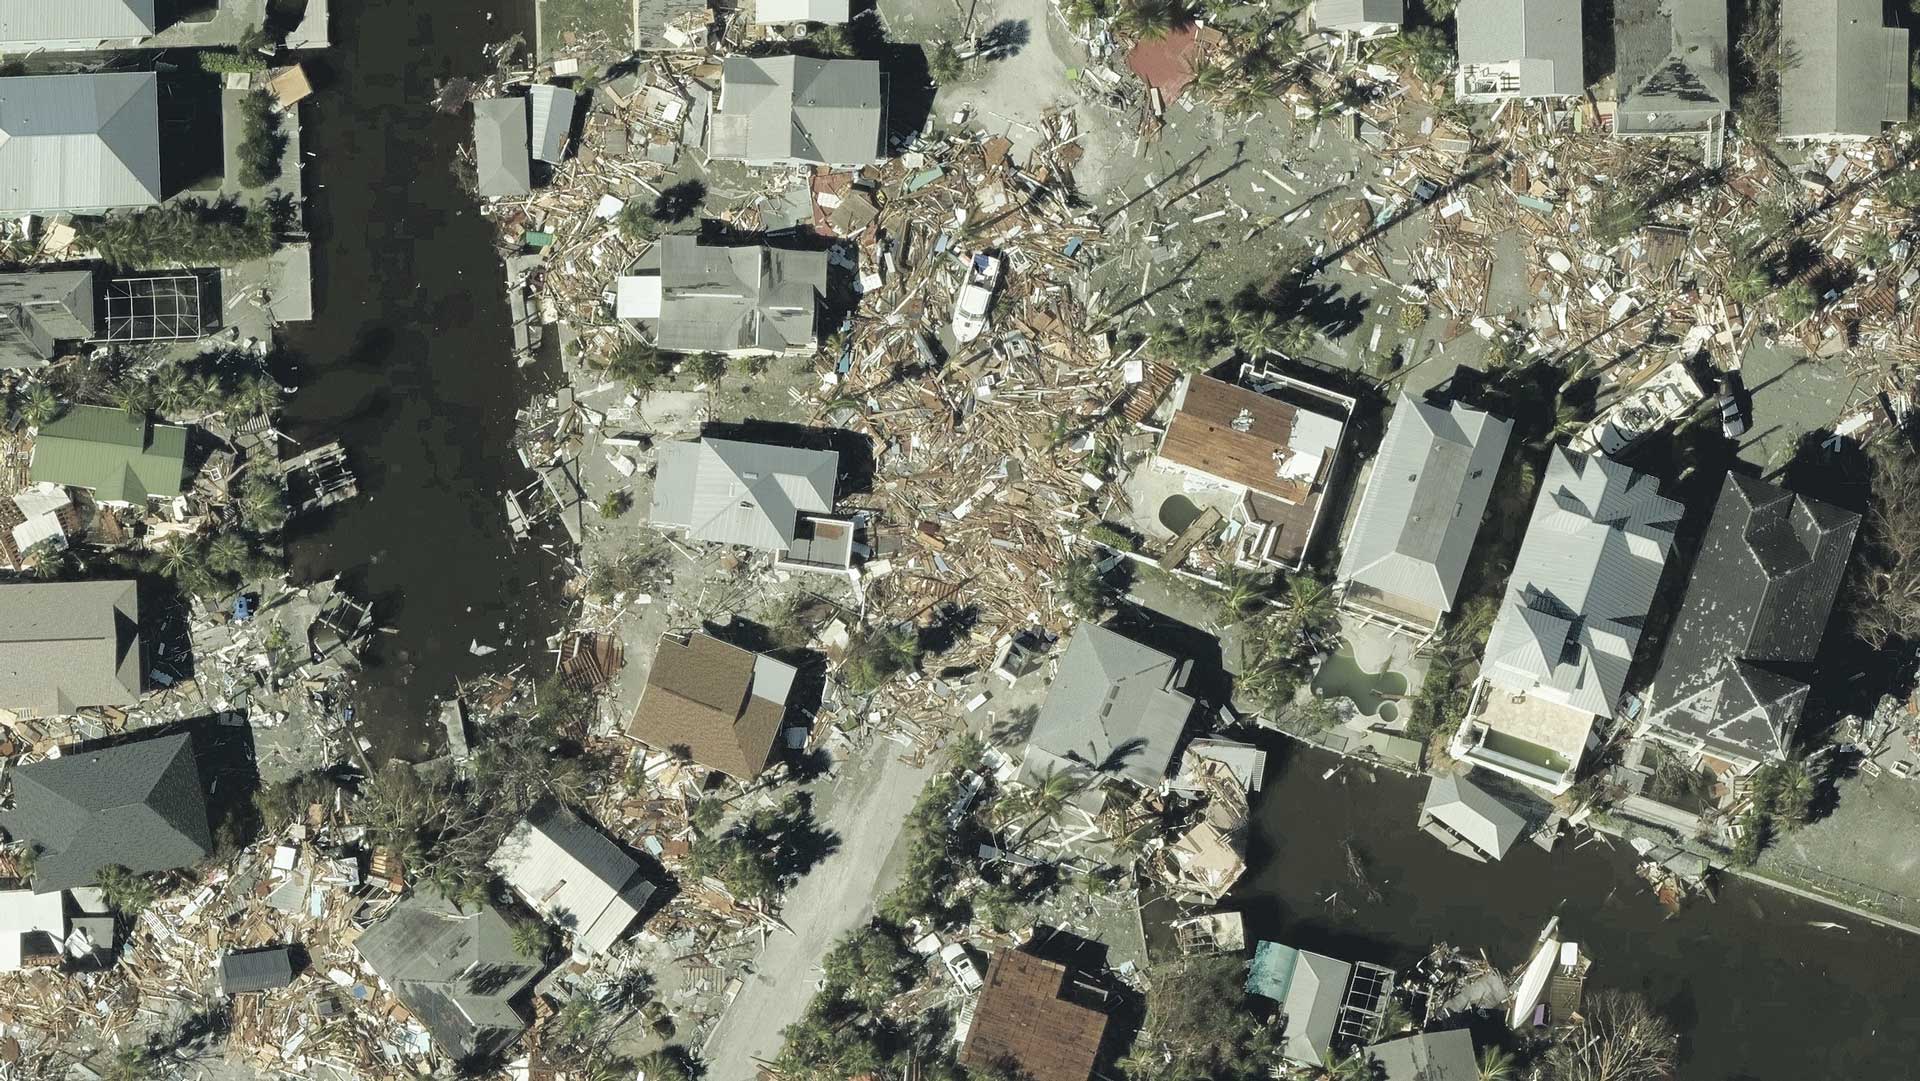
Most special assessments from hurricanes exist because reserve studies were inadequate. A proper reserve study looks at every major component of the property — roofs, paving, HVAC systems, elevators, plumbing — and calculates the replacement cost and remaining useful life of each one. It then determines how much the association should collect monthly to have enough money when replacement is due. After Ian, I reviewed reserve studies from approximately forty associations in the affected area. Fewer than half were current. Of those that were current, only about a third had adequate funding levels. The rest were running anywhere from twenty to sixty percent funded, which meant they collected about half of what they actually needed and then got blindsided when a Category 4 hurricane hit. This isn't an indictment of any specific company. Reserve studies are hard. They require professional judgment, site inspections, and ongoing updates. Many associations skip the inspection part entirely and use generic costing formulas from software, which produces numbers that look precise but are fundamentally wrong. I've seen a reserve study that valued a twenty-year-old roof at zero replacement cost because the software default assumed a thirty-year lifespan and the inspector never corrected it. That roof failed during Ian, and the resulting special assessment hit owners who'd been told their reserves were "adequate."
If you're currently dealing with an assessment and want to understand whether the underlying reserve study was negligent, you can request the most recent reserve study from the association. If it's outdated or clearly inaccurate, that's relevant context but probably not a legal defense against the assessment itself. Courts have generally held that inadequate reserves are the board's problem, not the owner's excuse for nonpayment. It's an uncomfortable reality, but it's the one that plays out in litigation.
A Specific Edge Case I Dealt With
One association I worked with had a special assessment that included a line item for "code upgrade compliance" costing $220,000. The board wanted to spread it across all owners equally. But the code violations stemmed from damage to only the southern wing of the building — twelve units out of sixty-four. The other fifty-two units had no code issues and were fully insured. The governing documents were silent on how to handle component-specific assessments. So I dug into Florida case law and found precedent supporting proportional allocation when a special assessment addresses a specific portion of the property rather than a common element. The board agreed to restructure the assessment so the southern wing owners absorbed the code upgrade costs while the rest of the association only paid for the shared structural repairs. It added about three weeks to the process but saved the unaffected owners roughly $8,000 each. Worth the delay. This kind of situation is rare but it happens. If your assessment feels unfairly distributed, don't just accept it. Review the governing documents, look at what the funds are actually being used for, and ask the board for a breakdown by component. Most will provide one if you ask politely and in writing.
Resources
The Florida Department of Business and Professional Regulation maintains a consumer guide on condominium and cooperative special assessments. It's not thrilling reading but it's accurate. The Florida HOA website also has state-specific articles on assessment procedures and owner rights. For legal questions that go beyond general information, consult a Florida-licensed attorney who specializes in community association law. General practice attorneys often don't know the nuances of FL Statutes 718 and 720, and relying on incorrect advice during an assessment dispute can cost you more than the assessment itself. If you need to download or reference official Florida statutory requirements around HOA assessments and reserve funding, the Florida Legislature's website publishes the current text of both Chapter 718 and Chapter 720 free of charge. The PDF versions are searchable, which helps when you're looking for a specific section about notice requirements or lien procedures. The bottom line is that a special assessment after a hurricane is stressful but manageable if you move deliberately. Read the documents. Verify the numbers. Negotiate the payment terms. Pay what you can. And don't let the embarrassment of not knowing what to do become the reason you ignore it until a lien attaches.