Understanding the SSVF Income Eligibility Threshold
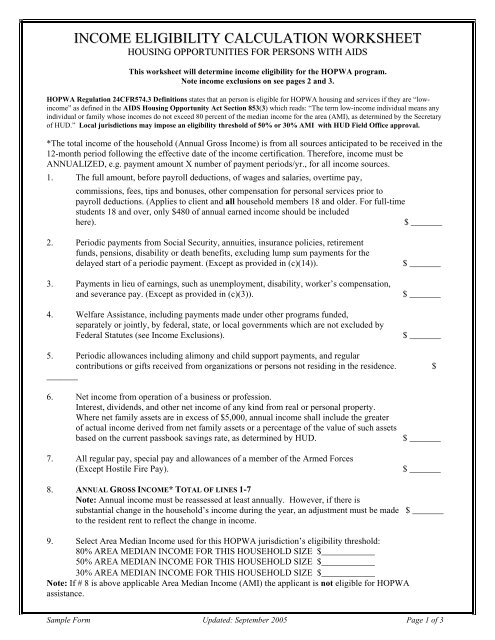
The VA uses the Federal Poverty Guidelines as the baseline for SSVF income eligibility. Right now, for a household of one, that threshold sits at $15,060 annually. For a family of four, it's $31,200. You add roughly $3,940 per additional household member. These numbers adjust every fiscal year. If you're working off old guidelines, you're already behind. Here's what most people get wrong on first pass. The income calculation isn't just about the veteran's paycheck. It's about the entire household. Spouses count. Dependents count. Anyone living in the home who contributes income gets folded in. The worksheet accounts for this by summing gross annual income from all sources before any deductions.
How to Use the Ssvf Income Eligibility Calculation Worksheet Correctly
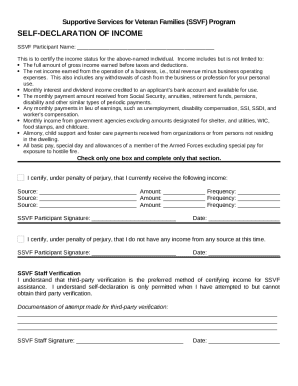
I've filled out dozens of these during intake screenings. The trick is catching the income sources that slip through. SSI, VA disability payments, child support, workers' comp, alimony, unemployment benefits — all of it counts. Even irregular income like seasonal work needs to be annualized. A client who makes $800 a month in summer and nothing the rest of the year still shows up as $9,600 annually on the worksheet. Don't let them round it down to zero because it's "off-season." One edge case that tripped me up for months: a veteran whose spouse receives Social Security Disability Insurance but doesn't file a tax return. SSDI is counted as income on the worksheet regardless of filing status. The client kept insisting it didn't count because they hadn't submitted paperwork to the VA for it. I had to pull the SSN and verify the benefit amount directly through the SSA to get it on the record. Once I did, it pushed the household income above the threshold. They didn't qualify that cycle. Worth noting — SSNA (Supplemental Security Income) counts the same way. The worksheet itself has a section for subtracting certain expenses, but the allowable deductions are narrow. Medical costs out of pocket don't count. Child care isn't deductible. What does go through is unpaid medical bills that are past due and likely uncollectible, and any court-ordered wage garnishments. Even then, you need documentation. An employer verification letter for garnishments. A statement from a medical provider for unpaid bills. Without paper, it doesn't exist on the worksheet.
There's a nuance most guides skip over. If the household income falls between 100% and 125% of the Federal Poverty Level, SSVF can still serve the veteran, but funding priorities shift. Agencies with capped beds often turn away households in that 100-125% band when demand exceeds capacity. The worksheet will flag it with a notation, but it won't auto-reject. That decision lives with the site director, not the form. Another thing that catches people: the income test uses gross income, not net. If someone's monthly take-home is $2,400 after taxes and deductions, you don't start there. You back into the gross figure. Multiply monthly by 12. If they're paid biweekly, multiply by 26. If their income fluctuates month to month, average the last six months. Don't use the most recent single paycheck unless the employment is ongoing and stable. A client showing $4,200 last month because they picked up overtime doesn't mean their annualized income is $50,400. Spread it across the year or the worksheet misrepresents them. Household size is where things get messy in practice. A veteran living alone with a minor child who visits every other weekend — is that a household of two or one? The answer depends on whether the child claims the veteran as a dependent on taxes. If yes, the child counts. If no, they generally don't, unless they receive more than half their support from the veteran. Read the instructions on the worksheet carefully. The definition of household member there is specific and it doesn't always match how people naturally think about family.
Get the Full Details
The biggest bottleneck I see in the field is timing. The Federal Poverty Guidelines drop in February each year. The worksheet is usually updated shortly after. Until then, you're running calculations on stale numbers. I've seen agencies get caught mid-cycle with outdated thresholds because the update came through after their training materials were printed. Always check the VA SSVF website for the current fiscal year's poverty line before finalizing an application. Using the wrong table is the fastest way to get a denial on technical grounds. There are scenarios where the worksheet simply doesn't work well. Self-employed veterans with irregular cash flow, or those who operate below the surface economy, are nearly impossible to assess accurately with this tool. The worksheet assumes reported income. When income isn't reported, you have to estimate from bank deposits or asset depletion patterns, and that introduces subjectivity. Some sites handle this with a secondary review process. Others just mark it as unverified income and move on. Neither approach is ideal. If the household income exceeds 125% of the Federal Poverty Level, the veteran doesn't meet SSVF eligibility under the standard income pathway. At that point, the worksheet doesn't offer an appeal mechanism. The only recourse is to look for alternative programs. HUD-VASH vouchers, state veterans homes, or local charity care networks may have different income caps. The worksheet is a gate, not a solution. Know what's on the other side of it before you invest time filling it out.
I've found that running the calculation twice helps. Once quickly to get a ballpark number, then again slowly with documentation pulled together. The first pass tells you whether you're in the right neighborhood. The second pass confirms whether the client actually qualifies. Skipping the verification step is how you end up with incomplete packets that come back from the regional office asking for pay stubs you should have collected upfront.