Getting variance analysis to actually mean something in a real factory
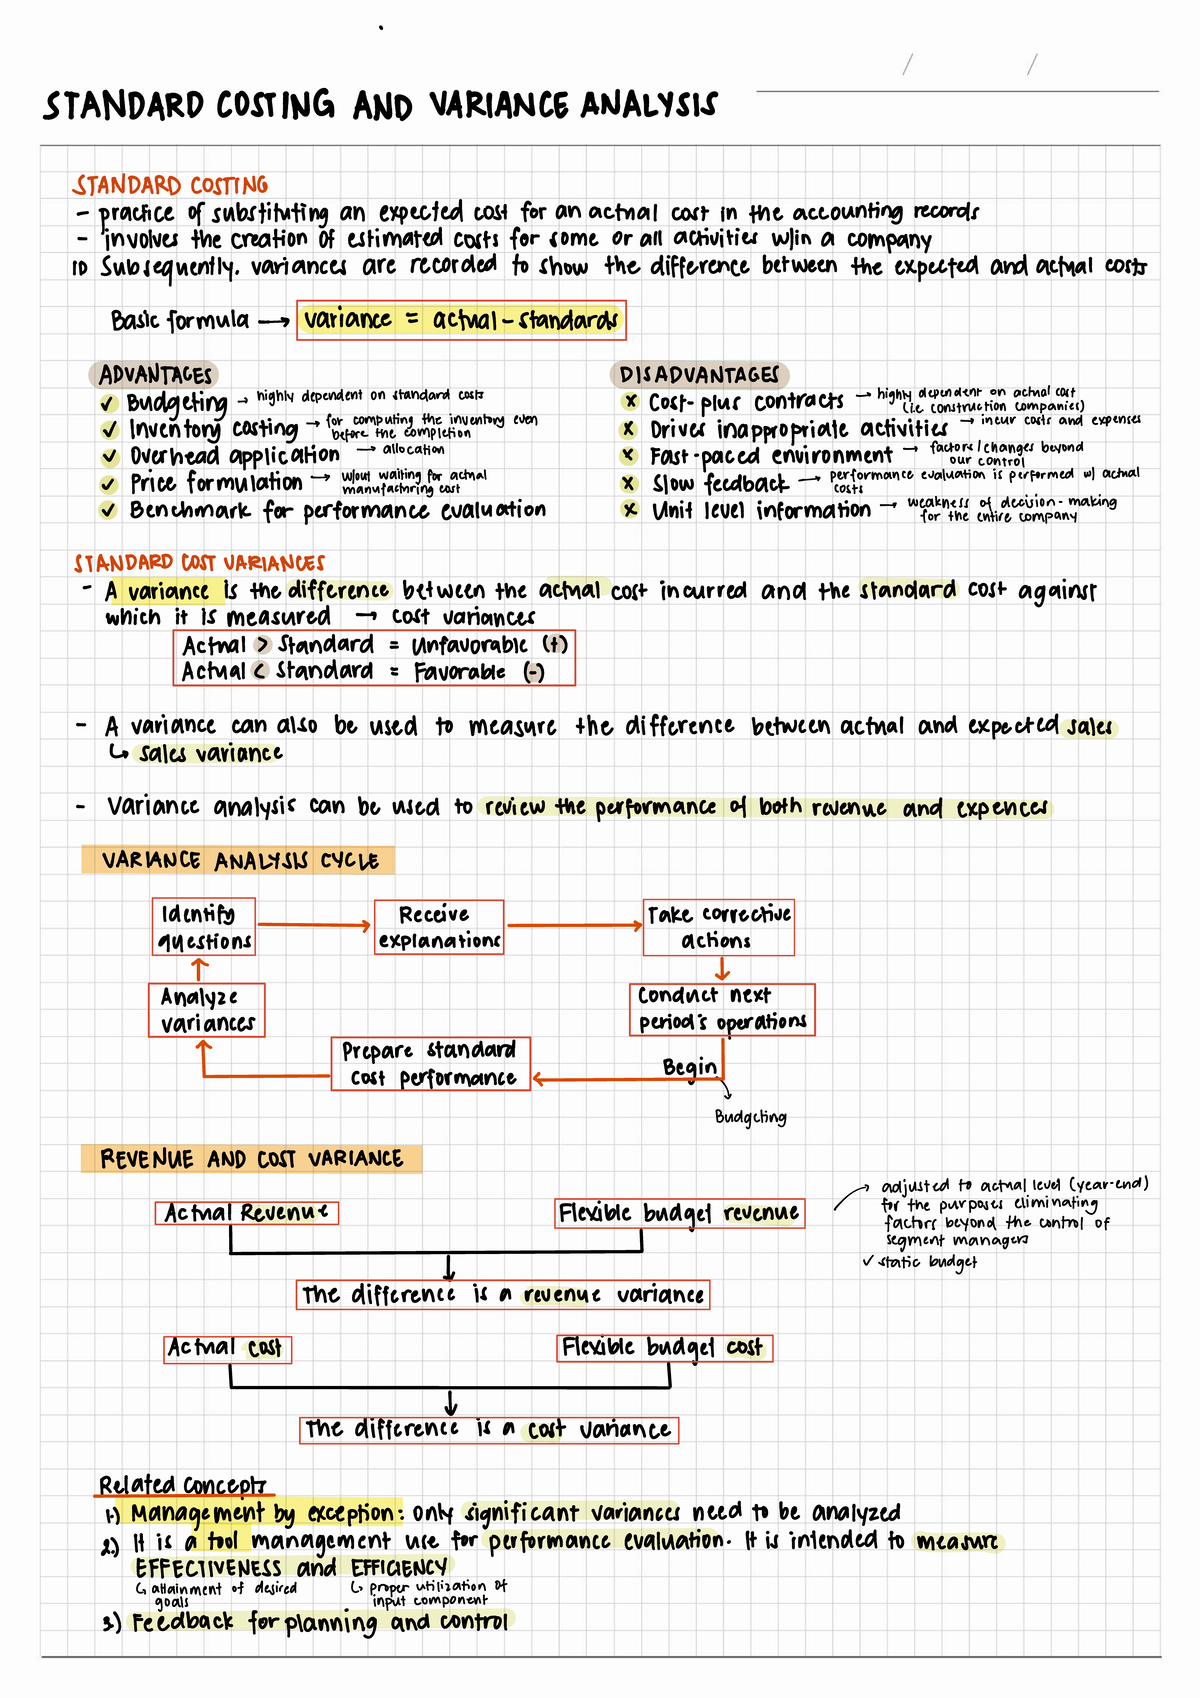
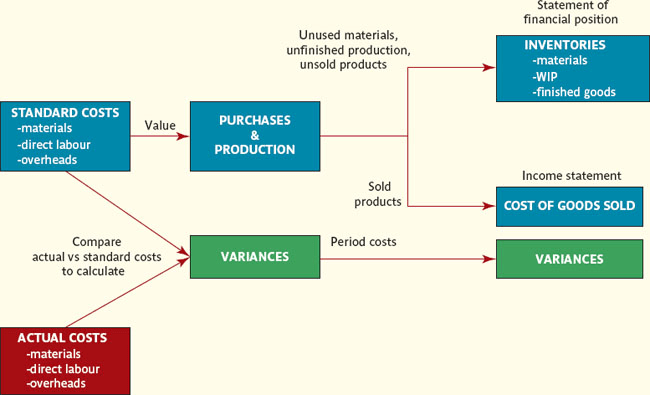
I used to spend three days every month chasing ghost variances that pointed at nothing productive. The numbers would look fine on paper but when I walked the floor, the problems were completely different from what the spreadsheet was telling me. That happened because I wasn't looking at the right variances or interpreting them correctly. Most people set up standard cost and variance analysis the wrong way from the start. The basic mechanism is straightforward enough. You set a standard cost for materials, labor, and overhead before the period begins. At the end of the period, you compare actual costs against those standards. The difference is your variance. A favorable variance means you spent less than expected. An unfavorable one means you spent more. That is the textbook version. The actual practice involves a lot more judgment calls.
Understanding the components of Standard Cost And Variance Analysis
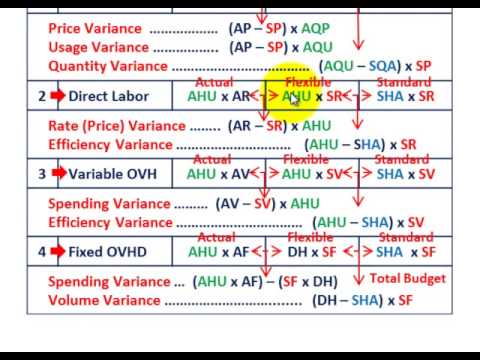
You need to break it down into specific variance types. Material price variance captures the difference between what you expected to pay per unit of raw material and what you actually paid. Material usage variance tracks whether you consumed more or less material than the standard allowed for the output you produced. Labor rate variance measures the difference between standard and actual hourly wages. Labor efficiency variance measures whether workers took more or fewer hours than the standard allowed. Overhead variances split into spending, efficiency, and volume components that get messy fast. I remember pulling my hair out over a recurring labor efficiency variance that showed up every single month on a specific product line. The variance was consistently unfavorable by about eight percent. I blamed the workers initially. Then I noticed the standard was based on a machine cycle time that assumed no setup changes between runs. The shop floor was doing frequent small batch changes. The standard was technically accurate for continuous production but completely wrong for how they actually operated. I reworked the standard to include setup time as a separate variance category and the labor efficiency numbers stabilized immediately. That taught me that variances are often telling you about flawed standards, not poor performance. One thing beginners consistently miss is the interaction between variances. They treat each one independently when that approach can be deeply misleading. If you buy cheaper materials and get a favorable price variance, you will almost certainly see an unfavorable usage variance because those materials are harder to work with or produce more scrap. The net effect might be worse than if you bought the proper material at the higher price. I have seen managers reward purchasing for a material price variance that ended up costing the company twice as much in waste and rework. The variance report alone would not have shown that damage.
Another counter-intuitive point is that favorable variances are not always good. A large favorable material usage variance could mean your standard allows too much waste as normal, so workers are coasting below expectations. Or it could mean they are cutting corners on quality. I once traced a favorable labor efficiency variance back to operators skipping a mandatory inspection step. The output looked fine until three months later when a customer return spike revealed the defect rate had quietly doubled. The variance was favorable but the business was losing money. The practical setup process starts with establishing realistic standards. Most companies pull these from engineering specs or historical averages without testing them against current conditions. Your material standards should reflect the actual grade and supplier you are using, not the ideal grade from a catalog. Labor standards need to account for real break times, changeovers, and the skill level of your current workforce, not the average of the last five years when things were different. Overhead application rates require a careful choice of allocation base. Machine hours, direct labor hours, and units produced will give you very different variance patterns depending on your cost structure. When you calculate variances, decide whether to use actual output or budgeted output as the denominator for flexible budget adjustments. Using budgeted output locks in volume variance differently than using actual output. I found that using actual output for material and labor variances but budgeted output for fixed overhead volume variance gave me the most actionable information. The math changes slightly and you need to be consistent about which method you choose.
Get the Full Details

Here is the blunt part that nobody puts in the textbooks. Standard cost and variance analysis breaks down in several common scenarios. If your product mix changes significantly during the period, the standard costs become comparably unreliable and your variances will fluctuate for reasons that have nothing to do with operational performance. Companies doing high-mix low-volume custom work often find that standard costing adds administrative overhead without delivering useful signals. The variance numbers become so noisy from constant standard revisions that managers stop reading the reports. In those cases, throughput accounting or activity-based costing gives clearer answers. Another limitation is that standard costing tends to encourage overproduction. Since fixed overhead is applied based on production volume, producing more units absorbs more overhead into inventory and makes the variance report look better in the short term. I have watched production managers push through extra units right before month end just to minimize their overhead volume variance. The finished goods warehouse got fuller and the cash flow got worse, but the variance report was green across the board. That behavior is baked into the method itself. For implementation, keep the number of variance categories manageable. I usually recommend focusing on the top five or six variances that drive the most dollar impact rather than computing every possible variance type. Most of the standard variances in a full system generate noise, not signal. Update your standards at least annually, but do it after reviewing whether existing standards still reflect current technology, material quality, and process capability. An outdated standard produces meaningless variances that blame people for problems they cannot control.
If you need to build this from scratch, start with a simple spreadsheet model tracking material price and usage variances plus labor rate and efficiency variances for your top three products by revenue. Get comfortable interpreting the interactions before adding overhead variances and second-order metrics. The framework scales up fine once you understand what each number is actually trying to tell you.