How startup funding without personal capital actually works
Most people looking for startup business loans with no money down are coming from a place of exhaustion. They've been turned down by traditional banks, they've maxed out credit cards, and they're told repeatedly that they need collateral or a strong credit history. The reality is more complicated than the marketing pages suggest. The phrase gets thrown around loosely. What you're really looking at are several distinct funding mechanisms that occasionally overlap. SBA loans designed for startups can qualify with zero down if you meet specific criteria. Revenue-based financing doesn't require collateral but it demands consistent monthly revenue. Merchant cash advances work without down payment but the effective APR is brutal. Grant programs exist but the acceptance rate hovers around two to four percent for most applicants. I spent three years managing small business lending portfolios before moving to the advisory side. One of the first things I learned is that the loan product itself matters less than how you present the business case. A weak proposal submitted to a lenient lender will fail faster than a strong proposal submitted to a strict one.
The mechanics behind zero-down approval
Lenders who offer no money down financing are taking on more risk. They compensate for that risk through higher interest rates, shorter terms, or personal guarantees. The key is understanding which trade-off you can actually absorb. A business owner I worked with had her startup approved for $75,000 with zero down through an SBA 7(a) program. The deal looked solid on paper. The problem was that she hadn't factored in the 3.675 percent guarantee fee, which came due at closing and reduced her net proceeds to roughly $72,000. She needed the full amount to cover equipment purchases and had to pull an additional $3,000 from personal savings at the last minute. The workaround was straightforward once I saw it. I had her request the loan disbursement split into two tranches tied to specific milestones. The first tranche covered the equipment. The second covered the operating expenses. This changed the lender's risk calculation and allowed them to roll the guarantee fee into the principal balance rather than demanding it upfront. Net result was the same capital, just structured differently.
What lenders actually evaluate
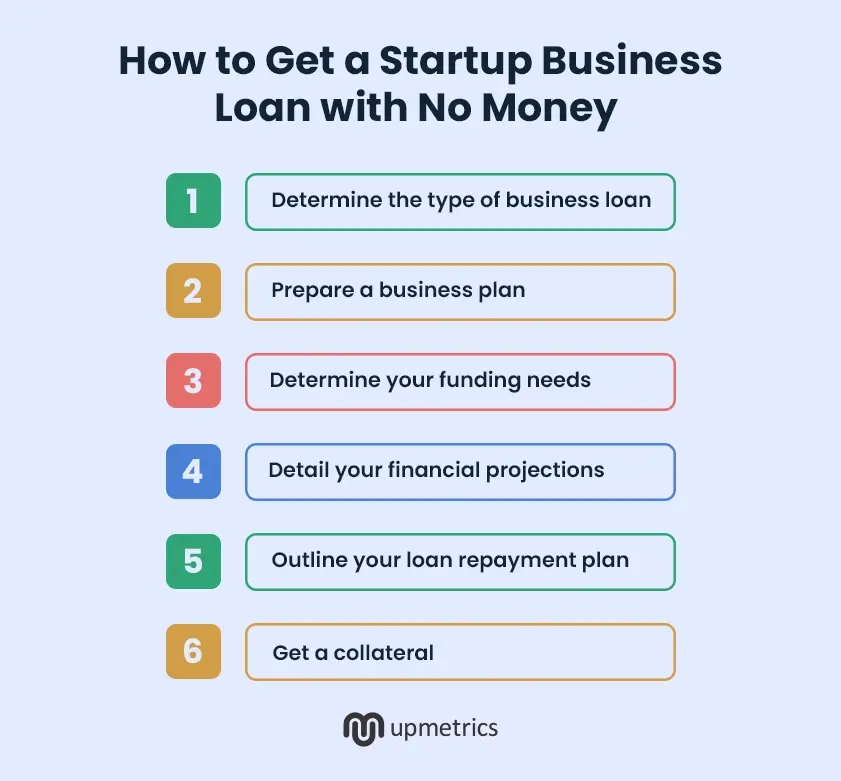
Your credit score matters but it's not the decisive factor for startup loans without down payment. Lenders look at your debt service coverage ratio even if you don't have historical revenue. They use projected cash flow models. They want to see that you can service the debt from expected income within the first twelve months of operation. Your personal credit history demonstrates how you handle financial obligations. A score in the high sixties or above opens most doors. Below that, you're looking at alternative lenders with considerably worse terms. Here's something most people miss. Lenders are more interested in your industry experience than your business plan. A founder with five years in restaurant management has a significantly easier path to zero-down financing than a first-time founder with a detailed business plan and no relevant background. The experience signals to the lender that you understand the operational risks involved.
Get the Full Details

Common pitfalls that kill your application
Applicants routinely underestimate the documentation requirements. A typical SBA zero-down application requires a complete personal financial statement, three years of personal tax returns, a detailed business plan with projections, and industry-specific market research. If you're missing any of these, the application stalls immediately. Most lenders will not accept partial submissions. Another frequent mistake is assuming that no money down means no personal involvement. Almost every zero-down startup loan requires a personal guarantee. That means if the business defaults, you are personally liable for the full amount. This is not a loophole. It is the standard structure and it exists because lenders need to align your incentives with the business's success. The biggest trap I see is overborrowing. Just because you qualify for $100,000 with zero down doesn't mean you should take it all at once. Each dollar you borrow increases your monthly payment obligation and reduces your runway. I recommend taking only what you need for the first six to eight months of operations and returning to the lender for a second draw when you have demonstrated traction.
Where to look beyond traditional banks
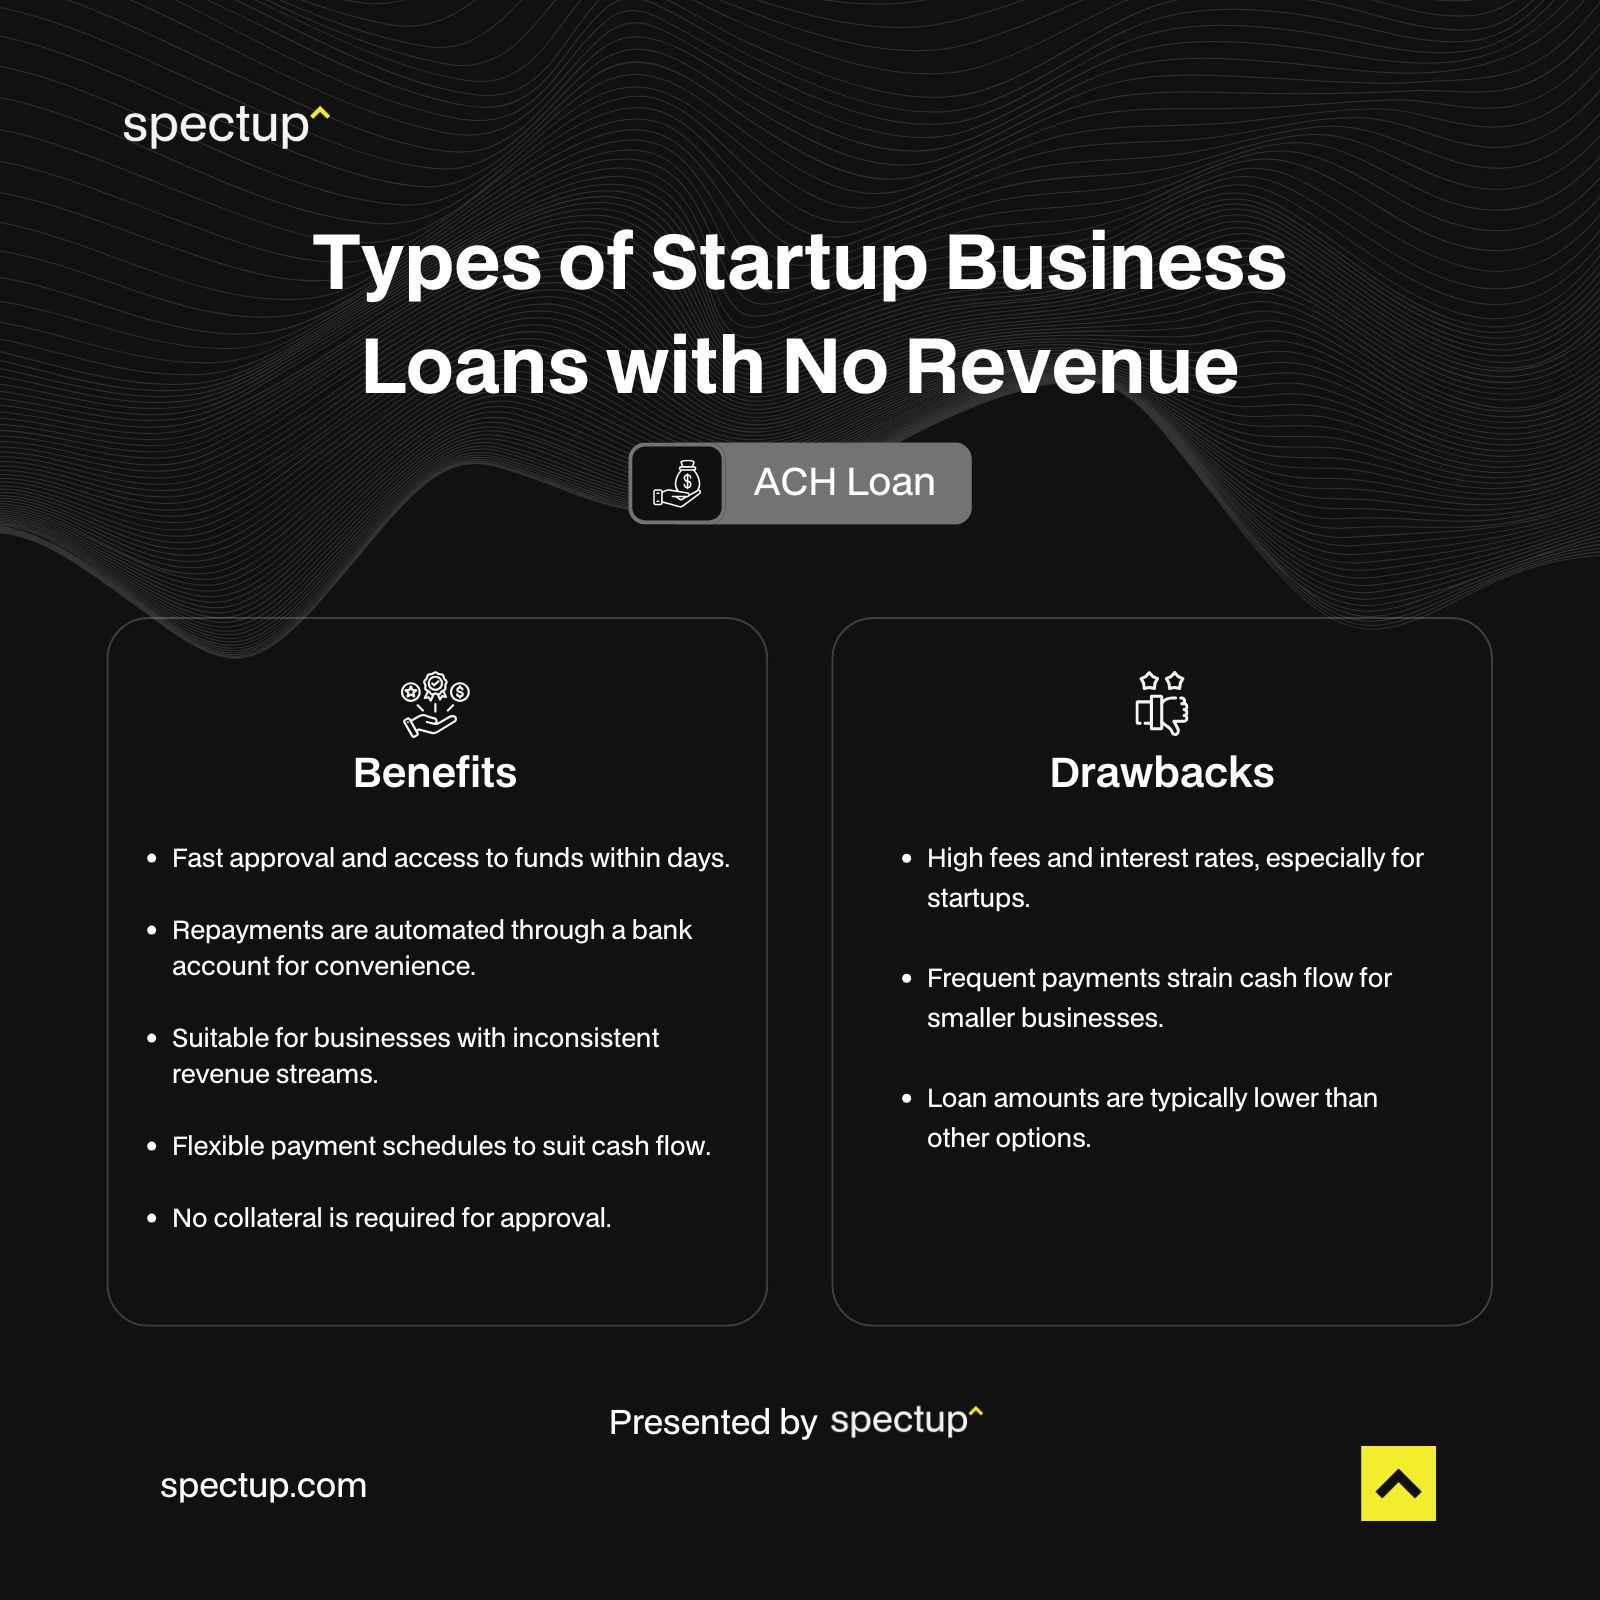
Community development financial institutions operate under different guidelines than national banks. They are mission-driven and often accept weaker credit profiles in exchange for stronger community impact narratives. Online lenders like Bluevine, OnDeck, and Funding Circle offer startup-friendly products though their rates are typically forty to eighty percent APR. Micro-lenders through networks like ACCION or Kiva provide smaller amounts, usually between five thousand and fifty thousand dollars, with more forgiving terms. Local economic development organizations sometimes maintain revolving loan funds specifically for startup businesses. These programs often have income caps and target specific demographics or geographic areas. A quick search through your state's SBA district office website will surface most of these options. The application process is slower than online lenders but the terms are considerably better.
The hard truth about no money down
Zero-down startup financing is accessible but it is not free money. The interest rates run higher. The personal liability is real. The approval standards are selective even when down payment is removed from the equation. If you have any savings to contribute, even a ten percent down payment dramatically improves your terms and broadens your lender options. A twenty-five percent down payment can drop your rate by two to three percentage points and reduce the lender's requirement for a personal guarantee on some products. The best outcome for most founders is a hybrid approach. Secure a modest zero-down loan for immediate operating needs. Supplement it with a smaller secured loan using whatever personal assets you have available. This two-track strategy reduces your total borrowing cost while keeping you afloat during the critical early months.