Why the Indirect Method Still Dominates Public Company Reporting
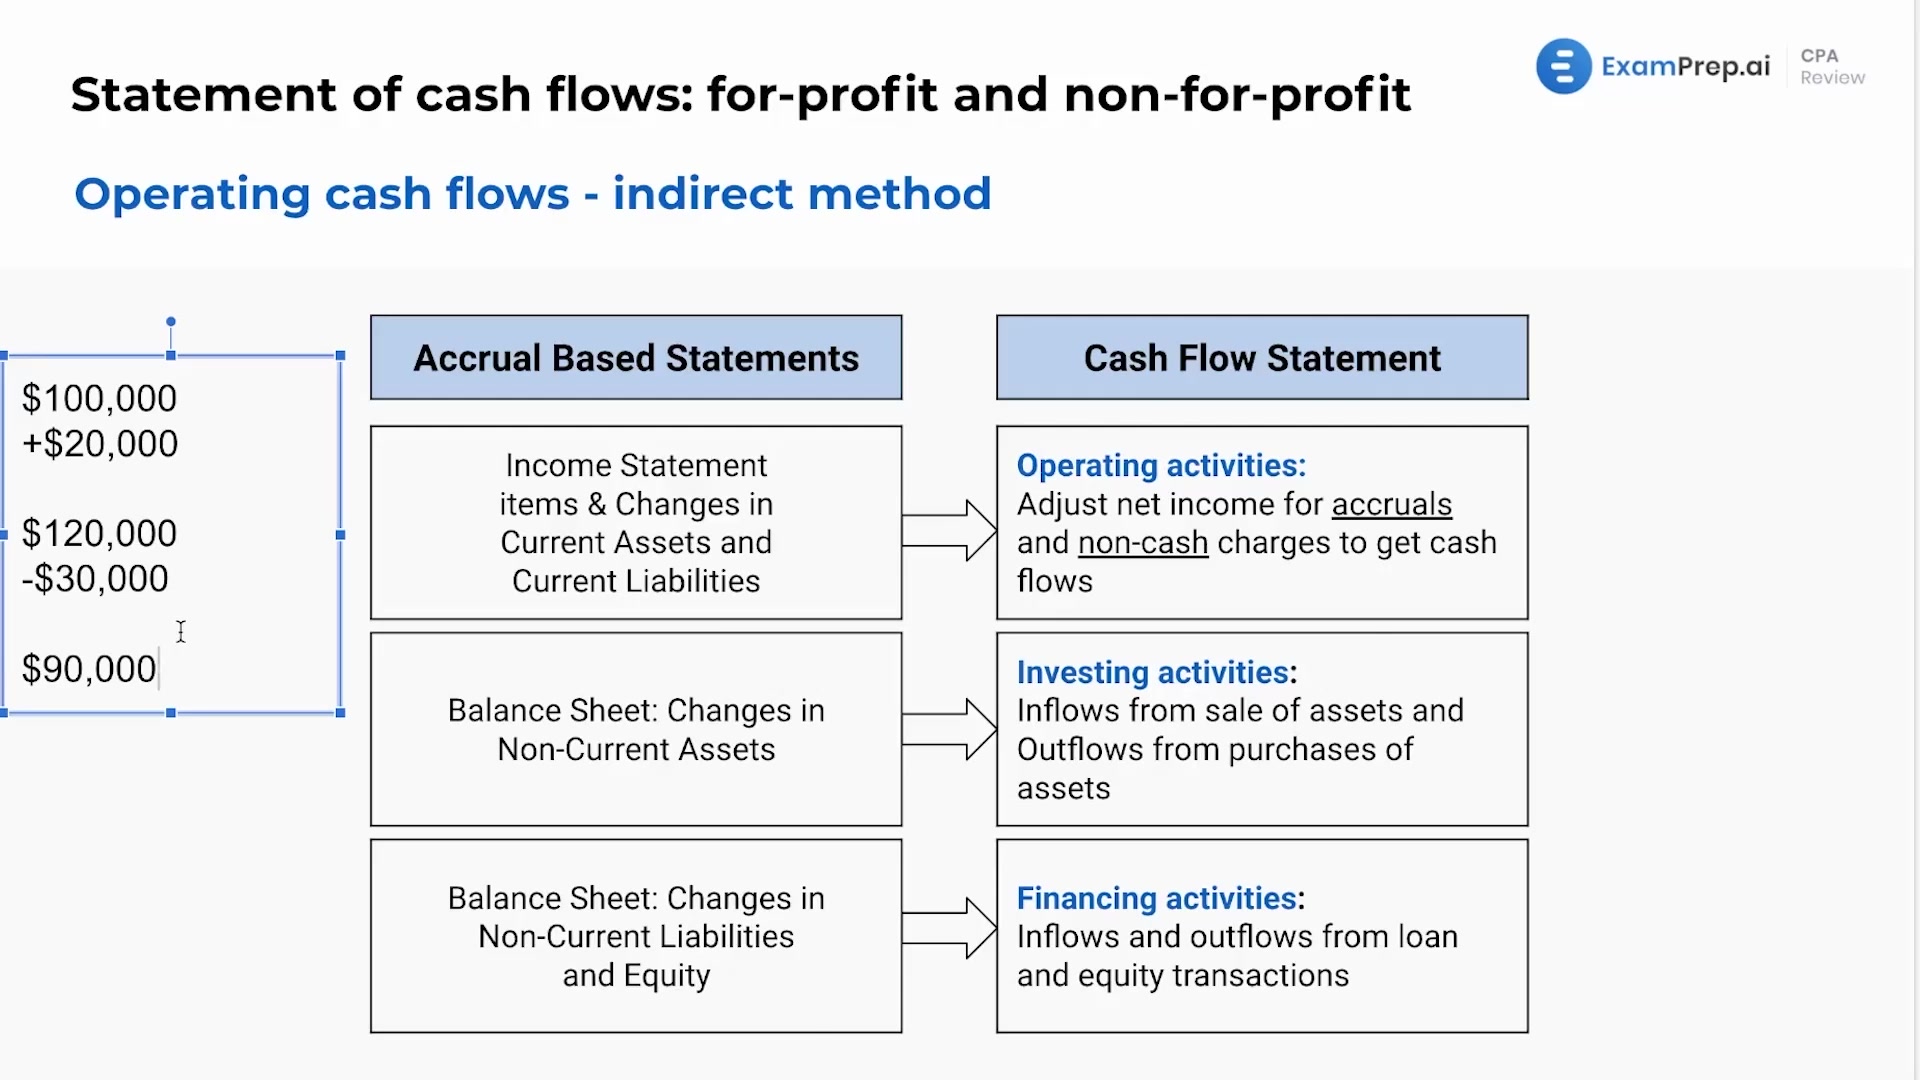
The indirect method for cash flows starts with net income and walks backward through the balance sheet to reconcile it to actual cash moved. Most companies use it because it is simpler when you already have your balance sheet adjustments pulled from the general ledger. The direct method requires tracing every single cash receipt and disbursement, which is a massive undertaking if your chart of accounts isn't cleanly mapped to operating, investing, and financing buckets from day one. I spent several years building cash flow statements from scratch for mid-market companies, and the indirect method has always been the faster path to a defensible deliverable. It is not the most intuitive method for someone learning accounting for the first time, but it is the one auditors expect to see and the one investors are used to reading. You will find it in 90 percent of public company SEC filings.
Understanding the Statement Of Cash Flows Indirect Method Example
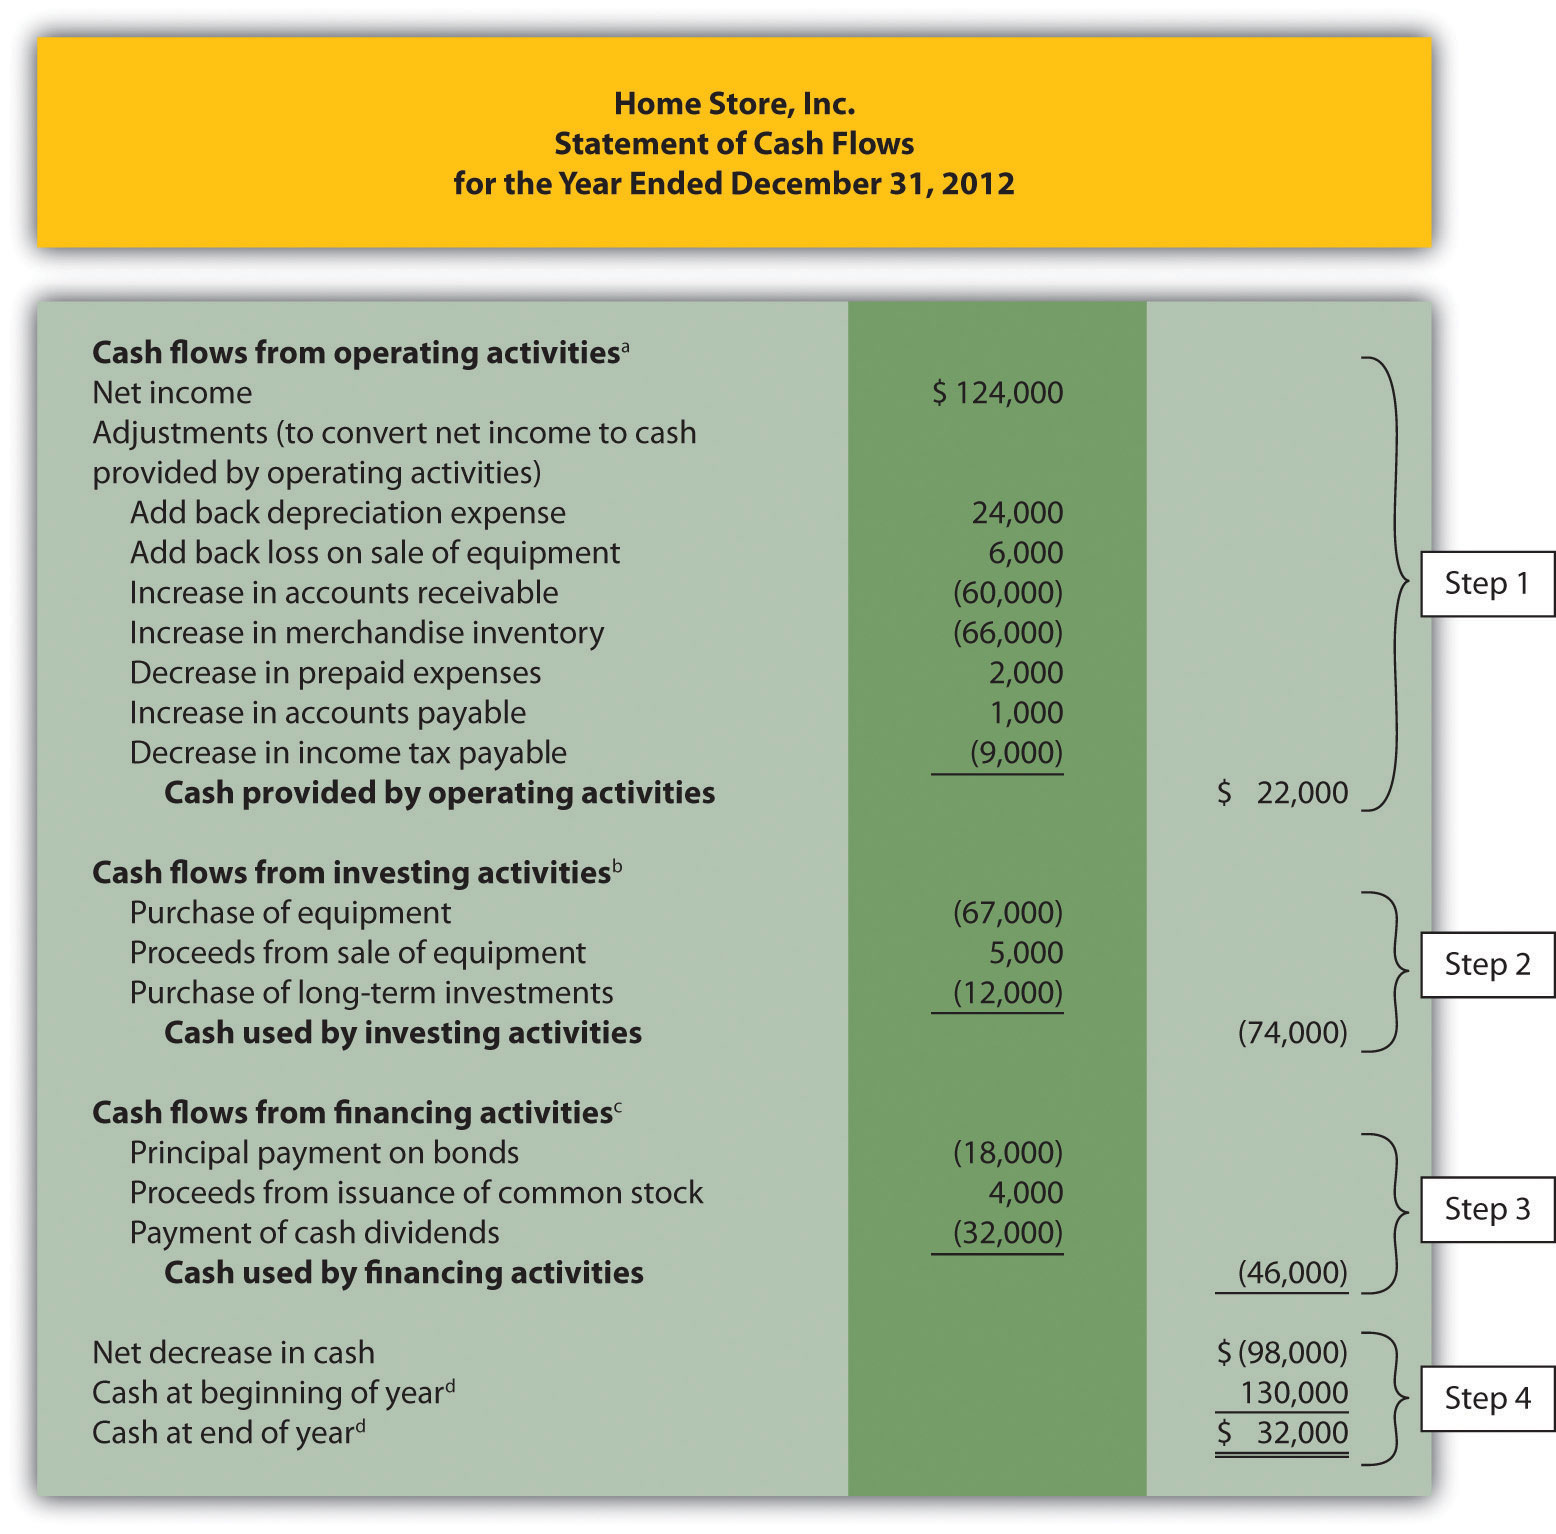
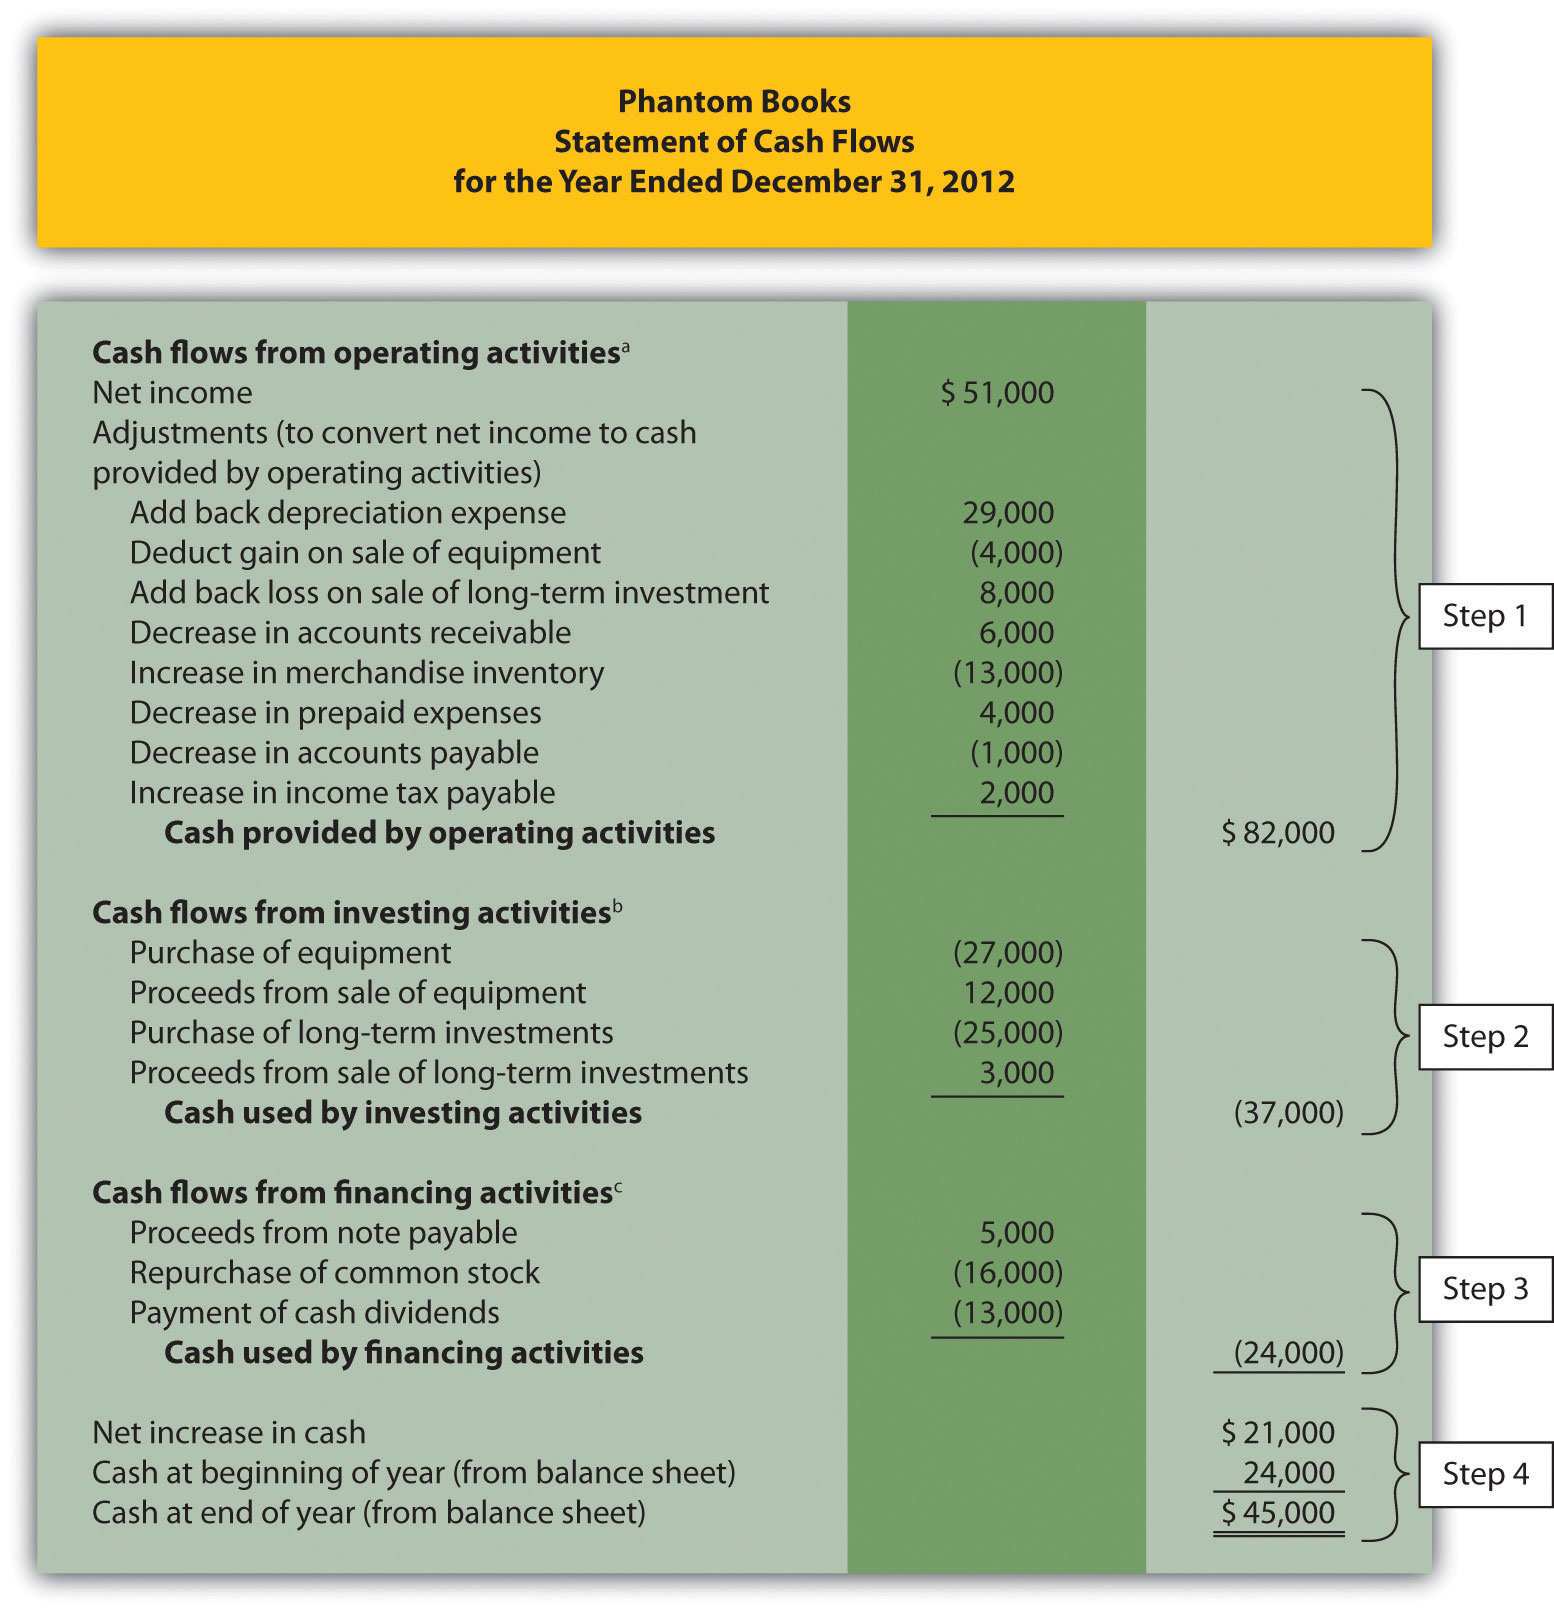
Here is how the mechanics actually work in practice. You begin with net income from the income statement. Then you add back non-cash expenses like depreciation and amortization because those reduced net income even though no cash left the building. Next you adjust for changes in working capital accounts — increases in accounts receivable subtract from cash, increases in inventory subtract from cash, and increases in accounts payable add to cash. The logic is straightforward once you internalize it, but the order of operations matters when you are building this in a spreadsheet under deadline pressure. Let me walk through a concrete scenario. Company A reports net income of $150,000 for the year. Depreciation expense was $35,000. Accounts receivable increased by $20,000. Inventory decreased by $8,000. Accounts payable increased by $12,000. Here is the reconciliation: Net income: $150,000
Plus depreciation: $35,000 Less increase in accounts receivable: ($20,000) Plus decrease in inventory: $8,000
Get the Full Details
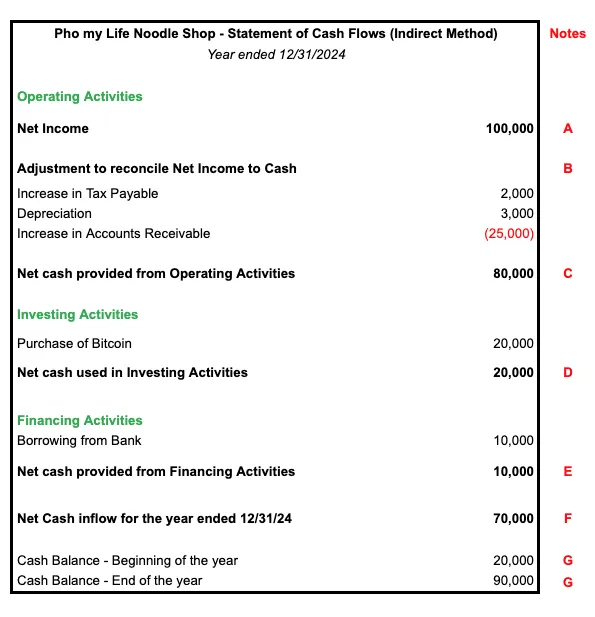
Plus increase in accounts payable: $12,000 Cash from operations: $185,000 The investing and financing sections are separate. Any purchase or sale of fixed assets goes into investing. Any debt issuance, debt repayment, stock repurchase, or dividend payment goes into financing. The net change across all three sections should match the change in cash on your balance sheet. If it does not, you have an error somewhere and the auditor will find it before you do.
One thing most people miss is that the indirect method conceals the actual cash inflows and outflows. Net cash from operations comes out as a single number. You cannot tell from the statement alone whether revenue came in mostly from cash sales or credit sales that are still outstanding. That is the primary criticism of this approach, and it is legitimate. If your stakeholders need transparency into the composition of cash receipts, the direct method is technically superior even though it is far more tedious to prepare. I encountered a specific edge case once involving a company with significant lease obligations under ASC 842. The right-of-use asset depreciation and the interest component of lease payments both create adjustments that look similar on the face of the cash flow statement but have different implications. The depreciation portion is a standard add-back. The interest portion is already embedded in net income through the income statement, but the principal repayment on the lease liability is a financing cash outflow that does not appear in the operating section at all. I spent about three hours reworking the schedule because the initial draft had classified the entire lease payment as an operating adjustment, which overstated operating cash flow and understated financing cash outflows. The workaround was to pull the lease amortization schedule directly from the subsidiary ledger and separate the interest and principal components before applying any adjustments. That should take you about 20 minutes if your lease data is organized properly, but it will take significantly longer if you are reconstructing it from a mess of journal entries. Another counter-intuitive point that trips up people regularly involves stock-based compensation. When a company grants restricted stock units or options, the expense hits net income but involves zero cash. The add-back is correct, but you also need to consider whether the exercise of those options generates actual cash proceeds that belong in the financing section. I have seen cash flow statements where the SBC add-back was correct but the proceeds from option exercises were accidentally buried in operating activities because the accountant treated them as a reduction of the SBC adjustment rather than a distinct financing inflow. That misclassification does not change total cash, but it materially distorts operating cash flow, which is the line item analysts care about most.
The indirect method also struggles with certain items that sit between operating and investing. Gains and losses on asset sales require you to remove the gain or loss from net income and then report the full proceeds in investing. If you forget to remove the gain, you are double-counting. A $50,000 gain on equipment sold means you subtract $50,000 from net income in the operating section and then add the full sale proceeds to investing. Missing either half of that adjustment throws off both sections and your total cash reconciliation. For a downloadable template, most accounting departments maintain an internal workbook that maps directly to their general ledger trial balance. The structure is simple: net income at the top, then a section for non-cash adjustments, then a section for working capital changes, then investing, then financing. I recommend building yours with clear reference columns that link each line item back to the specific GL account number. When you are preparing this quarterly and your team rotates, that traceability saves hours of reconciliation work. A blank template without account references is fine for learning, but it is not production-ready. The biggest bottleneck I see in practice is timing. Companies often wait until the balance sheet is finalized before starting the cash flow statement, but the working capital adjustments depend on comparing beginning and ending balances. If you are closing the books simultaneously across multiple entities with different fiscal month-ends, the comparison dates can drift and create reconciliation headaches. Start the cash flow schedule as soon as you have the prior period balance sheet in hand, even if the current period is not fully closed. You can update the numbers as they come in. This usually cuts the process down from two days of frantic end-of-period work to about three hours of maintenance throughout the close cycle.
There are legitimate scenarios where the indirect method fails to give you useful information. If a company has highly volatile working capital — say a seasonal business with massive inventory buildup and liquidation cycles — the operating cash flow number becomes noisy and difficult to trend. In those cases, supplementing the indirect method statement with a direct-method schedule for internal management reporting is reasonable. The SEC filing still uses indirect, but your operational decision-making benefits from seeing gross cash receipts and payments broken out by category. Another limitation is that the indirect method does not naturally accommodate companies with complex foreign currency operations. Translation adjustments flow through other comprehensive income and create adjustments that do not map cleanly to any single line item. You need a separate calculation to determine the cash impact of hedging activities versus pure translation effects. I have seen junior accountants lump the entire translation adjustment into the operating section add-backs, which is technically incorrect and creates a material misstatement if the hedge accounting is not segregated properly. The takeaway is that the indirect method is the practical default for external reporting, but it requires disciplined understanding of what each adjustment represents. The mechanics are simple. The application is where mistakes accumulate. Getting comfortable with the reconciliation logic and building a repeatable template with clear account mappings will serve you far better than memorizing the formula.