Working With State Securities Registration Under the Federal Framework
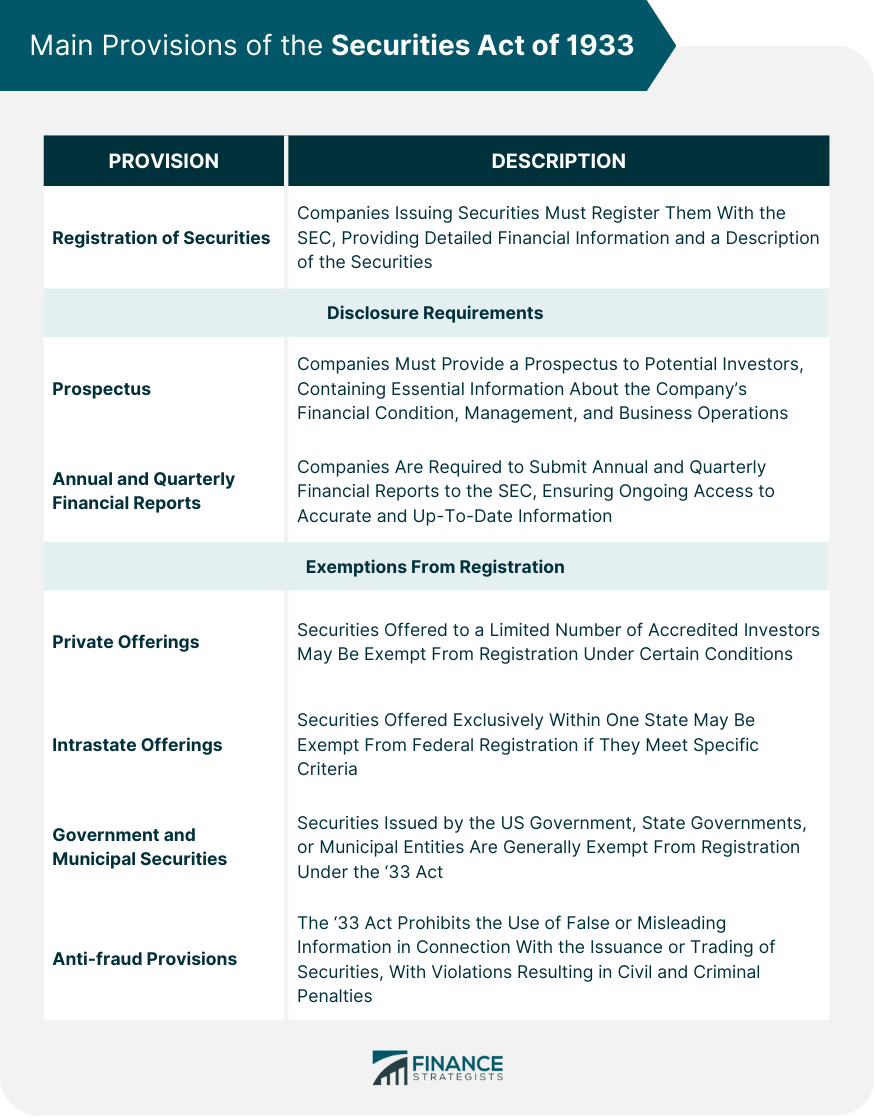
The federal Securities Act of 1933 handles the big registration picture, but every state has its own parallel requirements that you cannot ignore. Many people new to this area treat state filings as an afterthought, then get surprised when a single missed jurisdiction turns a clean offering into a compliance nightmare. The truth is that state-level registration under what people often call the States Securities Act Of 1933 framework operates as its own distinct system, and it demands the same careful attention as the federal side. Each state maintains its own securities division or equivalent regulatory body. These divisions enforce blue sky laws, which predate the federal act by decades in many cases. When you register a security federally under the 1933 Act, that does not automatically cover state requirements. You still need to satisfy each state where you plan to sell. The mechanics vary from state to state, and some states have adopted versions of the Uniform Securities Act while others have built their own distinct rules. I spent years dealing with these filings across multiple jurisdictions, and one thing becomes clear quickly: the federal form does not translate directly into state forms. The SEC form is standardized. State forms are not. Even states that claim to follow the Uniform Securities Act have carved out their own exceptions, additional disclosure requirements, and different fee structures.
How the Coordination Process Actually Works
Coordination is the standard mechanism that links your federal registration to state filings. Under Section 18 of the Uniform Securities Act, which most states have adopted in some form, a state registration can be coordinated with a parallel federal registration. The effect is that your state filing becomes effective on the same date your federal registration becomes effective, provided you file the required state documents within the window the law allows. Here is where most people trip up. The coordination period is measured against when your federal registration statement becomes effective, not when you file it. If your federal effective date shifts because of an amendment or a supplement, your state coordination clock resets. I had a client once who assumed a late-filed Form S-3 amendment would not affect his state timelines. It did. He lost his original coordination date and had to refile in three states before he could proceed. That added roughly two weeks and about $18,000 in legal fees that could have been avoided with a simple calendar check. The practical workaround is straightforward: track every federal filing date and effective date, and maintain a state-by-state spreadsheet that shows coordination deadlines, required exhibits, and fee amounts. Most securities attorneys use a matrix like this already, but if you are handling this yourself or working with a small firm, do it anyway. The spreadsheet pays for itself the first time a filing date moves.
Notice Filings and Exemptions You Should Know About
Not every offering requires full state qualification. Notice filings exist for certain categories of securities, including nationally traded stocks and securities issued by well-known seasoned issuers. The rules differ by state, and the list of eligible securities changes periodically. Some states have narrowed their notice filing provisions over the years, while others have expanded them. One thing that is easy to miss: the federal exemption under Section 3(a)(2) for bank securities does not automatically carry over to state notice filing eligibility. A few states still require full qualification for certain bank-issued securities even when the federal exemption applies. I learned this the hard way when advising on a credit union bond offering. The federal side was clean. Texas and Florida both required full qualification, and the state counsel had not caught the divergence because the exemption language looked identical on paper. Rule 147 and its federal counterpart Rule 144A provide intrastate and private resale exemptions, but those exemptions do not guarantee state-level protection either. Several states have rejected Rule 147's territorial approach outright or imposed additional residency requirements on the issuer's officers and directors. If you are relying on an intrastate exemption, verify the specific state rules before you structure the offering.
Get the Full Details

Fees, Turnaround Times, and What to Expect
State filing fees are calculated differently than federal fees. The SEC charges based on the aggregate offering price with set brackets. States vary: some charge a flat fee per jurisdiction, some use a percentage of the offering amount, and some combine both approaches. The total cost for a multi-state offering can range from a few thousand dollars to well over $50,000 depending on the number of states and the offering size. Turnaround times are another variable that gets overlooked. The SEC has statutory review periods for federal registrations. Most states do not have fixed review periods, though a handful do. In states without a set timeline, you are at the mercy of the securities division's workload. I have seen the same type of filing take 12 days in one state and 90 days in another, sometimes for nearly identical prospectus content. The difference usually comes down to whether the state examiner is familiar with the industry and the specific exemption being claimed. A useful strategy is to file in your most time-sensitive states first, then batch the rest. If you submit all 50 states at once, you will burn review capacity across the board. Filing strategically lets you lock in effective dates for the critical markets while the others catch up.
Common Pitfalls That Cause Real Problems
The first and most frequent mistake is assuming that an exemption from federal registration means an exemption from state registration. They are separate questions. The safe harbor analyses differ, the eligible issuer categories differ, and the documentation requirements differ. Always run the state analysis independently. The second mistake involves the treatment of control persons. Federal registration requires disclosure of controlling persons. Some states require control person consent to service of process, and a few require the control persons themselves to sign the application. If your prospectus lists five control persons and your state application only has three signatures, the filing will be rejected. The examiner will not tell you this until after submission. The third mistake is forgetting about state securities registration for subsequent sales. Federal registration covers the initial distribution. But if you conduct a secondary offering or a private resales program, some states treat those as separate triggering events that require new state filings or at least amended notices. I worked on a case where a company completed its initial federal registration and state coordination smoothly, then launched a Rule 144A resales program six months later. Two states treated the resales as a new offering requiring full qualification because the original state registration had expired by operation of state law. The company had to pause the resales for three weeks while the filings were prepared and accepted.
A Practical Step-by-Step Walkthrough
Start by determining the states in which you intend to sell. This is not just where your investors live. It includes where your issuer is organized, where your principal place of business is located, and in some states, where your underwriters or placement agents operate. Each of those connections can trigger a filing requirement. Next, identify the exemption or qualification path for each state. For offerings registering on Form S-1 or S-3, coordination is usually the path. For private placements, you will likely be relying on state exemptions that mirror Section 4(a)(2) or specific state rule exemptions. Document the basis for each exemption in writing before you file. Examiners routinely ask for this, and having it ready cuts the review cycle significantly. Then prepare the state applications. Use the NAIC Uniform Application form as your base if the state accepts it, but check the state-specific supplement requirements. Some states require additional exhibits like a copy of the underwriting agreement, evidence of authority to sell in that state, or a separate fee calculation sheet. Missing exhibits are the most common reason for deferrals.
File the applications with the coordination deadline in mind. If you are coordinating with a federal registration, your state filing must be received before or on the effective date of the federal registration, unless the state allows a grace period, which most do not. Calculate the mailing time if you are submitting physically, though almost all states accept electronic filing now through the Electronic Filing System or their own portals. Finally, respond to examiner comments promptly and specifically. A one-line response to a multi-part question will not work. If the examiner asks about your revenue recognition policy and your related-party transactions, answer each part separately and reference the relevant prospectus pages. Examiners appreciate clear cross-references because it speeds up their review, and a faster review means a faster effective date.
Where the States Securities Act Of 1933 Framework Falls Short
The system works, but it is not efficient. The lack of true national reciprocity means that every additional state adds linear cost and time. There is no centralized state filing portal. Each state maintains its own queue, its own examiner expertise, and its own procedural quirks. A filing that goes smoothly in one state may raise questions in another about the same disclosure. The system was designed before the internet, and while it has modernized, the underlying structure remains fragmented. If you are running a nationwide offering with investors in many states, the only realistic way to manage this is to maintain a detailed jurisdiction tracker and budget extra time for states with longer review cycles. There is no shortcut around the fragmentation. The federal framework provides the registration shell, but the state layer is where the actual work happens, and it requires deliberate, jurisdiction-by-jurisdiction attention.