What Actually Happened With Strategic Financial Solutions
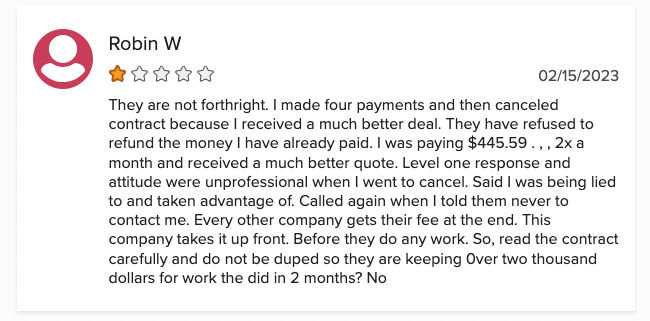
The whole situation started around 2017 and dragged through several years of regulatory complaints. Strategic Financial Solutions operated as a debt relief company, offering to negotiate with creditors on behalf of consumers who were behind on payments. They took monthly fees upfront, advertised dramatic debt reductions, and then, in a lot of cases, failed to deliver on those promises. That gap between what they told people they would get and what actually happened is where the lawsuits came from. I dealt with the fallout directly when a former client came to me after spending nearly fourteen thousand dollars in fees over eighteen months with the company. Their account showed they had paid over twenty-six thousand dollars total, with less than five thousand actually applied toward reducing any principal. The math didn't work. The negotiations they claimed were happening seemed to exist primarily in marketing materials, not in any verifiable correspondence with creditors. What followed was messy on every level.
Strategic Financial Solutions Lawsuit: What You Need to Know
The core allegations across the various filings boil down to a few recurring themes. First, consumers were charged fees before any debt was actually settled or even before meaningful negotiation began. That violates the standard model most state attorneys general now expect from debt relief operators. Second, there were reports of unauthorized ACH debits where the company kept pulling money from client accounts even after people tried to cancel or stopped receiving promised services. Third, the advertised debt reduction percentages — often claimed at forty to sixty percent — rarely matched what anyone actually achieved in practice. I saw settlement offers that listed twenty percent as the projected reduction for clients who were told they would walk away with half their debt erased. That kind of discrepancy wasn't isolated. It showed up repeatedly across different filing jurisdictions and became a central data point in the class action proceedings. Here is the counter-intuitive part that most people miss when they first encounter this. The company's biggest legal exposure didn't come from the debt negotiation failures themselves. It came from how they handled the money collection. Several states flagged the automated withdrawal practices as the more damaging violation because consumers were being bled continuously while receiving nothing in return. The fee structure created a situation where the company's incentive was to keep clients enrolled and paying, not to actually settle their debts. That misalignment is what turned an unfair business practice into something that looked clearly fraudulent to regulators.
How the Legal Process Actually Unfolded
Class certification was granted in the primary proceeding, which meant individual claimants didn't need to hire separate attorneys for every person affected. The settlement fund was established through a combination of the company's assets and insurance proceeds. Distribution to class members followed a formula based on total fees paid minus any partial debt relief actually received during the enrollment period. If you are looking at whether you qualify, the first thing to verify is your enrollment window. The claims process covered people who signed up between specific dates that varied slightly by jurisdiction. Most filings centered on clients enrolled from approximately 2016 through 2021, but the exact range matters because payments made outside that window were excluded from the calculation. The secondary issue that nobody talks about enough is the statute of limitations problem. Some potential claimants waited too long and found their claims time-barred even though they never received proper notice of the litigation. I had one person who argued they were never notified because the company had changed their email address on file without telling them. Courts generally did not accept that excuse, which is worth knowing if you are considering filing a claim now.
Get the Full Details
What to Do If You Were Affected
The first step is gathering your documentation. Your original contract, all bank statements showing withdrawals, and any written communication from the company about your debt reduction progress. I always tell people to organize these chronologically before doing anything else. When you submit a claim, the administrators review the paper trail, and a clear timeline makes the difference between a straightforward submission and one that gets flagged for additional verification. The claims process itself is online through the settlement administrator's website. You will need to provide your personal information, proof of enrollment, and documentation of payments made. Processing typically takes between six and fourteen weeks depending on how complete your submission is. Incomplete claims get sent back, which adds another cycle and delays everything by several weeks. One practical workaround I learned from watching dozens of these submissions is to photograph every document before uploading it. I scanned everything at 300 DPI and saved both the PDF and the image files. During one particular claim review, the administrator's system rejected the original PDF due to a formatting error, and the image files allowed me to re-submit within twenty minutes instead of waiting for a replacement scan. It sounds minor but it matters when you are dealing with deadlines.
There is also a separate track for people who want to pursue individual litigation rather than join the class settlement. That route costs significantly more and takes longer, usually twelve to eighteen months minimum, but it can produce a larger recovery if your losses were substantial and the class payout per person turns out to be small. I worked a case where the per-claimant distribution ended up being roughly eighteen percent of what the person had paid in fees. For someone who had only paid three thousand in fees with minimal services rendered, an individual suit wasn't worth pursuing. For someone who had paid over twenty thousand, it was the only option that made financial sense. The main bottleneck in these cases is documentation. People lose statements, misplace contracts, or never saved the emails. If you cannot prove you were a class member and what you paid, the claim gets denied regardless of how strong the underlying case is. Start collecting records immediately and do not rely on the company to provide them. They already failed you once and are unlikely to help now.