Why Most Accounting Departments Fail at Strategic Planning
Most accounting departments don't actually do strategic planning. They do a budget exercise and call it a strategy. There is a difference, and it is the difference between a department that gets promoted for fixing problems before they arrive and one that spends every quarter fighting fires. I learned this the hard way during a transition where my team was expected to close the books five days faster while simultaneously implementing a new revenue recognition standard. We had a strategy document. It was twelve pages long, printed in binders, and gathered dust in a cabinet that nobody opened after the kickoff meeting. The actual work happened in Slack threads, Excel files named Close_Schedule_v4_FINAL.xlsx, and whatever the lead accountant remembered from the last team meeting. Here is how you actually make strategic planning work in an accounting environment, not the version that looks good in a boardroom presentation.
The Core Method: Build From Bottlenecks, Not From Goals
Strategic Planning For Accounting Department operations should always begin with a bottleneck audit. Before you set any goals, map where your team loses time. Month-end close? Track every step and timestamp it for three consecutive cycles. Payroll processing? Document every exception and the handoff points. Reconciliations? Count how many are manual versus automated and where the manual work lives. The bottleneck will show you what to prioritize. If your close is taking 12 days and five of those are spent waiting on data from three different systems, your strategy is not about working faster. It is about fixing the data pipeline. I watched a team try to solve a 12-day close by requiring staff to work weekends. They hit 10 days and burned out. The real fix came from building an automated data aggregation layer that eliminated the waiting period entirely. A counter-intuitive insight most people miss: In accounting, the biggest efficiency gains rarely come from doing existing tasks faster. They come from eliminating entire categories of work that exist only because of legacy system limitations or historical workarounds. The manual journal entry adjustment that your team has been making every quarter since 2018 probably does not need to exist anymore. Challenge the work itself, not the speed of the work.
Setting Priorities That Actually Get Executed
Accounting departments operate under constraints that most strategic planning frameworks do not account for. Regulatory deadlines are non-negotiable. Audit requirements create hard gates. Headcount is usually fixed. These constraints mean your strategy has to be brutally realistic about what is possible within the operating rhythm of the function. The framework that works looks like this: Phase one: Baseline measurement. Take four weeks to measure everything. How long does each process take? Where do errors occur? What is the rework rate? What percentage of time is spent on strategic versus operational work? This baseline is your single most important data point. Without it, every goal you set is a guess.
Get the Full Details

Phase two: Objective setting tied to measurable outcomes. Do not write goals like "improve efficiency." Write goals like "reduce month-end close from 12 days to 7 days by automating intercompany reconciliations and eliminating manual variance explanations." Specificity forces clarity and makes failure visible. Phase three: Initiative mapping with resource reality checks. For each objective, identify the specific initiatives required. Then check against actual capacity. If you have three people on the team and one is on maternity leave for six months, your plan needs to reflect that. I once saw a strategic initiative slip by eight months because nobody factored in a planned transition that would remove two senior staff members during the critical execution window. Phase four: Timeline with built-in buffers. Accounting work has inherent variability. Tax filing season disrupts everything. Audit periods consume bandwidth. System migrations cause temporary slowdowns. A realistic timeline accounts for these disruptions rather than assuming continuous operating capacity.
The Metrics That Actually Matter
Most accounting departments track output metrics—number of invoices processed, number of reconciliations completed. These tell you nothing about strategic progress. The metrics that matter are leading indicators: Track these monthly. Review them in a standing leadership meeting. When the numbers move in the wrong direction, you should know within 30 days, not at the next annual strategy session. The first pitfall is treating strategic planning as an annual event. The business environment changes fast enough that a plan finalized in January may be obsolete by March. Accounting, with its regulatory and compliance dimensions, changes even faster. New standards get issued. Tax laws shift. System upgrades disrupt workflows. Your planning cadence should be quarterly reviews with monthly checkpoints.
The second pitfall is over-relying on software solutions. I have seen teams spend six months and $200,000 on a financial planning and analysis platform that solved none of their actual problems. The bottleneck was not the tool. The bottleneck was that the underlying processes were broken. Automation magnifies existing process quality. It does not fix poor processes. Another thing people get wrong: Strategic planning in accounting requires more stakeholder alignment than almost any other function because accounting touches every part of the business. Sales needs revenue recognition clarity. Operations needs cost allocation transparency. Treasury needs cash flow predictability. If your strategy only reflects accounting's internal priorities, you will create friction with the very departments you need to cooperate with. Build cross-functional input into the planning process from the start, not as an afterthought.
What This Approach Cannot Do
I want to be straightforward about where strategic planning for an accounting department hits hard limits. In organizations with fewer than five accounting staff, the overhead of formal strategic planning often outweighs the benefits. Small teams need flexibility and rapid adaptation more than structured planning cycles. The approach works best at five or more FTEs where there is enough complexity to justify the structure. For high-growth companies where the business model changes every 12 to 18 months, detailed multi-year accounting strategies tend to become obsolete before they are fully executed. In those environments, a rolling 90-day planning cycle with rapid reassessment is more effective than an annual strategic plan.
Some organizations treat the accounting function as purely transactional and refuse to invest in the infrastructure that strategic planning requires. No amount of planning methodology will compensate for a leadership team that views accounting as a cost center to be minimized rather than a function to be optimized.
Practical Execution Steps
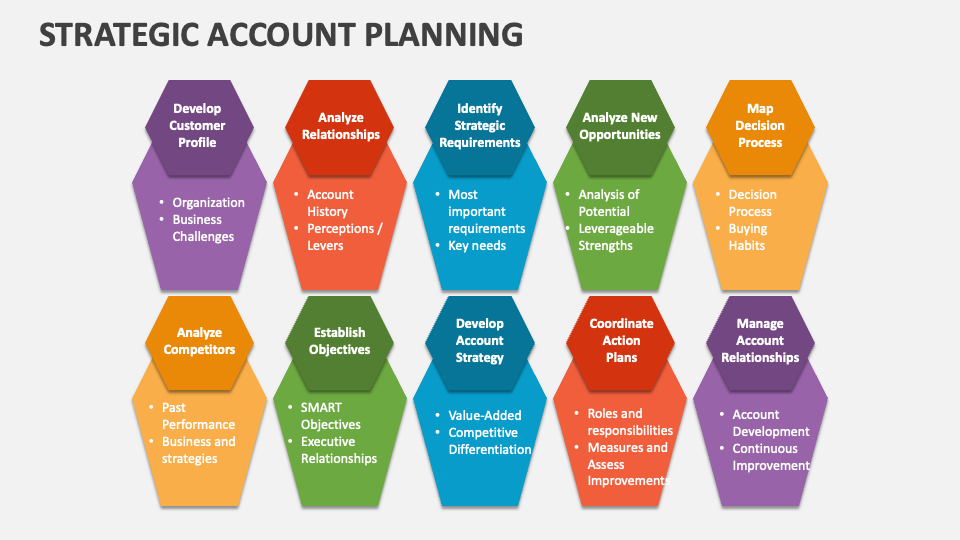
Start tomorrow with a process time study. Pick your most critical recurring process—likely the month-end close—and have each team member document every step they take, the time each step requires, the systems involved, and the handoff points. Do this for two full cycles. The data will shock you. Most teams have no idea where their time actually goes until it is measured. From that data, identify the top three bottlenecks. Not ten. Three. Then build a plan that addresses those three with specific initiatives, assigned owners, measurable targets, and timelines. Review progress monthly. Adjust quarterly. Repeat. The gap between a strategic planning document that collects dust and one that actually changes how the department operates is usually just one thing: consistent follow-through on a small number of priorities instead of ambitious coverage of everything. Accounting departments that improve are the ones that pick a few meaningful battles and fight them systematically over multiple quarters.