The Actual Work of Getting Out From Under What You Owe
Most people think debt payoff is a math problem. It isn't. It's a sequence of behavioral decisions made under stress, usually while you're already short on cash. The spreadsheet looks clean. Real life is messier.
I've been paying down consumer debt for about eleven years across three different rounds — credit cards, a car note, and a small personal loan I took on a whim in 2019. I learned things the hard way. Here's what actually moves the needle.
Strategies For Paying Off Debt That People Actually Use
The two main frameworks are the avalanche method and the snowball method. Avalanche targets highest-interest debt first. Snowball targets smallest balance first. Both work. Neither is neutral.
Avalanche saves you money. On a typical mix of 22% credit card and 7% auto loan, attacking the card first shaves roughly $340 in interest per $5,000 of balance compared to minimum payments alone. The math is clear.
Snowball preserves momentum. Clearing a $400 medical bill in month two gives you a visible win that most people need to keep going. Behavioral economists call this "quick feedback loops." I call it not quitting.
The truth is neither method matters as much as consistency. A mediocre plan executed for eighteen months beats a perfect plan executed for three. I learned this after switching strategies twice in my first year and making zero progress both times.
Here's how I structured my current round. I have four balances: a Chase card at 24.99%, a Costco any visa at 19.9%, a car note at 6.2%, and a SoFi personal loan at 11.4%. I'm running avalanche with a modified snowball trigger. When a balance drops below $500, I switch to clearing it regardless of rate. This happened in month seven with the Costco card and it changed my trajectory because it freed up $89 in monthly minimums that I redirected immediately.
Setting Up the System Before You Start
List every debt with its balance, rate, and minimum payment. Not from memory. Pull the statements. I once thought my medical debt was $1,200. It was $1,847. The gap felt small until I factored it into my payoff timeline and realized I was behind by three months.
Automate the minimums on everything. Every forgotten minimum triggers a late fee, which raises your utilized balance, which nudges your credit score down, which sometimes reopens rates. One missed payment on a 29% card costs you $45 immediately plus potential rate increases that last years. Set it and ignore it until you're ready to attack.
Build a $1,000 buffer before aggressive payoff. This is non-negotiable. Without it, a $200 car repair forces you onto another card, which adds to the pile you're trying to shrink. I ran this experiment once by skipping the buffer in 2020. My water heater failed. I put $680 on the card I was trying to kill. It took fourteen months to recover.
The Method in Practice
Avalanche workflow: after covering rent, food, utilities, and all minimum payments, every extra dollar goes to the highest-rate balance. When that balance hits zero, redirect that total payment amount to the next highest rate. Repeat.
The redirect step is where most people fail. They see a paid-off card and think "I can breathe now." They don't. The payment amount stays committed. If you were putting $289 monthly at the 24.9% card and $150 at the car note, the card payoff doesn't free up $289 to spend — it frees up $289 to redirect at the next target. That's the engine.
I used a simple Google Sheet. Columns: creditor, balance, rate, minimum, target payment, extra. The extra column calculated automatically. Each payoff triggered a cascade recalculation that I reviewed monthly. The whole thing took about twelve minutes per review.
There's an edge case that tripped me for months. My Chase card had a balance transfer offer — 0% for fifteen months, then 24.99% retroactively on the transferred amount if not paid in full. I transferred $3,200 to stop the bleeding while I built runway. The problem: the minimum payment on the new card was calculated on the full transferred amount, not my old payment. My minimum jumped from $96 to $128. I hadn't budgeted for that increase. I missed a payment. The 0% rate voided retroactively. I owe $3,200 plus roughly $240 in back-interest at 24.99%. This is the single most expensive mistake I've made with debt.
The workaround: before any balance transfer, calculate the new minimum. If it exceeds your capacity, don't transfer. The 0% rate is worthless if you miss one payment and the void clause triggers. Read the terms. The void clause is usually in section 4 or 5 of the agreement, buried after the marketing language.
When Strategies Stop Working
Debt payoff strategies break down in three scenarios.
First, income volatility. If you're on commission or hourly with unpredictable schedules, fixed monthly extra payments become a liability. You'll either underpay during lean months or overcommit and miss. The fix is percentage-based payoff — direct a flat percentage of whatever hits your account each month, not a fixed dollar amount. This kept me functional during a six-week pay gap in 2022 when my hours dropped 40%.
Second, high-interest medical or emergency debt. Standard avalanche doesn't account for collection risk. A $4,000 medical bill in collections doesn't care about your payment schedule. It cares about statistics. The moment a debt hits collections, the strategic priority flips. Negotiate a settlement for 40-60% of the balance before starting any structured payoff. One settlement conversation saved me $1,100 on a $2,750 dental bill that had been sold to a collection agency. I paid $1,350 and closed it. The remaining $1,400 in theoretical savings disappeared because I hadn't acted fast enough.
Third, relationship debt. When someone else's spending created the obligation, the standard frameworks don't address the underlying friction. I worked through this with my partner by separating tracked balances — some debts were individually owned, some shared. We paid shared debts proportionally to income and individual debts separately. This prevented resentment from building around who was "carrying" what. It took three months to set up the tracking system. It saved the relationship more than the money.
Concrete Steps for This Month
Pull your three most recent statements for each creditor. List balance, APR, and minimum. Calculate your total minimum obligation. Subtract from your take-home pay. Whatever remains is your attack budget. Assign it using avalanche or snowball based on whether you need math optimization or psychological momentum. Automate the minimums. Set a calendar reminder for the 15th of each month to review and redirect. Do not skip the redirect step.
If you have a balance transfer offer sitting in your email from the last six months, check the expiration date. Most are 60-90 days old by the time you find them. If it's expired, it's expired. Don't reapply — the hard pull hurts your score and the rate you qualify for will likely be worse than what you already have.
The hardest part isn't the math. It's the eighteen-month plateau where progress feels invisible. I hit this in months ten through fourteen. My balance went from $8,400 to $7,900 — a $500 reduction over five months. It felt like nothing. It was actually three months of payments swallowed by interest. The redirect from the Costco card payoff in month seven didn't compound until month nine. This lag is normal. It's also why the buffer and the automation matter — they keep you from bailing during the invisible stretch.
I'm now at month twenty-two. Three balances down. Two remaining. The pattern holds: automate minimums, redirect aggressively, negotiate collections early, avoid balance transfers unless you've read the void clause, and never skip the redirect step even when you think you've earned a break. The break comes after the last balance hits zero, not before.
Gallery Strategies For Paying Off Debt
20 Tips to Pay Off Debt | Spergel | Debt free tips, Tips for paying off debt, Debt chart pay off
Fastest Way to Pay Off Credit Card Debt: Smart Strategies
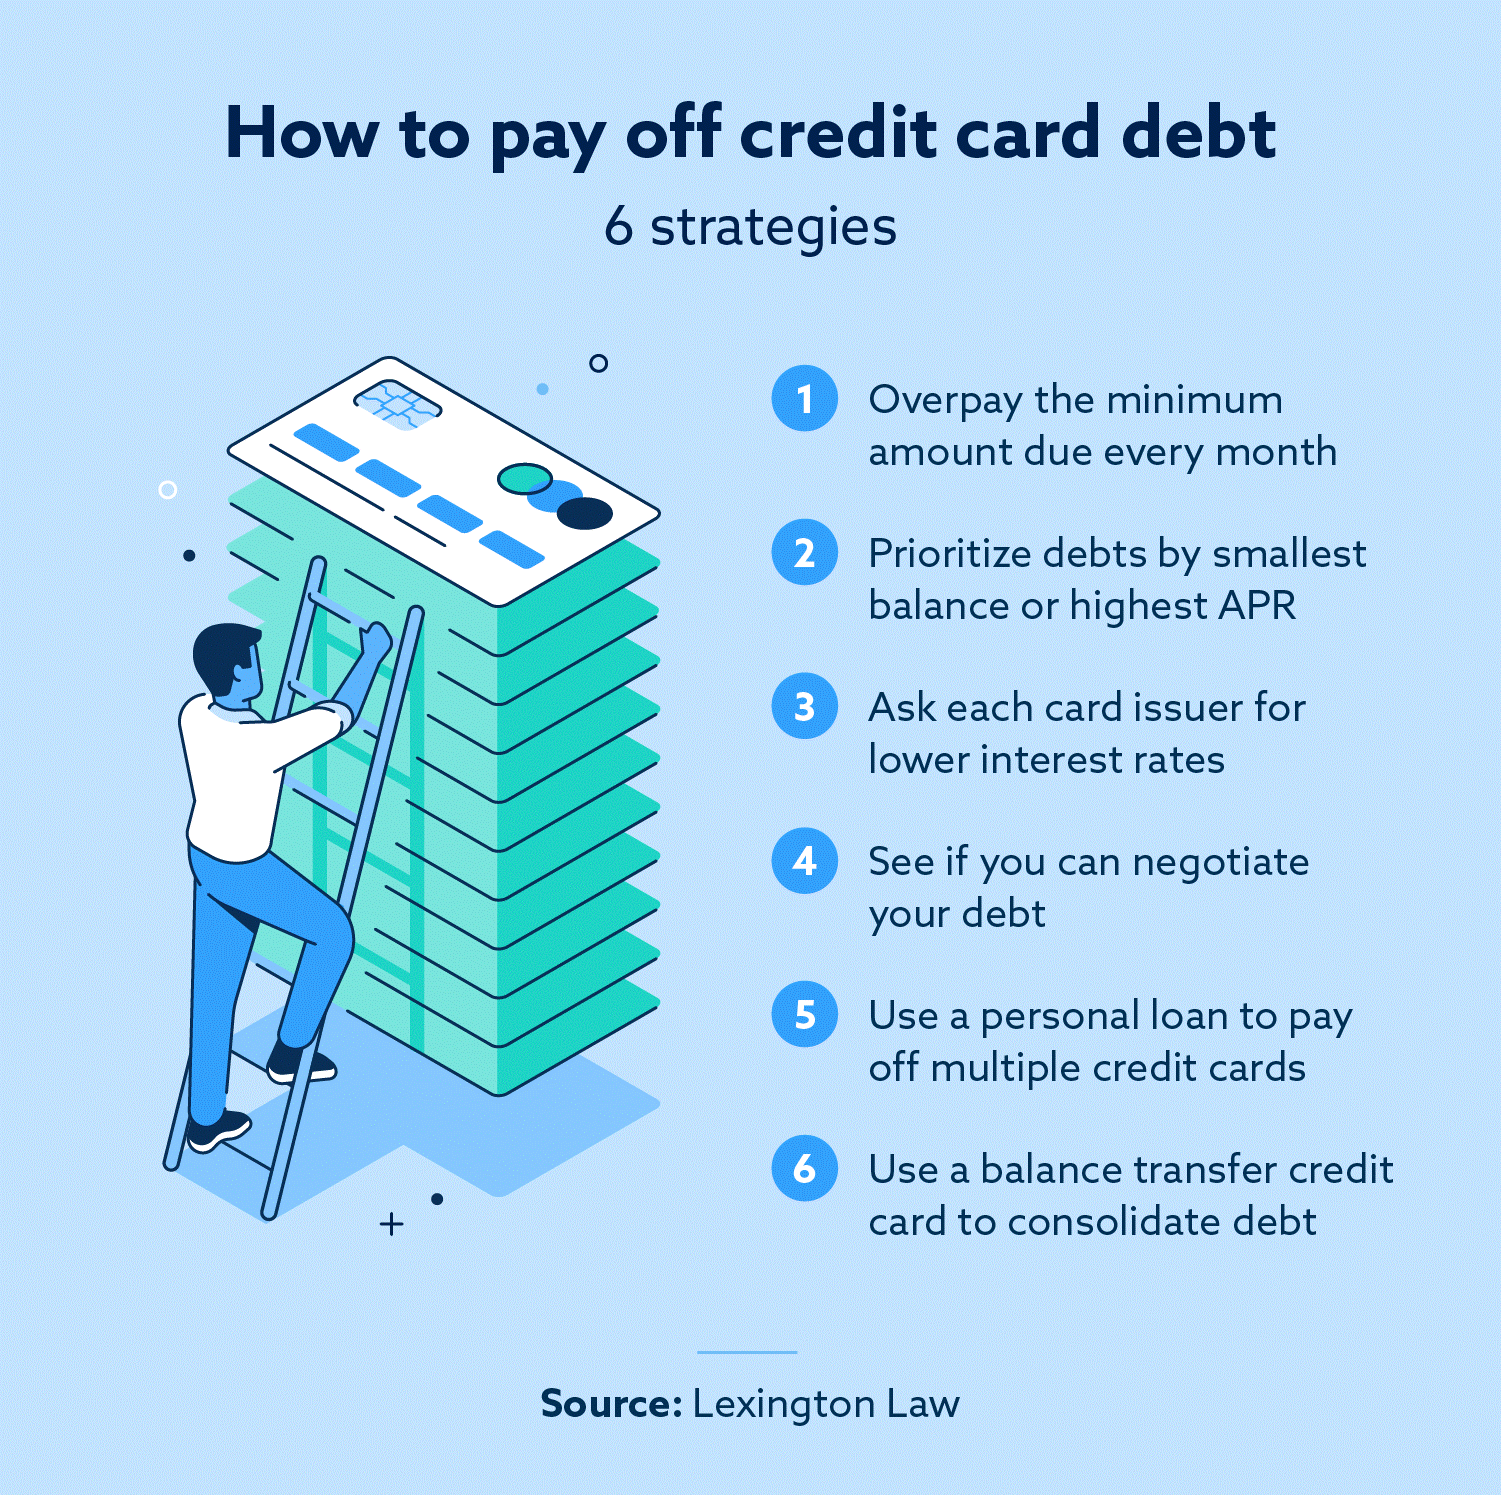
How to Pay Off Credit Card Debt: 6 Strategies | Lexington Law
20 Simple Tips on How to Pay Off Debt Fast | Money saving strategies, Debt payoff, Debt payoff plan
How to pay off debt – Artofit