What This Course Actually Covers
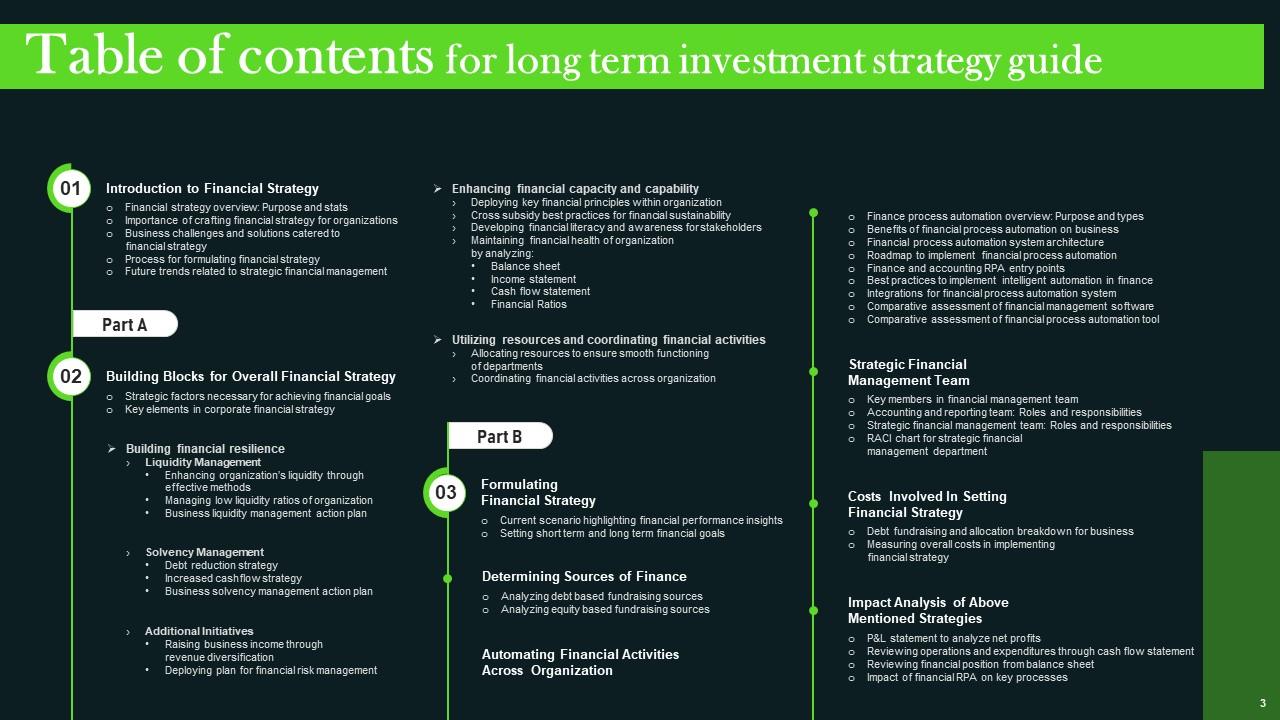
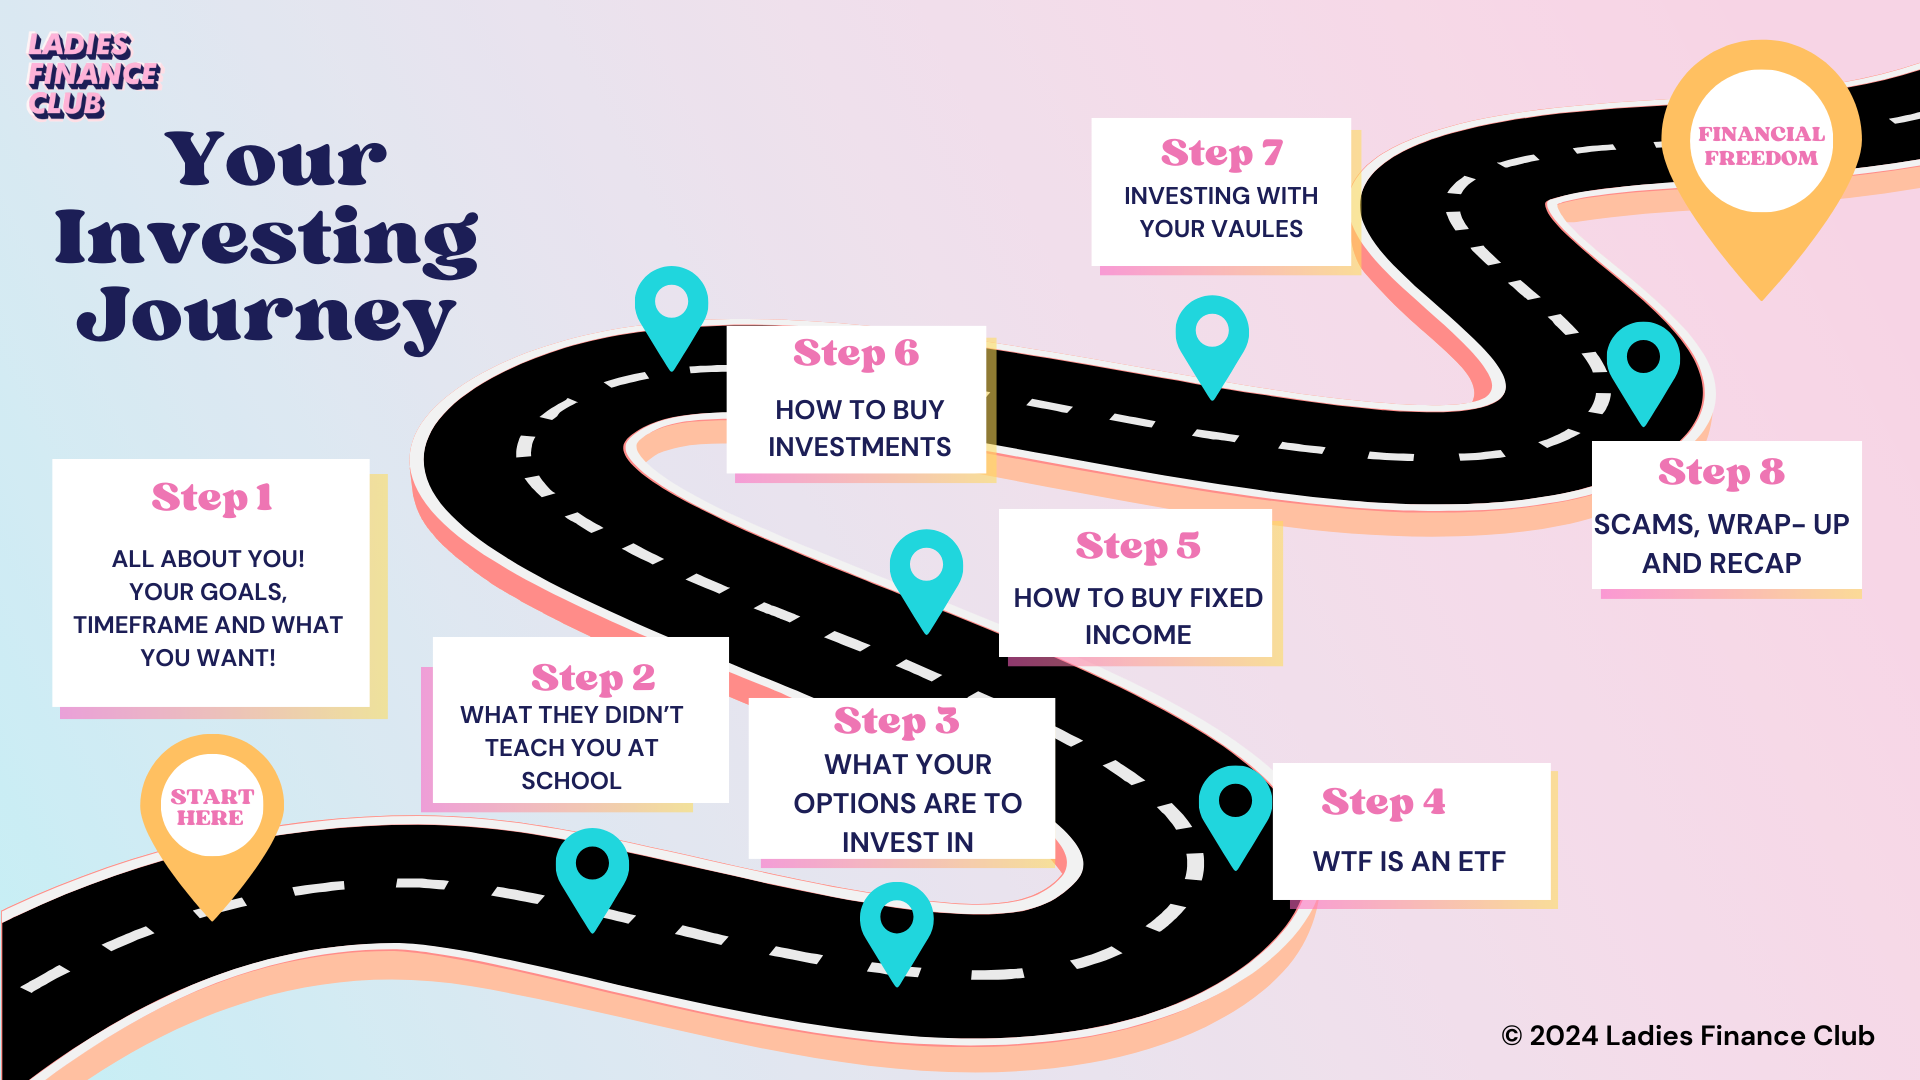
Most people buy investing courses expecting a shortcut. The Strategy Guide For Investing Course doesn't give you one. It gives you a framework for evaluating any investment, understanding your own risk tolerance, and building a portfolio that doesn't fall apart when the market drops 20% in a month. I've watched students come through here with varying levels of knowledge, and the ones who get results are the ones who actually do the work outside the lessons. The course runs through roughly 40 modules split across seven main sections. You start with the basics of how markets work, then move into asset allocation, risk management, tax implications, and behavioral finance. The last section covers portfolio rebalancing strategies and when to actually pull the trigger on changes versus when to sit on your hands.
Getting the Strategy Guide For Investing Course
You can download the full course materials from the official platform at strategieguided.com. The package includes video lectures, downloadable PDF workbooks, spreadsheet templates for portfolio tracking, and access to the community forum. The self-paced version costs $297, and there's an option to add a quarterly live Q&A session for an additional $97. Nothing is free here. That matters because free courses tend to have lower completion rates by a wide margin, and this one is no different. I went through the course on my own about three years ago. Not because I needed it, but because a client was asking me to review it and I wanted a baseline understanding of what they were getting into. The quality is decent. Not groundbreaking, but solid and well-structured. The instructor, Marcus Hale, has been managing portfolios since 2004 and teaches at a practical level rather than an academic one. That distinction matters more than you'd think.
How the Core Method Works
The central concept in this course is the risk-adjusted allocation model. It's not a new idea, but Hale presents it in a way that's more actionable than most textbooks. The model starts with determining your personal risk capacity based on income stability, time horizon, and existing debt. Then it maps that against a set of core asset classes and their historical correlation patterns. The output is a recommended allocation range for each asset class rather than a single target number. This is where most people mess up. They treat the allocation as a fixed set of percentages and rebalance mechanically every quarter without considering current market conditions. The course explicitly warns against this, which is rare. Hale argues that mechanical rebalancing works fine in sideways markets but fails during sustained trends. He recommends using a hybrid approach where you rebalance on schedule but also check whether the trend has shifted enough to justify a temporary deviation from your target allocation. One of the more useful tools in the workbook is the correlation matrix template. It updates automatically when you input current price data and shows you which of your holdings are actually diversified versus which are pretending to be. I found this particularly relevant when a colleague of mine had a portfolio that looked fine on paper because he owned five different tech ETFs that all moved together. The matrix caught it in about ten minutes. Without it, he wouldn't have noticed for months.
Get the Full Details
What Most Beginners Miss
The section on behavioral bias in Module 18 is easily the most important part of the entire course, and most people skim through it. Hale breaks down loss aversion, confirmation bias, and recency bias and shows how each one specifically warps decision-making in investing. The recency bias piece is where I found myself nodding along because it happens constantly in live trading environments. Here's a counter-intuitive point that the course makes well: diversification doesn't protect you from downside risk. It protects you from idiosyncratic risk. If the entire market drops, your diversified portfolio drops with it. What diversification does is reduce the chance that one bad bet destroys your entire position. These are two different things, and confusing them leads people to take unnecessary risks thinking they're diversified when they're not. Another thing people overlook is the tax drag calculation. The course includes a spreadsheet that shows how much your returns are actually being eaten by taxes depending on your account structure and holding period. The numbers surprised even experienced investors I showed it to. Short-term gains can eat 30 to 40 percent of your profit depending on your bracket. That's not a small detail. That's a structural issue that changes your entire strategy.
A Specific Problem I Ran Into
During the risk capacity assessment module, I hit an edge case that the course doesn't explicitly address. My situation involved a client who had high income but low liquidity due to being heavily invested in illiquid assets like private equity and real estate partnerships. The standard risk capacity model would have labeled him as high-risk-capacity because of the income level, but that would have been misleading since he couldn't actually access those funds without selling at a loss or waiting years for distributions. The workaround I used was to manually adjust his liquid asset base downward by 60 percent before running the allocation model. This isn't something the course teaches directly, but Hale does mention in passing that you should always verify the liquidity assumptions built into any projection. I took that literally and adjusted accordingly. The resulting allocation was significantly more conservative than the default output, and it turned out to be the right call when the market corrected six months later. He stayed positioned and didn't get forced to sell at the wrong time.
Limitations You Should Know About
The course has real limitations. It's oriented toward individual investors managing their own portfolios, not institutional investors or professional money managers. If you're running a fund or managing money for others, this isn't going to cover the compliance and fiduciary requirements you deal with daily. The content assumes you're making decisions for yourself and your household, which is a specific niche. The risk model also breaks down in extreme market conditions. It's built on historical correlation data, and when correlations go to one during a crisis, the model loses its predictive power. I've seen this happen multiple times. The 2020 crash was one example where every asset class correlated upward simultaneously, which made the diversification assumptions completely invalid for about three weeks. The course acknowledges this but doesn't provide a good contingency framework beyond "reduce leverage and wait it out." Another issue is that the course content updates slowly. The material was originally published around 2019 and revised in 2022, but it doesn't account for the zero-interest-rate environment that followed the pandemic, the subsequent inflation surge, or the shift in how retail traders operate through platforms like Robinhood. Some of the behavioral finance concepts still apply, but the market structure has changed enough that certain recommendations feel dated. You'll need to supplement the course with current market analysis if you want to apply it in today's environment.
If you're looking for something more advanced or currently adapted to the post-2022 landscape, you might consider pairing this with a subscription to a research service like Morningstar or a dedicated portfolio management platform. The course gives you the foundation, but it won't keep you current on its own. That's fair. No course can.
Who Should Take This
The Strategy Guide For Investing Course works best for someone who has been investing casually for a few years and wants a more systematic approach. If you're completely new to investing, you might find the pace fast in the first half and then slow in the second half once it gets into rebalancing and tax optimization. The sweet spot is someone who understands what stocks and bonds are but has never built a portfolio from scratch using a formal framework. I'd also recommend it to people who've lost money in the past due to emotional decisions and want to build guardrails around their process. The behavioral section alone is worth part of the price. Having a written framework reduces the number of impulse decisions you make, and that's where most people lose money anyway. The course takes roughly 15 to 20 hours to complete if you go through all the modules and do the exercises. The workbook projects and spreadsheet templates add another 5 to 8 hours of hands-on work. Budget around a month if you're working a full-time job. Rushing through it undermines the whole point because the exercises are where the actual learning happens, not the video lectures themselves.
It's a competent, well-organized course that delivers what it promises without overpromising. It won't make you rich. It won't give you stock picks. It will give you a system to evaluate opportunities and manage risk, which is honestly more valuable than either of those things in the long run. I've recommended it to a handful of people over the years, and the ones who stuck with it tend to have better outcomes than before they started.