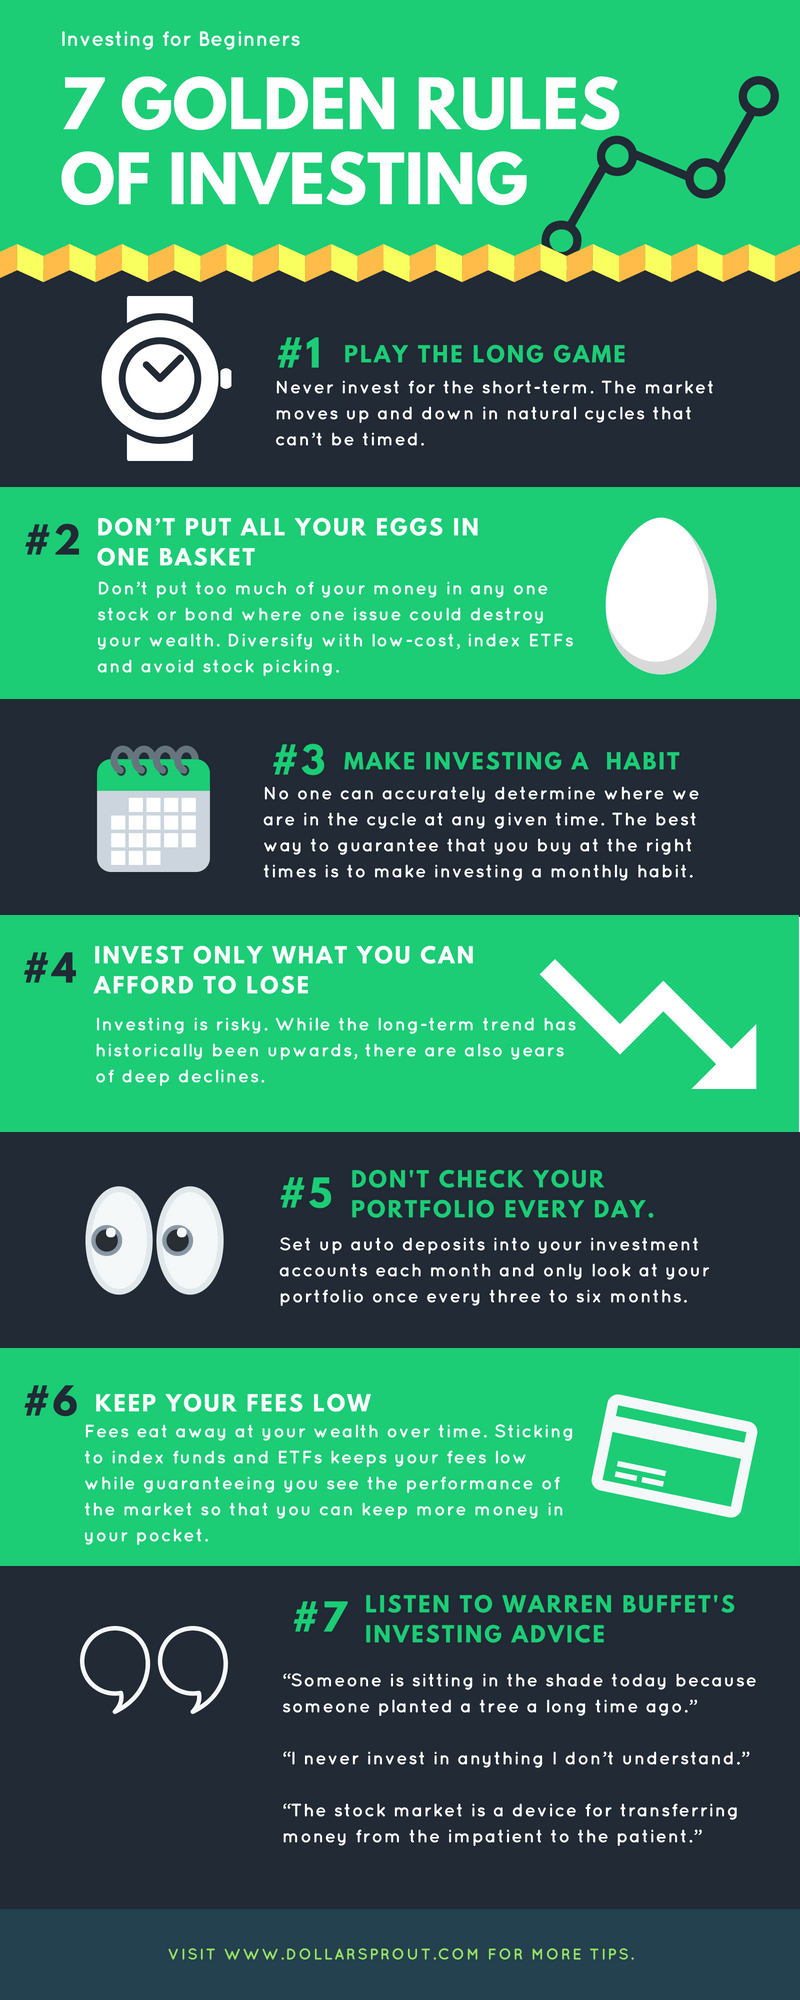
The mechanics of keeping your portfolio from falling apart
Most people treat style guides like they're decorating a cake. They pick colors, choose fonts, arrange things to look nice. Investing isn't decoration. It's load-bearing. You don't get to eyeball it when the roof caves in. I spent three years working with fund managers who had no systematic approach to risk allocation. Two of them blew up a fund because they kept doubling down when positions moved against them. The third one was fine for eight years, then lost forty percent in six months because nobody had written down what "enough" actually meant for any given position. That's not bad luck. That's missing the style guide.
What Style Guide For Investing Best Practices actually covers
A style guide for investing is the document that says: when you see X, you do Y. Not maybe. Not let's discuss. You do Y. It covers position sizing, entry criteria, exit triggers, rebalancing schedules, and the specific conditions under which you override the rules. The override section matters most. Every strategy gets violated eventually. If you haven't written down when you're allowed to break the rules, you'll break them for the wrong reasons. The common mistake is making the document too long. I've seen guides that run eighty pages. Nobody reads them after week two. The effective version fits on three screens. If yours doesn't, cut it down.
Writing the document itself
Start with the exit rules. People always start with entry rules because that's the exciting part. Entry rules are easy. Exit rules are where careers end. Write down exactly when you sell. Not "when it looks bad." A specific threshold. Ten percent below cost basis. Thirty days without the thesis playing out. Maximum position size of twelve percent regardless of conviction level. Concrete numbers. Not feelings. Next section: position sizing. This is where most retail investors destroy themselves. The rule should state maximum exposure per sector, per single position, and per correlated basket. I keep one fund at eight percent per name, five sectors maximum, and if two positions in the same sector move against me simultaneously, both get trimmed to four percent automatically. No discretion. The discipline is in the automation. The controversial part most guides skip: drawdown limits. What happens when the portfolio drops twenty percent? Twenty-five? Thirty? Write the response before you need it. When markets crashed in early 2020, the funds that survived were the ones that had already decided what to do during a crash. The ones that didn't panic-sold at the bottom because they were making the decision emotionally in real time.
Get the Full Details

Building a Style Guide For Investing Best Practices that you'll actually use
Make it a living document, not a museum piece. Review it quarterly. Update the numbers, not the principles. The principles can stay the same for a decade. The thresholds need to adjust as your capital base changes and as market regimes shift. In a low volatility environment, a ten percent drawdown means something different than in a high volatility one. Here's the thing nobody tells you: the best style guides are boring. If yours reads like an inspiration poster, you wrote it wrong. It should read like a technical manual for a machine that occasionally explodes. Dry. Specific. Unemotional. Test it against your worst historical decision. Pick the trade you regret most. Run it against the document. Did the guide allow it? If yes, the guide is wrong. If no, the guide worked and you ignored it anyway — which means you need a harder constraint, not a new section. Usually that's a hard pre-trade approval rule or a forty-eight hour cooling period for any position over eight percent.
The edge case that caught me off guard: when you inherit a portfolio from someone else who didn't write anything down. You're operating on institutional memory that died with the person. The workaround I use is to reverse-engineer their actual behavior from trade history. They bought tech at twelve percent of portfolio? That's your baseline. Then you add constraints around it. You don't strip their decisions down immediately because that creates whiplash. You layer rules on top until the behavior stabilizes, then you clean up the document.
Common failure modes
Option paralysis. You spend so much time writing contingencies that you never trade. The fix is setting a date when the guide goes live regardless of completeness. You'll discover gaps in month three and update accordingly. A flawed guide used aggressively beats a perfect guide that lives in a drawer. The second failure mode: making it too rigid. Markets don't follow rulebooks. When a fundamental shift happens — interest rates moving from zero to five in eighteen months, like we just saw — your old thresholds are noise. Build in a review trigger. "If the Fed moves rates by more than one hundred basis points in a quarter, all position sizing rules enter emergency review." That's how you stay disciplined without being blind. Don't overfit to recent history. I watched a manager in 2021 build an entire style guide around low-rate, high-liquidity conditions. It worked beautifully until 2022. The guide itself wasn't wrong, but it was incomplete. It didn't account for the regime change because the regime change hadn't happened yet. Account for that by stress-testing your rules against at least two historical episodes that look nothing like today.
The download structure
If you want the actual template, here's what goes in it. Everything else is commentary on why those sections exist. Section one: investment philosophy. Three sentences. No more. If you can't summarize it in three sentences, you don't understand it well enough to enforce it. Section two: position sizing rules. Maximum per name. Maximum per sector. Maximum per correlated group. Scaling in and out procedures.
Section three: entry criteria. What must be true before you buy. Hard requirements only. Not preferences. Not "nice to haves." Section four: exit criteria. Same format. Hard requirements. Price targets, time-based exits, thesis invalidation triggers. Section five: portfolio-level constraints. Total exposure limits. Cash drag tolerance. Rebalancing triggers.
Section six: override protocol. When you can deviate, what approval you need, what you document afterward. This section prevents emotional decisions from becoming permanent ones. Section seven: review schedule. Quarterly updates. Annual rewrite. Trigger events that force immediate review. That's it. Three screens. If you need more, you're documenting decisions you haven't made yet. You'll figure those out when they come up.
The one thing I wish someone had told me before writing my first version: include the documentation requirements. When you override a rule, you write down why in three lines before the trade executes. Not after. Not the next morning. Before. This alone prevented me from making at least twelve bad decisions that I would have otherwise rationalized into permanence. The act of writing forces honesty that thinking doesn't. Also worth noting: this doesn't scale down well for absolute beginners with under twenty thousand to invest. At that level, the overhead of maintaining a style guide exceeds the value of the discipline it provides. Index funds and forget-it works better until you have enough capital at risk that process matters. If you're reading this and you're in that boat, skip the guide. Just buy the index and stop checking the balance. When you have the capital, though, the guide is the difference between building wealth and building stories about what you almost did right.


